Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
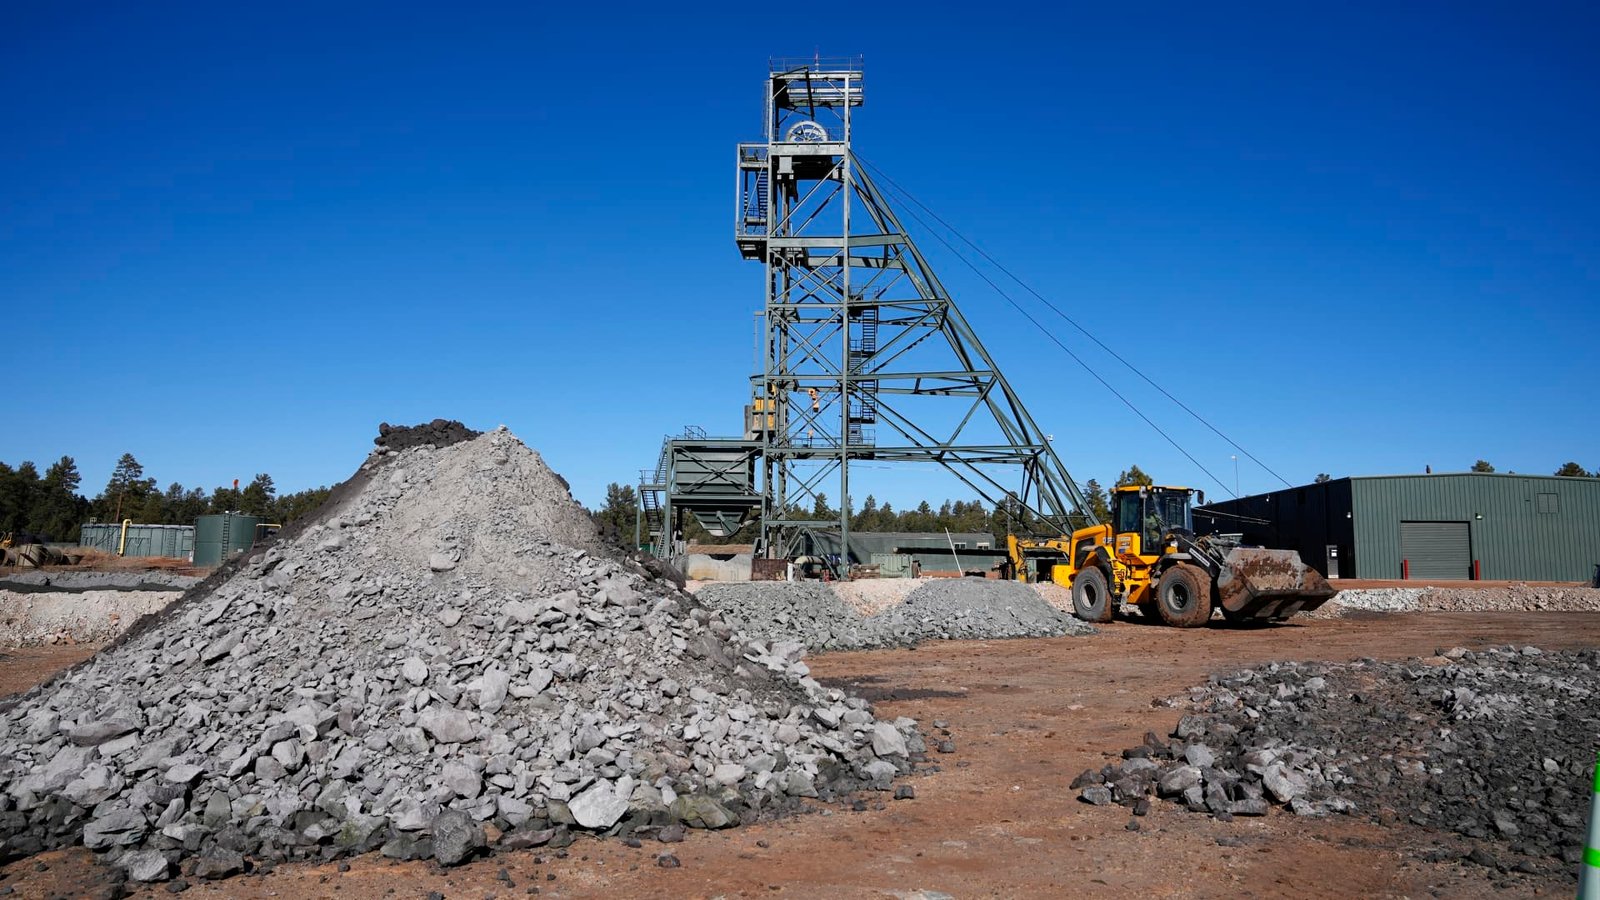
 LivestreamMenuNexGen Energy is likely to see considerable upside as it gets closer to completing its massive uranium mine, according to JPMorgan. The investment bank initiated coverage of the clean energy stock with an overweight rating. It also set a $14 price target on shares, implying 50% upside from Friday’s close. Shares were up nearly 3% in trading on Monday. “[NexGen Energy’s] portfolio screens favorably in terms of grade ( > 2%), scale ( > 10% market) and jurisdiction (Canada),” analyst Bill Peterson said Monday in a note to clients. “Equally important, the project is fully permitted, is well supported by funding providers and we see a path to a multi-decade mine life as adjacent prospects are integrated into the mine plan.” NexGen is constructing a large high-grade uranium mine and mill in Canada under its Rook I Project, which is expected to be completed by 2030. The mine will aim to produce 30 million pounds of uranium per year, according to NexGen. That should drive major upside to shares of NexGen, even though the project is far from finished and poses risks, per JPMorgan. “While construction is not without risk, we see headline risk as longer-dated and valuation as undemanding, resulting in an attractive risk-reward,” Bill Peterson wrote. The analyst added that similar uranium mine projects are not fully permitted, giving NexGen an edge over competitors and making its stock especially appealing to investors. In addition, the stock “offers a rare combination of tier-one asset quality and long-dated growth optionality” compared with other critical mineral names covered by JPMorgan, according to Peterson’s note. JPMorgan’s call lines up with consensus on Wall Street. All eight analysts covering NexGen Energy have a buy or strong buy rating on the stock, LSEG data shows. Shares have ticked up nearly 2% year to date, and the average analyst price target anticipates the stock will more than double from here.Read More
JPMorgan says this uranium stock can rally more than 50%
NexGen Energy is likely to gain a lot of ground as it makes progress on its Canadian uranium mine, which is set to be completed in 2030, per JPMorgan.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets news People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports