Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
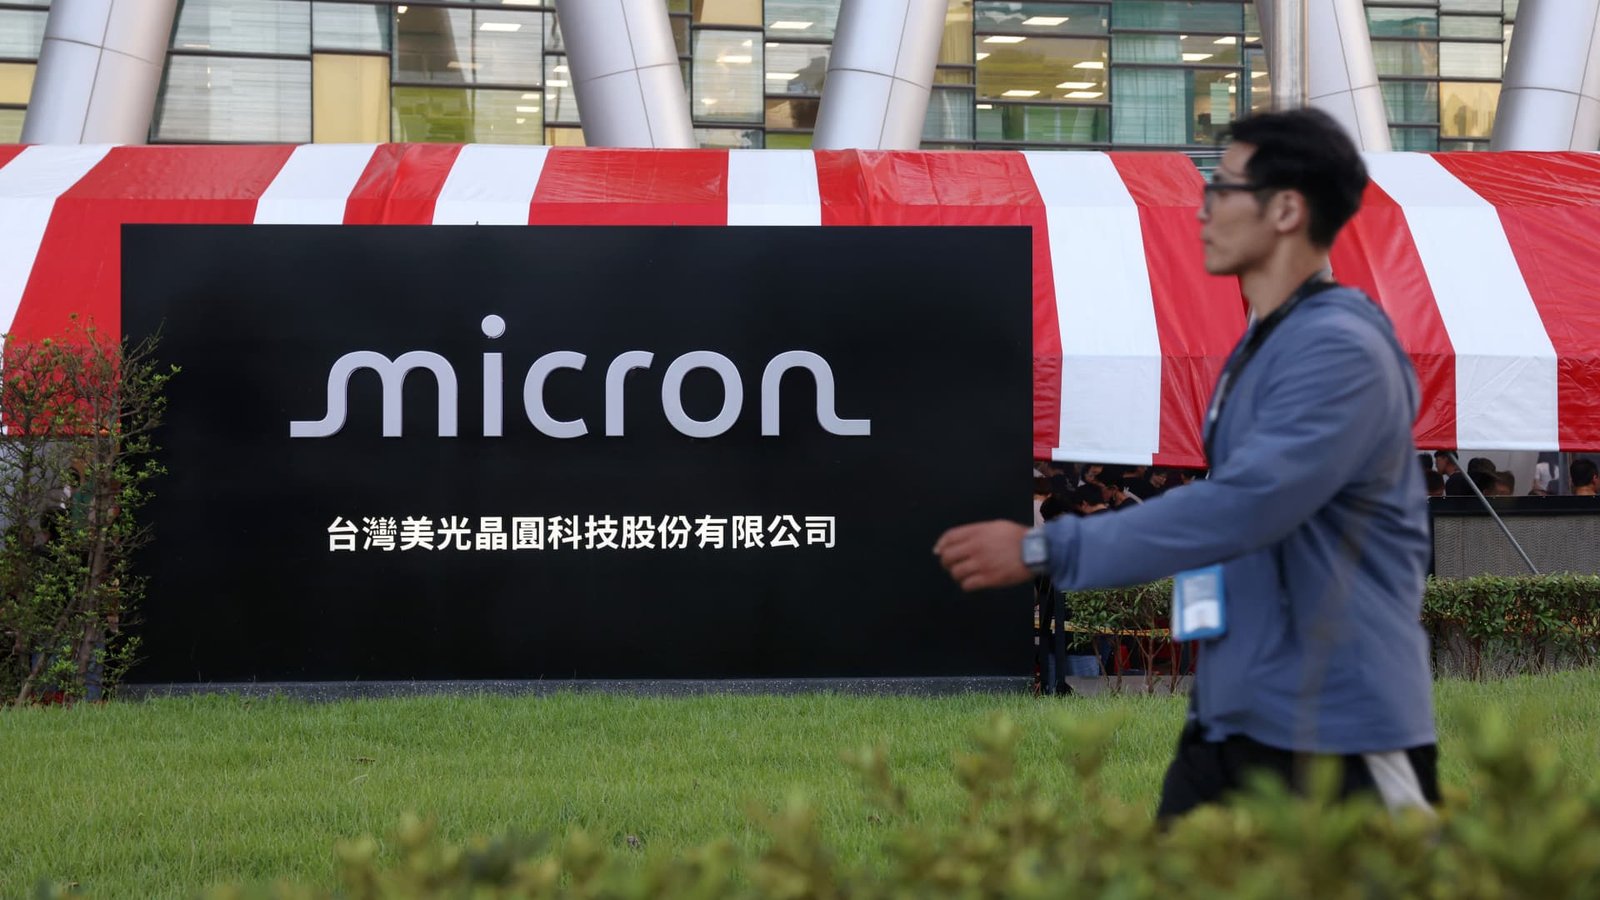
 LivestreamMenuMicron Technology posted strong quarterly results on Wednesday, giving analysts plenty of reasons to be bullish on the stock. The memory-chip company posted adjusted earnings of $33.42 per share for the fourth fiscal quarter, exceeding the $31.61 expected by analysts polled by LSEG. It also clocked $54.23 billion in revenue, topping the Street’s consensus of $51.07 billion. That figure came in nearly four times higher than revenue for the same period a year earlier. The chipmaker also issued better-than-expected forecasts for the current quarter. Micron sees adjusted earnings of $38.15 per share on revenue of about $61.5 billion for the first fiscal quarter, well above what the Street had penciled in. Shares of Micron hardly moved following the earnings report, however. The stock was flat in premarket trading. That marks a stark contrast to Micron’s performance since 2026 began. Shares are jumped 273% year to date thanks to a memory demand boom fueled by an acceleration in artificial intelligence adoption. MU YTD mountain Shares are up 273% in 2026. That demand is expected to only continue gaining steam, catapulting shares of Micron even higher in the near future, according to Deutsche Bank. “We remain highly constructive on the memory sector and MU in particular, with industry fundamentals seeming to be structurally sound for the foreseeable future,” analyst Melissa Weathers said Wednesday in a note to clients. “While we expect volatility in memory narratives to persist in this AI environment, we believe MU’s co-specific drivers and robust supply-demand backdrop can support through-cycle earnings power well above historical trends.” Deutsche Bank has a buy rating on Micron. It also has a $1,550 price target on shares, implying nearly 46% upside from Wednesday’s close. Here’s what others on the Street are saying about the memory chipmaker. Morgan Stanley: Overweight, $1,200 price target “Largely as previewed; sequential improvement has decelerated, but the strength in the business continues to shine through; and with duration still underappreciated by some.” Bank of America: Buy, $1,550 price target “As HBM pricing agreements renew and strategic customer agreements (SCAs) expand (now 26 from 16 last qtr), mgmt now sees visibility into QoQ sales/GM expansion every quarter in FY27 from FQ1. The “memory tax” also continues to rise (up to 50%+ of DC Systems TAM or ~35% of AI capex), and we expect memory to increasingly capture more value in 2027 and beyond.” UBS: Buy, $1,625 price target “Ultimately, we think the market will reward this stock with a much higher P/E multiple as it sees a cycle play out in which MU’s gross margins probably don’t go below 65-70%, but in the meantime TBV/share should approach $360 by CYE28 – keeping a solid floor under the stock given much higher RoE across the cycle going forward as memory is critically important in an AI world.” Citi: Buy, $1,300 target “The principal constraint in the industry is on cleanroom space. MU commented that majority of the construction capex increase for F27 is for cleanrooms that will come online in late 2028 and beyond, which shows how long it takes to come online and MU confidence in demand trends. SCA’s are transformational to match supply with demand. Most of construction capex increase is to accelerate cleanroom space. The spend here doesn’t translate into bits, they can provide equipment in these fabs when needed.” JPMorgan: Overweight, $1,540 target “MU delivered a decisive beat-and-raise alongside a material step-up in SCA coverage, an upgraded view on supply-demand tightness, and confirmation of a near-certain capital return pivot – all drivers that we think ultimately dictate the strong multi-year earnings power narrative from here.” Goldman Sachs: Neutral, $1,250 target “We expect the stock to trade modestly higher following a strong quarter and guidance that were well ahead of the Street, partly offset by modest gross margin downside and set against elevated investor expectations heading into the quarter. … Micron has also signed 10 additional long-term agreements, in total amounting to ~35% of expected revenue through FY30 – with ~75% of these containing structured pricing frameworks. We continue to believe these agreements are a positive for the stock which could help increase the multiple on “peak” earnings investors are willing to pay for the stock.”Read More
Micron stock barely budged on chipmaker’s latest earnings. Wall Street still thinks gains will come
Micron reported better-than-expected earnings results and issued strong guidance this week, giving Wall Street analysts reasons to be bullish on the stock.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports