Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
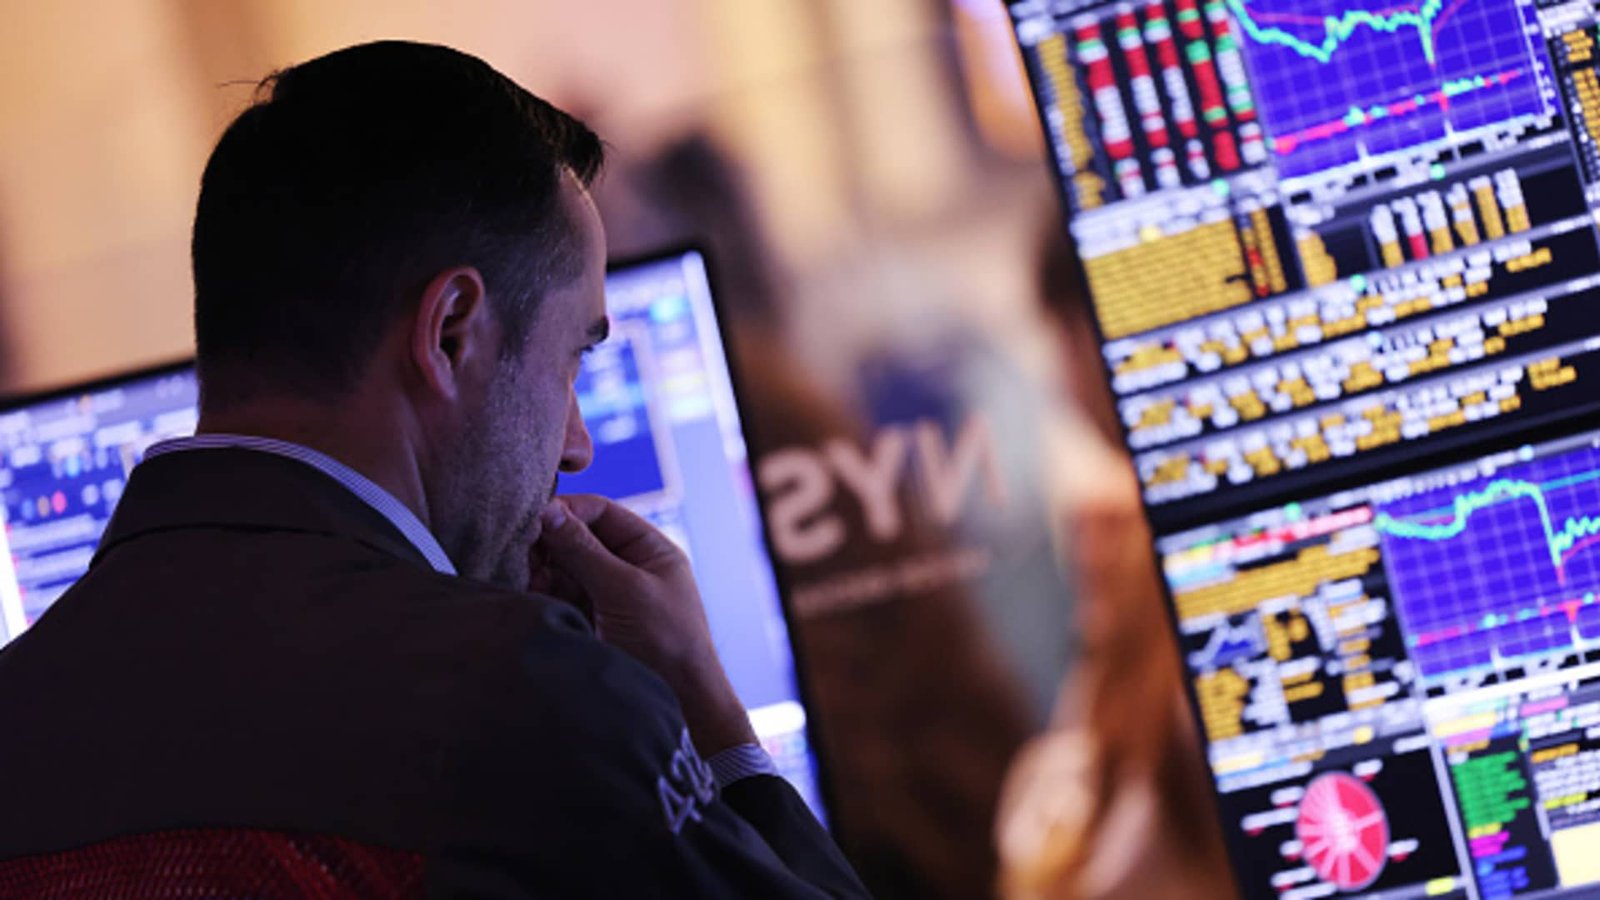
 LivestreamMenuGlobal bond markets are in turmoil, with U.S., U.K., French and German government debt all coming under heavy selling pressure in recent days — and now UBS Investment Bank sees a new pressure point in Europe’s sovereign debt space. Reinout de Bock, head of European rates strategy at UBS Investment Bank, said he has closed a bearish position against French bonds and unveiled a new wager that Italy will be the next country to see its government debt — known as BTPs — come under sustained selling pressure. “This morning, I opened a short BTP Italy versus bunds,” de Bock told CNBC’s “Squawk Box Europe” on Friday. Yields on 10-year Italian BTPs were largely steady at 4.69% by 12:20 p.m. London time (7:20 a.m. ET), after rising to their highest level since 2023 during Thursday’s session. Meanwhile, Germany’s 10-year Bund yield slid more than 10 basis points to 3.414% on Friday morning. That pushed the spread between Italian BTPs and German Bunds — widely viewed as Europe’s safest debt and a key barometer of eurozone borrowing risk — to around 127 basis points. “The safest asset is still the Bund here, and you want to worry about further escalation in parts of the rates market or the financial sector that are vulnerable, that are maybe weaker links,” de Bock said. “I think Italy maybe will catch up, and people will get more concerned about Italy as well at these higher yields, despite a lot of reforms that have been done in Italy.” IT10Y 5D mountain Italian 10-year BTPs. The benchmark U.S. 10-year Treasury hit its highest level since 2002 on Thursday. Across the Atlantic, the U.K. became the first G7 nation to see yields on its longer-dated debt reach 6%, with the 30-year Gilt yield topping levels last seen in 1998. France’s 10-year OAT yield surged to 4.9%, reaching its highest level since July 2002, and posting its biggest quarterly rise in almost forty years. “We live in historic times,” de Bock said, pointing both to price risks across energy and commodities markets, as well as questions over growth resilience. “These two things are now coming together to potentially historic repricing, going back to the levels in yields of the 2000s.”Read More
UBS reveals a new short trade amid bond market turmoil
UBS Investment Bank sees a new pressure point in Europe’s sovereign debt space amid the global bond rout.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports