Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
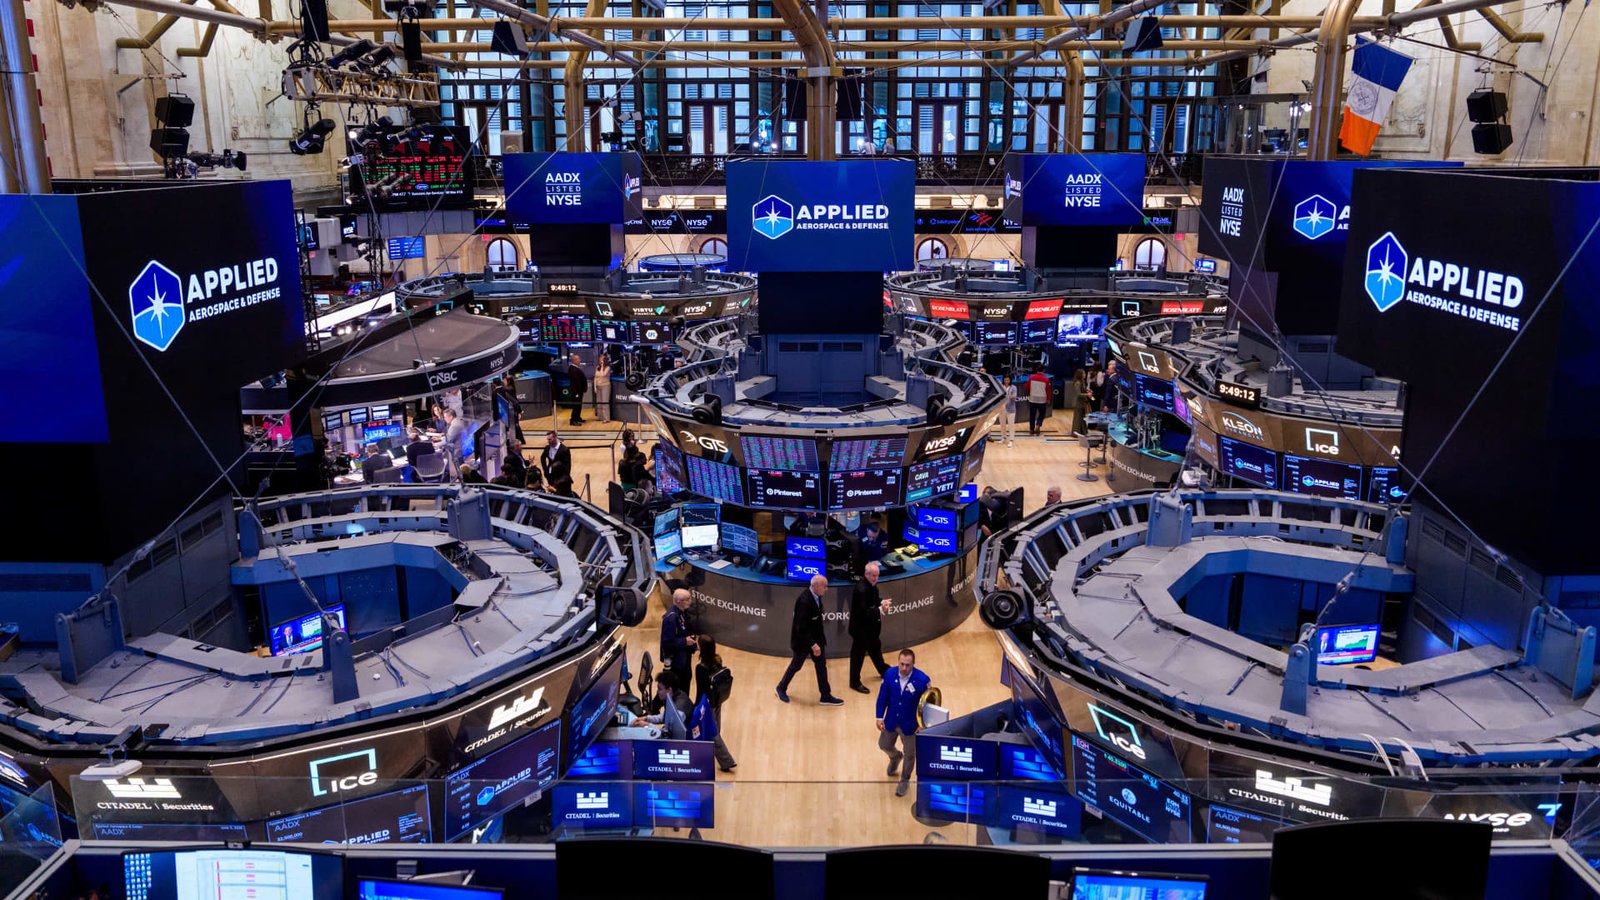
 LivestreamMenuApplied Aerospace & Defense shares are mispriced. The stock fell below its June IPO price after a second-quarter loss, largely due to one-time issues, masking its growth potential. The defense company offers embedded, recurring economics. About 87% of its revenue comes from the sale of products of which it is the sole supplier, and one-third is tied to long-life aftermarket and sustainment programs. Applied Aerospace has strategic positions in next-generation defense and space programs, yet the stock trades below peers such as TransDigm and HEICO. When the value of a newly public company drops by more than a third within months of its trading debut, investors usually scramble for the exits. But this supplier to the defense and space industry deserves a closer look. Applied Aerospace & Defense , which went public on June 3 at $20 a share, has collapsed to as low as $11.39. The catalyst was a headline-grabbing second-quarter loss of $154 million that likely sent trading algorithms to hit the sell button. The reported loss was an accounting entry, driven by $110 million in nonrecurring, noncash IPO-related stock compensation and transaction fees. Strip away these one-time charges, and its underlying business accelerated strongly. Adjusted earnings before interest, taxes, depreciation and amortization was a record $36.4 million, up 38.5% year over year, while revenue grew 47.4%. The standard IPO launch noise may have been confused with operational decay, offering more forward-looking investors an improved entry point into a mission-critical defense company trading at a deep discount. What’s more, its growth runway could widen materially as the Huntsville, Alabama, company deepens its relationships with disruptive defense innovator Anduril Industries and space-launch leader SpaceX . In both cases, these partnerships could translate into years of accelerating demand for the high-value products Applied Aerospace manufactures. The invisible skeleton of modern warfare Applied Aerospace is not a speculative, pre-revenue technology startup selling software promises. It’s a Greenbriar Equity-backed roll-up built around two long-established aerospace manufacturers: Applied Aerospace Structures, founded in 1954, and PCX Aerosystems, whose roots date to 1900. The private equity firm acquired Applied in 2022, merged it with PCX in late 2025, and added Vestigo Aerospace before taking it public. The company operates 11 purpose-built facilities spanning 1.5 million square feet across six states. Its products may be unglamorous, but they are also highly complex and difficult to replace as they make modern flight, rocket delivery and electronic warfare functional. Applied Aerospace feeds into three structurally booming end-markets: Space and launch systems (~23% of revenue): In an era when space access is transitioning from an elite scientific pursuit to a high-cadence commercial business, Applied Aerospace manufactures primary structural parts and components. These include propellant tanks, engine nozzles, nose cones, thermal payload fairings and advanced deployable solar arrays. Defense aviation and airborne systems (~30% of revenue): This segment manufactures composite wings, flight control surfaces, engine shafts, and ruggedized fuselage structures for elite military aircraft, ensuring allied air dominance in an increasingly unstable geopolitical landscape. C5ISR and precision strike platforms (~47% of revenue): Applied Aerospace’s fastest-growing segment supplies the physical hardware behind modern command-and-control, cyber intelligence, surveillance, and reconnaissance networks, the systems that turn battlefield data into action. The company manufactures solid-rocket-motor cases, specialized missile bodies, and radar- and interceptor-protecting radomes. As defense shifts from traditional armor toward connected missile-defense grids and real-time targeting, its components become increasingly central to the weapons and sensing systems that make those networks work. Ability to flex pricing power The crown jewel of Applied Aerospace’s investment thesis lies in its 87% single-source contract mix. In the commercial sector, monopolies are fiercely litigated. In the defense subsystems sector, they represent a coveted competitive fortress. When a primary Pentagon or aerospace contractor designs a multibillion-dollar platform, it qualifies specific suppliers down to the smallest detail. Applied Aerospace’s proprietary and customer-specific manufacturing processes, including Nadcap-accredited chemical processing and heat treating, as well as complex multimaterial bonding, are deeply embedded in these long-lived platforms. That qualification history helps explain its average customer relationship length of 39 years. Because space and defense qualification cycles require multiple years of exhaustive safety and performance certifications, switching to a cheaper competitor is highly frictional for a prime contractor. This creates a level of customer stickiness and pricing power that is difficult to find in the public markets. Furthermore, about a third of Applied Aerospace’s 2025 revenue came from systems used in aftermarket and sustainment programs. This provides long-term revenue visibility, because the underlying platforms have lengthy service lives. Once the company supplies a component for an enduring military or aerospace platform, it can support that program through replacement, repair, overhaul, and service-life-extension cycles for many years — often decades. The result is a recurring and relatively predictable revenue stream that reduces economic cyclicity. Valuable partnerships: SpaceX and Anduril The most impressive aspect of the Applied Aerospace story is its front-row seat to the remaking of the military-industrial complex. For the past three decades, defense procurement was a stagnant oligopoly dominated by a handful of massive legacy prime contractors and painfully slow cost-plus research-and-development cycles. The wars in Ukraine and the Middle East have underscored how quickly drones, autonomous systems, precision strike, electronic warfare and resilient battlefield networks can reshape the combat zone. Venture-backed defense-technology entrants are speeding up the shift to software-defined, autonomous systems and faster production cycles, raising the value of manufacturing partners that can prototype, qualify and scale complex hardware quickly. Applied Aerospace has emerged as a key partner for these disruptors, bridging the gap between digital design intellectual property and mass production. Consider its deep integration with private defense technology juggernaut Anduril Industries. The two have partnered on Anduril’s flagship autonomous aircraft, the Fury collaborative combat aircraft, since the second quarter of 2025, according to a Baird research report dated June 29. While Anduril owns the software brains, it completely lacks the manufacturing capabilities required to produce stealth airframes. Anduril relies on Applied Aerospace to deliver the physical aircraft, supplying everything from the engine fuselage and main landing gear assemblies to the wings and horizontal stabilizers. The U.S. Air Force is moving its collaborative combat aircraft program from prototypes to production, with plans to procure more than 150 aircraft by fiscal year 2031. This puts Applied Aerospace on the ground floor of a potentially massive manufacturing ramp-up. It’s also a vital partner to SpaceX’s Falcon 9 platform. Beyond supplying payload deployment structures — the hardware that helps a satellite, sensor, solar array or other payload survive launch and then deploy correctly in space — Applied Aerospace manufactures the landing gear components. The primary structural hinges are reused, but the aluminum honeycomb crush pods located at the connection joints of the landing legs must be replaced with each launch. The highly specialized crush pods are designed to absorb the touchdown impact. As the pace of SpaceX launches accelerate, manufacturing these parts becomes a high-volume revenue funnel for Applied Aerospace. The company hasn’t disclosed the percentage of its sales from SpaceX, and it also supports the reusable landing gear for Blue Origin’s New Glenn rocket. At a cash flow inflection A traditional bear argument against high-growth advanced manufacturing plays is the capital spending burn. There is a fear that a company will be forced to dilute shareholders or choke itself with expensive debt to build factories to fulfill orders. Applied Aerospace has 40% structural excess capacity, giving it a competitive advantage. Simply by scaling from single-shift operations to standard multishift routing, Applied Aerospace can boost its throughput to clear its rapidly growing $1.13 billion contracted backlog without brick-and-mortar expansion. The financial runway cleared by its June IPO is transformative. Pre-IPO, Applied Aerospace was heavily weighed down by legacy debt of $643 million, a byproduct of Greenbriar’s buy-and-build strategy. The interest expense offset GAAP profitability, masking strong adjusted EBITDA margins of 23.6%. Post-IPO, Applied Aerospace’s leverage is down to 2.5x adjusted EBITDA. As interest expenses decline in the second half of 2026 and 2027, earnings are likely to accelerate. A risk: Unbilled receivables No investment thesis is complete without a look at structural risk, and for Applied Aerospace one is buried within its working capital accounts. Investors should monitor the company’s unbilled receivables, which recently spiked from 28% to 34% of trailing 12-month sales. Because the company builds multiyear aerospace systems, accounting regulations require them to recognize work-in-progress revenue, often before they reach the contract milestones that allow their billing. The timing differential translates into a lag in cash collection. The working capital buildup is the main reason near-term operating cash flow has been temporarily constrained. To prove the absolute health of its free cash flow conversion engine, this metric needs to return to the mid-20% peer average over the next few quarters. A TransDigm in the making Applied Aerospace’s current valuation is unlikely to persist. As of Thursday’s close, at $11.69 per share, the company has a market cap of more than $2.07 billion and trades at an enterprise valuation of ~16x estimated consensus 2026 EBITDA of $152 million. Elite aerospace subsystems comparables such as TransDigm and HEICO trade at similar or higher multiples despite materially slower growth. The differential appears too steep: Applied Aerospace’s sole-source revenue mix is about 87%, which is close to TransDigm’s roughly 90% rate, yet Applied Aerospace is growing faster. Its second-quarter revenue rose 47% including acquisitions and 19.8% organically, compared with TransDigm’s fiscal third-quarter growth of 23% as reported and 13% organically. A 12-month return to its IPO price of $20 per share is a highly conservative target, applying a standard re-rating multiple of 15x estimated 2027 EBITDA once clean GAAP earnings surface. Most Wall Street analysts recommend purchase with an average price target of $25.75, or more than double its current price, according to LSEG. The Street-high target $30 suggests a 150% return versus Thursday’s close. As Applied Aerospace strips out IPO charges over the next two quarters, demonstrates its capital-light operating leverage, and starts collecting cash on its backlog, the valuation gap will likely compress. Applied Aerospace isn’t a broken business. It’s a broken IPO, offering a high-quality runway for long-term returns. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET. THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL’S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR. Click here for the full disclaimer.Read More
This SpaceX supplier has a front-row seat to major shifts in warfare and rocket use
Although this recent IPO is trading below its offer price, its supplier relationships with both SpaceX and Anduril bode well for future revenue growth.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports