

Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
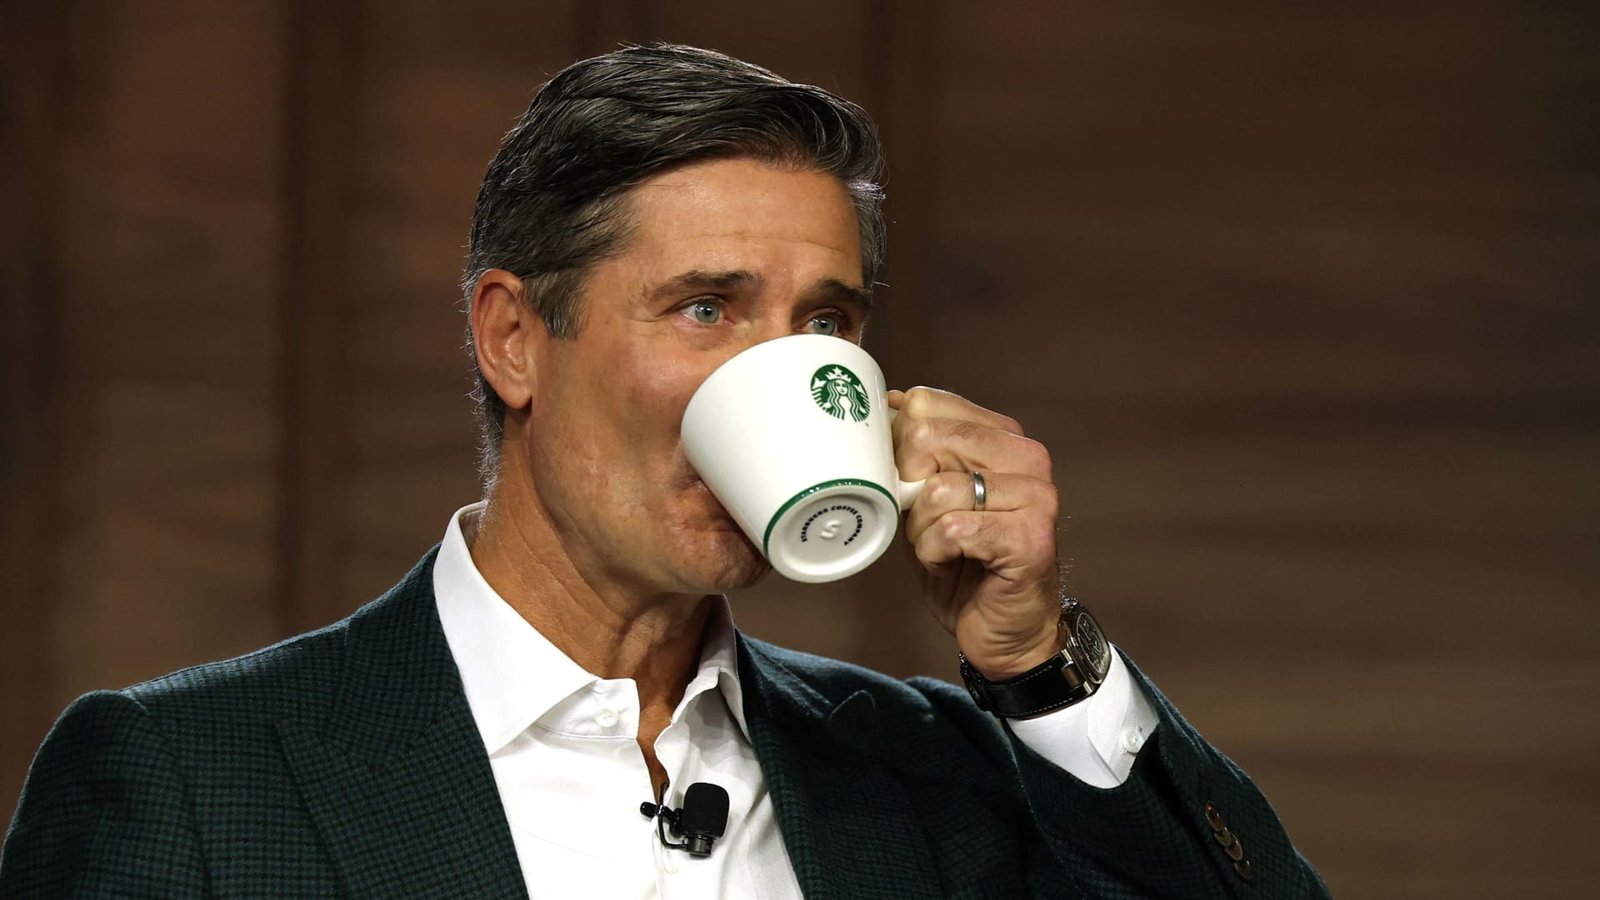
 LivestreamMenuStarbucks on Thursday reported better-than-expected quarterly profits to wrap up its fiscal 2026 and issued healthy guidance for its new year. The results and outlook may not convince any skeptics to change their tune, especially as elevated gas prices remain a threat to consumer spending. However, we see plenty of encouraging reasons to stay invested and bet on CEO Brian Niccol. Revenue in its fiscal 2026 fourth quarter was $9.14 billion, slightly missing the LSEG consensus of $9.23 billion. Quarterly revenue declined 4.5% year over year, primarily due to its China business moving to a joint-venture model from company-operated stores. Adjusted earnings per share (EPS) in the July-to-September period increased 54% on an annual basis to 80 cents, topping the 72-cent consensus, LSEG data showed. Global comparable store sales, a key performance metric in the restaurant industry, were up 7.2% in the quarter. That exceeded the FactSet consensus of 6%. North America comparable store sales increased 7.9% in the quarter, beating expectations of 7% growth. SBUX YTD mountain Starbucks YTD Shares of Starbucks were down about 2% in extended trading Thursday. That could reflect some profit-taking following a strong comeback for the stock in recent weeks. Like many restaurant stocks, Starbucks suffered a bruising decline beginning in late August and into October, driven primarily by concerns that resurgent gas prices in the U.S. may put a crimp on consumer spending. The stock lost more than 16% between Aug. 26 and Oct. 9. However, it has since erased most of those losses and, as of Thursday’s close, sat less than 3% from its highest close of the year on Aug. 11. We’re reiterating our hold-equivalent 2 rating and keeping our price target of $120 a share. Bottom line Starbucks is on solid ground as Niccol enters his third full fiscal year leading the coffee chain. Investors are no longer satisfied with reinvigorated top-line growth. They want to see continued sales momentum translate into stronger profits. We think Niccol is doing just that, reflected in Starbucks’ fiscal fourth-quarter adjusted EPS exceeding consensus and its initial fiscal 2027 guidance at least meeting expectations on adjusted operating margin and profits. Bears may still be concerned about valuation, with shares trading at 33 times forward earnings. That’s a tough debate to settle at the moment. For the stock to work, Starbucks will need to execute and deliver upside in the coming quarters — making the stock look cheaper in the rearview mirror than it appeared. With Niccol steering the ship, that’s a bet we’re willing to make. And it’s no longer about his track record at Chipotle . At Starbucks, he’s delivered three earnings beats in a row, following an uneven start to his tenure, which began in the fall of 2024. All the changes that Niccol had to make — adding staffing to cafes, streamlining the menu, closing underperforming locations and starting renovations of surviving locations to make them more inviting places to be — are bearing fruit. “Back to Starbucks, as a strategy, has switched gears from a turnaround plan to a growth plan,” Niccol said on Thursday’s earnings call. The company has delivered five straight quarters of positive global comparable store sales growth, or comps. In North America, comps exceeded Wall Street expectations for the sixth earnings report in a row. Looking ahead, Starbucks said it expects North America comps to grow 4% in fiscal 2027 — slightly below the 4.2% consensus on FactSet. For comparison, full-year comps in fiscal 2026 rose 6.6%. Some deceleration is very much expected. And considering Niccol has a long-term target of at least 3% comps growth, it’s notable that the fiscal 2027 guide came in above that. Asked about the comps outlook, Niccol said, “We just see strength in the business that gave us the confidence to commit to 4% comps.” He added, “The way I look at it is, we’re probably a year ahead of schedule relative to the guidance that we gave for fiscal ’28” at our January investor day . The CEO pointed to the way that improved customer service has resonated, along with a redesigned digital rewards program that has grown to 36 million active users over the past 90 days, up from 35.8 million in July. Starbucks is working to add more personalization to the rewards program to fuel its next leg, Niccol said. Niccol also said the strength of the business stems from compelling marketing behind menu innovations such as protein cold foam, its iced Refreshers, and food upgrades. He mentioned there’s more to come on the food front, particularly to drive transactions in the afternoon, and teased new tea drinks that lean into health and wellness. “The business is on really strong footing, and it is driven by operational health,” Niccol said. He added, “Starbucks brand affinity is at near record levels as our menu innovation, marketing and merchandise continue to create moments that drive culture and bring people into our coffee houses.” The marketing engine is revving up in the coming months with special holiday cups — most notably the return of last year’s viral sensation: the Bearista glass cold cup. A few more thoughts on fiscal 2027: Starbucks is planning to increase the number of cafe uplifts to about 2,000 in North America, up from more than 1,700 in fiscal 2026. Niccol also said it will be year of major tech modernization, including new point-of-sale and staffing systems. Guidance Here is the full look at Starbucks’ initial guidance for fiscal 2027 (which includes 53 weeks instead of its usual 52 weeks): Consolidated net revenue down 1%, including a $700 million from the extra week. The decline is primarily driven by the fact China was still company-operated for the first half of fiscal 2026. North America comparable store sales growth of roughly 4%, a touch below the 4.2% consensus on FactSet. Adjusted operating margin in the range of 13.5% to 14%, which even on the low end exceeds the 13.3% expectation. Adjusted EPS in the range of $3.15 to $3.25, including slightly more than 10 cents from the 53rd week. The midpoint of $3.20 edged out the FactSet consensus of $3.16 and represents almost 18% year-over-year growth. (Jim Cramer’s Charitable Trust is long SBUX. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
Starbucks serves up a solid quarter and full-year outlook. Why we’re staying invested
The coffee chain is showing improved profitability, chipping away at part of the bear case.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News


Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports


