Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
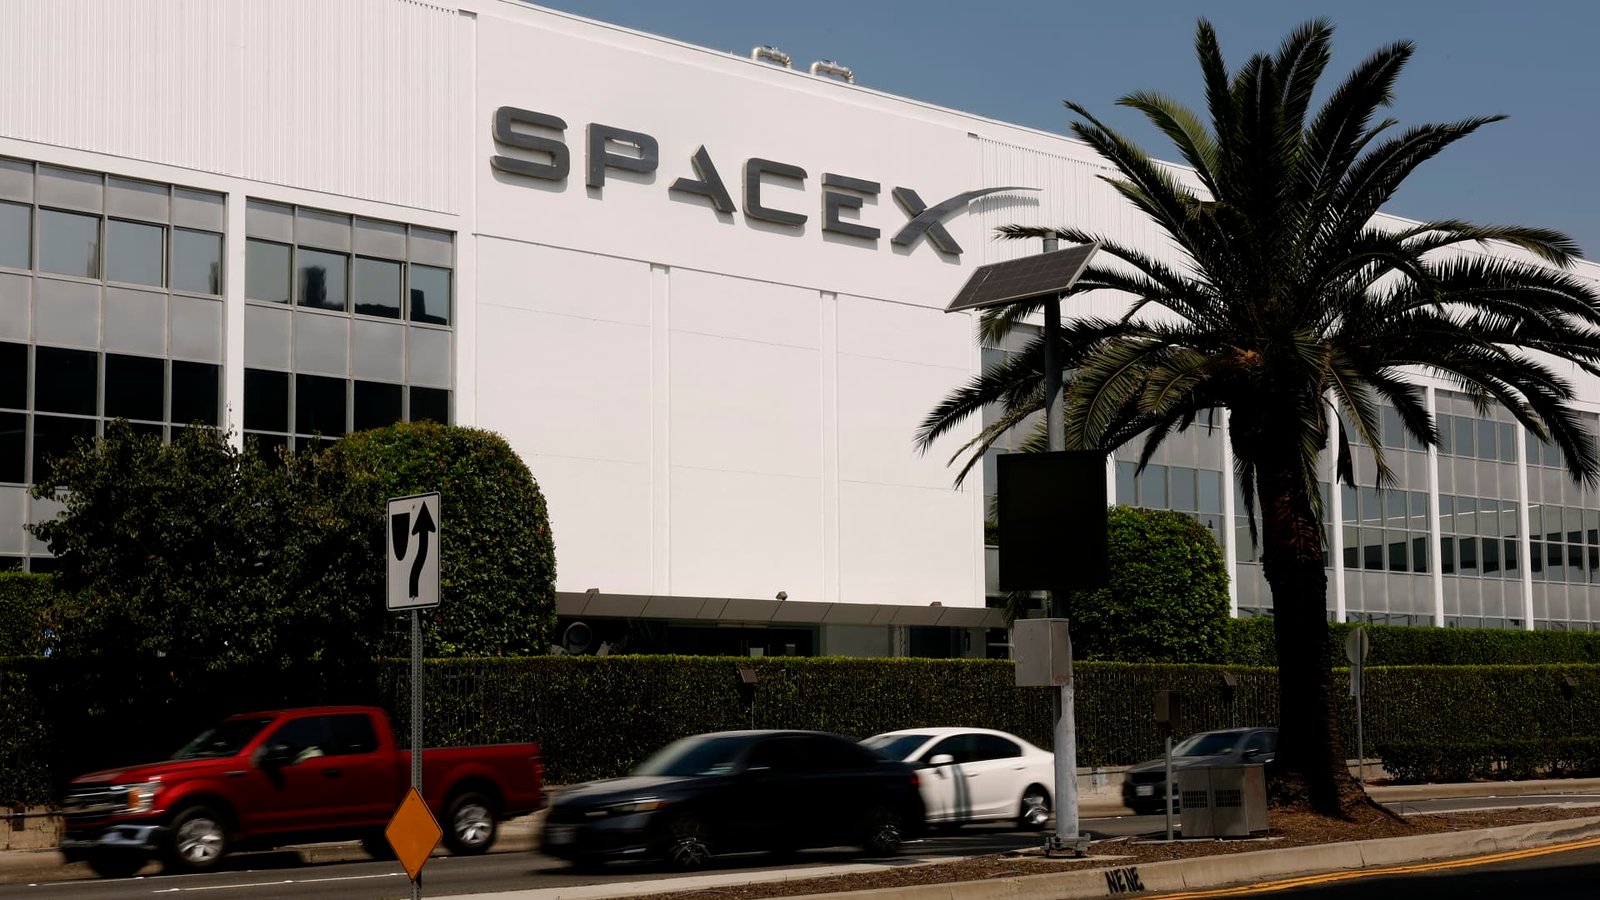
 LivestreamMenuStronger-than-expected revenue from SpaceX’s AI business is making PhillipCapital — once a bear on the company — bullish about the Elon Musk giant’s stock. The firm upgraded shares of the space and AI company to buy from sell, and hiked its price target to $250 from $75. That level implies an almost 73% gain from Thursday’s close. SpaceX reported on Tuesday adjusted earnings of 45 cents per share and revenue of $14.58 billion for the third quarter, both exceeding expectations. The company delivered its first profit as a publicly-traded stock, which analyst Glenn Thum wrote in a Friday note, was driven by three catalysts. “1) SI, as new cloud services agreements came online at higher rental prices and Cursor added US$608mn from mid-August,” Thum said in the note, referring to the company’s AI business as its branded “super intelligence” name. “2) Connectivity, as aviation installs and Starshield contracts lifted enterprise and government revenue 91% YoY; and 3) operating leverage, as higher-margin cloud services turned SI profitable.” Thum said, though, he still sees full-year 2027 revenue as lower than that of what SpaceX might expect, based on annualization off its guidance for the first quarter of next year. He said that’s because he expects delays in scaling SpaceX’s compute business, with cooling and power key constraints to doing so. But as Thum raises his forecasts, it’s that very business that is giving him more confidence in the company. “We like SPCX for compute demand running ahead of supply,” he wrote. “Contracts are renewing at higher prices per watt, new capacity pays back in under a year, and guidance implies 1Q27 revenue more than double 3Q26.” Shares were higher by 2% in premarket trading Friday. SPCX 5D mountain SpaceX 5-day.Read More
SpaceX bear flips to big bull because of AI business. Analyst now sees 70% gain
PhillipCapital moved its rating on the Elon Musk giant to buy from sell, with the bullishness stemming from the company’s AI business.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports