Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
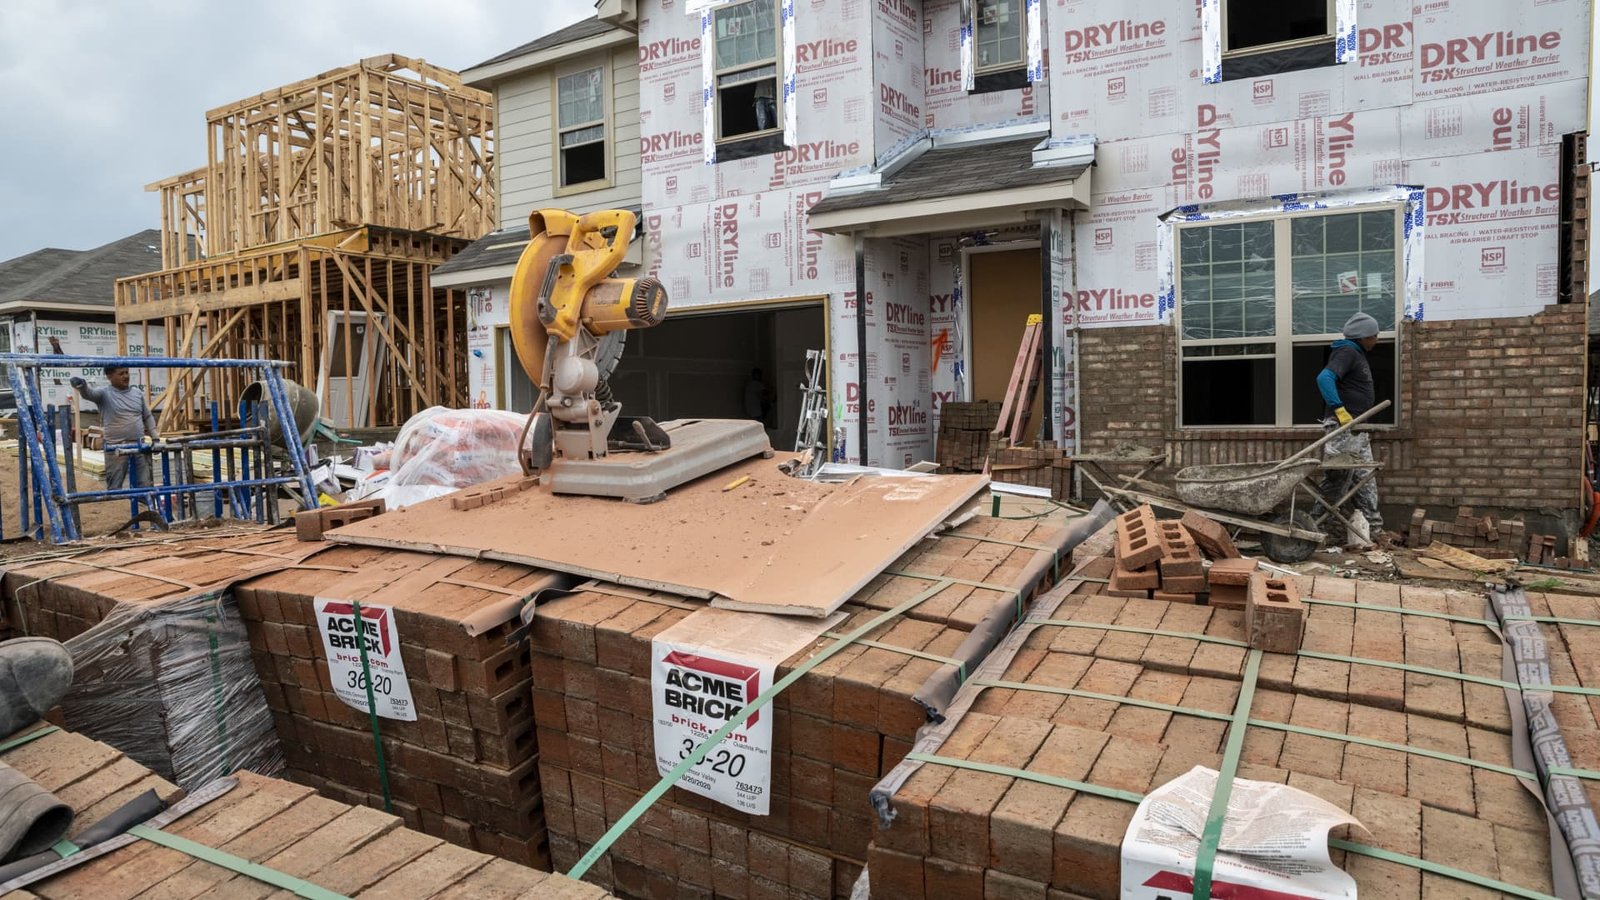
 LivestreamMenuRayonier trades at a steep discount to its net asset value, hurt by rising rates and worries about housing affordability. U.S. housing supply remains constrained, while lower Canadian lumber supply and Rayonier’s land-based businesses could support future earnings. Housing affordability, mortgage rates, lumber-cycle weakness and dividend risk could keep pressure on the shares. Timberland offers a cheaper way to hedge inflation, with one ounce of gold going for nearly 2.5 acres of Rayonier timberland at current prices. If someone told you that you could buy land for a 40% discount, would you buy it? Right now, Rayonier , one of only two publicly traded timberland real estate investment trusts listed on U.S. markets, is trading at a price that values its land assets at less than its fair market value. The stock, down about 14% year to date, has felt pressure from rising U.S. Treasury yields. The pressure is twofold. Rising rates have pushed 30-year mortgage rates above 7%, hurting Rayonier’s largest demand segment: residential construction. There’s also been less demand for REITs as income-seeking investors opt for the perceived safety in higher bond yields. This near-term weakness has created a remarkable buying opportunity: Rayonier is trading at about 40% below its net asset value. This is an opportunity seen only twice in recent history, during the Covid-19 lows and the global financial crisis. Long-term market forces could provide tailwinds to Rayonier. U.S. housing remains significantly underbuilt, with an about 4 million unit shortfall. The median housing age continues to reach new highs every year, which should drive home repair demand in the future. The company also is exploring other avenues for EBITDA growth, with its carbon capture and solar land lease businesses expected to more than double between 2027 and 2030, along with a growing rural land sales business. Investors also could benefit as management looks committed to narrowing the stock’s discount through share buybacks. Finally, for defensive investors, Rayonier offers a cheap inflation-hedge angle and a chunky dividend. A U.S. timberland REIT Rayonier’s history dates back a century to the founding of the Rainier Pulp and Paper Company in Shelton, Washington. In 1931, it partnered with DuPont to produce cellulose and create rayon, a cotton and silk substitute. The product, named Rayonier, fueled growth in the textile industry and lent the company its name as it went public in the late 1930s. To feed its mills, Rayonier began purchasing its own U.S. timberland. The company has morphed a number of times throughout its history — including big shifts over the past year and a half. In June 2025, it shed its New Zealand timberland and on Jan. 30 Rayonier merged with PotlatchDeltic , consolidating the industry further and leaving Rayonier as the only publicly traded timber REIT focused solely on U.S. assets. The company owns 4.1 million acres of U.S. timberland, with 77% in the Southeast. Post-merger, it operates four segments: Southern timber, Northwest timber, wood products and real estate. Housing demand The first tenet of Rayonier’s long-term growth case hinges on the U.S. housing market. In April, the St. Louis Federal Reserve said estimates suggest the U.S. is short between 3 million and 5 million housing units. Existing homes are also growing older, with the median age reaching around 43 years, a record high, according to Raymond James estimates. Nearly 60% of all standing homes were built before 1990, Raymond James said. Closing the gap will create demand for timber products. The obstacle is affordability. In September, housing starts fell to 1.22 million, down 5.2% month over month and 7.4% year over year. Raymond James said there is ample evidence of significant pent-up demand waiting to be unlocked if affordability improves. Lumber supply outlook Falling lumber imports and small mill curtailments are providing a floor to U.S. lumber pricing and also supporting Rayonier’s growth. North American softwood lumber production has steadily declined from its 2021 peak of about 62 billion board feet to around 55 billion board feet in 2025, as high-cost mills have been forced to shutter production. Canadian mills have felt the most pain. International lumber imports have fallen 17% year to date, according to Raymond James, with U.S. production picking up the imbalance. Just weeks into his second term, President Donald Trump signed an executive order to investigate imports of timber, lumber, and derivative wood products. This led to a 10% tariff on imported softwood lumber . This duty was layered on top of existing levies on Canadian lumber, and challenges have only managed to reduce the current tariff to around 35%. Canadian imports have fallen about 9% through July from the same period a year ago, according to Raymond James, and are down about a third from the 2021 peak. Canadian sawmill production fell 8.6% month over month and 6.7% year over year in July. This should benefit Rayonier, specifically its Northwest segment. At a minimum, the trend supports lumber pricing. Land value upside The final growth vector is its land optionality. The real estate segment houses its higher-and-better-use land business, where it can sell land at significantly higher prices than it receives for timberland. In the second quarter, the company said it sold 7,500 acres for $53.7 million. During the three-month period, these land sales fetched $5,439 per acre, more than double the latest National Council of Real Estate Investment Fiduciaries timberland index’s implied price per acre of $2,250 in 2025. The land sales can provide a floor to EBITDA in the event of a fallow timber period. Developed land sales are expected to continue increasing, with its finished Chenal Valley project, a 4,800-lot master-planned development in Arkansas, selling finished lots. Its Wildlight and Heartwood communities in Florida and Georgia are still in development. At Wildlight, Rayonier is targeting about 400 closings per year, up from its 123 average annual home closings in the last five years. Heartwood is targeting 300 closings per year, up from 54 average annual home closings in the same period. Hidden within its timberland segment is a growing business placing solar leases and carbon capture leases on its land. Management estimates by 2030 EBITDA from land-based solutions will reach $75 million, up from an estimated $30 million in 2027. The leases take time, as a solar or carbon lease developer typically has a 3- to 5-year option period, leasing the land with no impact to timber operations. Once the lease fully converts, Rayonier could receive 5 times to 10 times its timberland EBITDA on the same land, with recent transactions priced at $10,000 to $20,000 per acre. Plus, the long-term lease business could shield it from cyclical exposure in lumber. There’s even an AI angle. On its second-quarter call, management said it’s fielding interest from data center developers. While warning it could take time to materialize, it has enlisted outside experts to identify data center opportunities, and hinted at a $25,000-$30,000 per acre price point. Feeling defensive? An underappreciated aspect of Rayonier is its inflation protection. Timberland is a real, productive asset with the added benefit of cash-flow upside not found in other inflation-protection assets like gold, silver, or, depending on who you ask, bitcoin. Timberland offers inflation protection through its biological growth, its harvest flexibility, and its commodity-based pricing that’s historically scaled with inflation. Trees’ biological growth isn’t beholden to any market, as physical volume expansion builds in value over time. Timberland owners have the flexibility to harvest when prices are perceived to be stronger. In Rayonier’s case, this could lead to more harvesting from a stronger Northwest timber segment rather than its U.S. South segment, giving that region’s prices time to recover. Notably, the disconnect between gold and timberland acreage has reached a fever pitch. With an ounce of gold trading around $4,000 on Friday, that’s the equivalent of nearly 2.3 acres of Rayonier timberland at its current valuation, while offering a similar protection profile — a historic dislocation. Lastly, with its price around $18.65, Rayonier sports a dividend yield of 5.6% and provides stable income for defensive, income-seeking investors. Cash available for distribution has covered its dividend in four of the last five years. Analysts expect profits and assets to cover the dividend through weaker timber periods. Risks The risks to Rayonier are plain to see: housing sentiment and 2027 housing forecasts are in the doldrums, with worries about affordability, higher mortgage rates, and elevated new housing stock. In addition, Rayonier’s competitor Weyerhaeuser cut its third-quarter wood products EBITDA estimate on Sept. 24 by about $20 million to $25 million due to higher diesel costs. Rayonier sold off on the news. While Rayonier has been silent about its outlook, analysts slashed EBITDA estimates. Should its forecast disappoint, the stock could fall further. Any cut to the dividend also could lead to near-term stock weakness. However, with the company’s depressed valuation, these potential issues may already be priced into the stock. Rayonier valuation discount Rayonier is a cyclical stock beholden to both the housing and lumber cycle. Cyclical stocks tend to look expensive as earnings fall at the bottom of a cycle and deceptively cheap at the top. The company currently sports a P/E above 40, which screens as expensive. However, investors should value Rayonier on a sum-of-the-parts basis, with a necessary discount to the company’s net asset value. Per Raymond James’ Oct. 7 report, Rayonier trades at a 40% discount to its NAV of $31.39, or about 1.8 standard deviations outside the norm. The firm’s estimate assigns a blended portfolio average of $2,577 per timberland acre, or $9.2 billion; $1.4 billion to its real estate portfolio; and only $338 million to its wood products segment. They estimate that if Rayonier returns to its historical discount to NAV of 12%, the stock would rise more than 50%. During recent investor meetings, management has said it believes the market has valued its timberland at about $1,400 per acre, hinting at an even greater discount. Management has said it could close the gap to NAV through share repurchases. Through the second quarter, it bought back 4.9 million shares for about $103 million, leaving it with an authorization of about $126 million. In a recent Truist note, company management is said to be willing to consider incremental land sales to fund buybacks, which could support the stock price. In summary, Rayonier is a scarce, U.S.-focused asset with long-term tailwinds from underbuilt U.S. housing and falling Canadian lumber supply, coupled with a tangible real-asset inflation-protection angle and a management team focused on correcting its historically wide discount to NAV. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET. THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL’S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR. Click here for the full disclaimer.Read More
Buying America at a discount: This timberland REIT is on sale
This timberland REIT is trading far below the value of its land assets even as it has stands to benefit from several different growth oppportunities.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports