Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
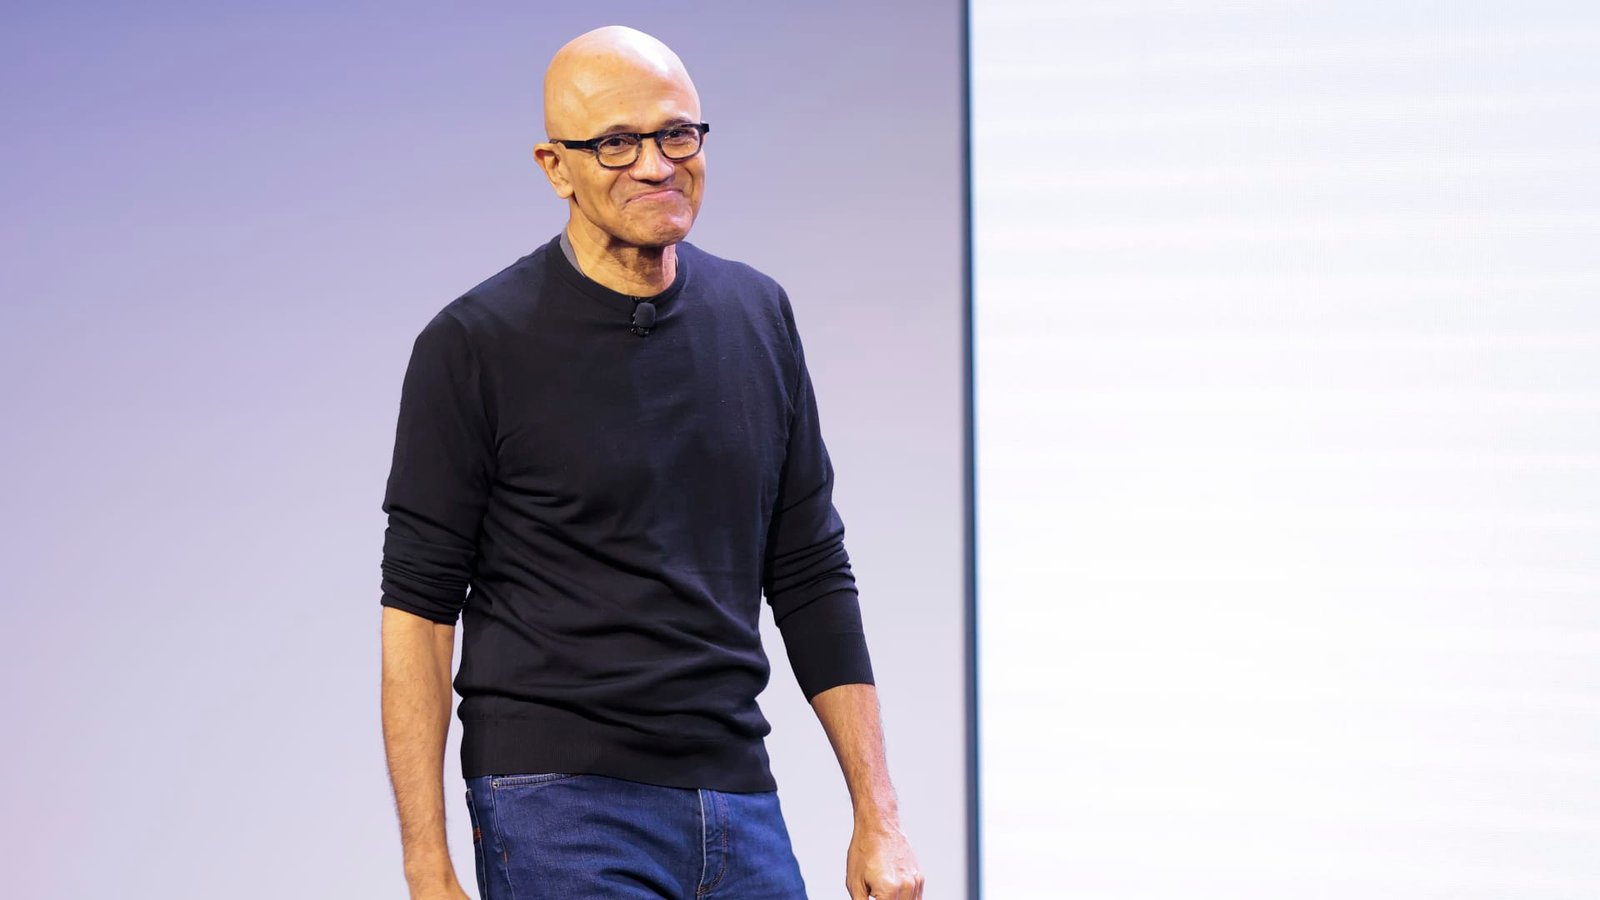
 LivestreamMenuShares of Microsoft edged higher Wednesday evening after the tech giant reported better-than-expected results across all key metrics and signaled that growth in its all-important Azure cloud computing business continues to accelerate. Revenue in the three months ended in September rose about 19% year over year to $92.28 billion, beating the LSEG consensus estimate of $90.69 billion. Adjusted earnings per share (EPS) totaled $4.92, up 32% from a year earlier, beating the $4.73 consensus, according to LSEG. Azure cloud revenue grew 48% year over year on a reported and constant-currency basis, beating FactSet consensus estimates of about 44% and 45%, respectively. MSFT 1Y mountain Microsoft 1-year stock performance Bottom line Earlier this year, Microsoft shares were down about 25%, trading in the mid-$300s on concerns that it had fallen behind in the AI race, that its seat-based subscription model was vulnerable to disruption, and that the company lacked innovation in its AI tools. But that all changed in July: Azure revenue growth accelerated; momentum in Copilot paid seats grew; and, perhaps most importantly, the company separated itself from the other major hyperscalers by spending within its means and not burning through all its cash flow to support its AI efforts. The stock gained roughly 51% from its summer low in late June through Wednesday’s close. That rebound is likely to continue after another clean earnings report. Microsoft shares are up another 3% in after-hours trading, putting the stock in record-high territory. We’ll see how it trades Thursday in what may be a tough day for tech following misses from Alphabet, ServiceNow , and Fortinet , but any dip will have nothing to do with its excellent quarter. To start, Azure revenue growth accelerated to 48% year over year, exceeding analyst expectations and management’s guidance of about 45%. More precisely, Azure revenue totaled $33.17 billion in the quarter, up from $22.38 billion last year. Microsoft’s disclosure of quarterly Azure cloud revenue is new, following changes to its reporting structure announced in September. Why we own it Microsoft is a core backbone of global productivity thanks to its Office 365 suite and hybrid cloud platform Azure. The company is also proving itself to be a key provider of AI tools, in part due to its large investment in OpenAI, the startup behind ChatGPT. We also like what it’s doing in the video gaming industry as it looks to grow recurring revenue streams. Competitors : Amazon , Alphabet and Salesforce Weight in portfolio : 2.9% Most recent buy : Aug. 5, 2024 Initiated : Dec. 4, 2017 Past Microsoft quarters were held back by capacity constraints, leaving Azure revenue on the table. Similarly, Azure revenues were limited by the company allocating capacity to other opportunities, such as Copilot and internal R & D. But there has been a major emphasis on bringing capacity online faster to meet accelerating demand. Microsoft added 24 new data centers across five continents in the quarter. Notably, Azure revenue exceeded expectations despite Microsoft experiencing third-party capacity delays. These third-party delays are something we must monitor in the weeks and months ahead, as they could lead to more push-outs in AI spending. Still, Microsoft generated more revenue than expected due to gains in GPU efficiency, which allowed it to allocate additional capacity to customers while increasing revenue per token. This is a particularly notable development because it suggests each dollar of capital spending can support greater revenue generation and potentially higher returns on investment. We’ve been skeptics on Copilot, but it’s clear this AI tool is gaining traction in the enterprise. Microsoft calls Copilot “the new OS [operating system] for work.” On the earnings call, CEO Satya Nadella said that Copilot’s daily users increased by 50% year over year, while user satisfaction improved by nearly 20% quarter over quarter to an all-time high. We didn’t hear anything new regarding paid seats, but the company sounded upbeat about its adoption. Finally, we appreciate Microsoft’s unwillingness to wreck its balance sheet and burn through all its cash flow. Capital expenditures (including finance leases) were $45.2 billion, up modestly from $41 billion in the prior quarter and $34.9 billion in the prior year. But Microsoft’s spending was much lower than the $51 billion analysts had forecasted and the $50 billion projected by management. Although some of the differences between actual spending and management’s guidance were due to those delays in third-party capacity deliveries — meaning some of that spending will be pushed into future quarters — free cash flow remains firmly in positive territory. This financial discipline allows the company to continue investing aggressively in AI while also returning capital to shareholders, including $2.9 billion in share repurchases during the quarter. That amount may seem trivial, but it’s noteworthy in a year when Alphabet and Meta issued equity to fund their AI investments, diluting existing shareholders. Microsoft’s positive free cash flow suggests the business doesn’t have any immediate cash needs. However, CFO Amy Hood acknowledged that the company “will access additional sources of funding when we believe it is attractive to do so.” We do not want Microsoft to follow Meta and Alphabet’s lead with equity offerings, so this is something to be mindful of in the future. Looking ahead, the company’s revenue outlook for the current quarter was slightly better than expected, driven by continued upside in Azure despite third-party capacity constraints. Azure revenue is expected to grow about 49%-50% in constant currency, above analyst forecasts of about 46% growth, according to FactSet. It all adds up to a great quarter, solid guidance, and continued financial discipline that could make this stock one of the more attractive hyperscalers in the market. We are increasing our price target to $580 from $550 and maintaining our 2 rating. Guidance Microsoft’s quarterly outlook offered slight upside. The company guided revenue from its Agents and Infra segment to $80.1 billion to $80.7 billion, which is above the FactSet consensus of $79.6 billion. In Devices and Consumer, revenue is expected to be $15.9 billion to $16.4 billion, which is roughly in line with the consensus estimate of $16.29 billion, according to FactSet. This means Microsoft forecasts total company revenue of $96 billion to $97.1 billion, above the Street’s $95.6 billion. In terms of capex, Microsoft plans to spend over $50 billion in the second quarter and $170 billion over the calendar year. The full-year figure is slightly lower than the $175 billion previously expected, with the difference attributable to capacity delays at third parties — something to keep an eye on for the semiconductor and power infrastructure food chain. (Jim Cramer’s Charitable Trust is long MSFT. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
Microsoft’s strong quarter backs up its stock rebound. Here’s our new price target
Microsoft shares are up nearly 3% in after-hours trading, putting the stock in record-high territory.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News

Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports