Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
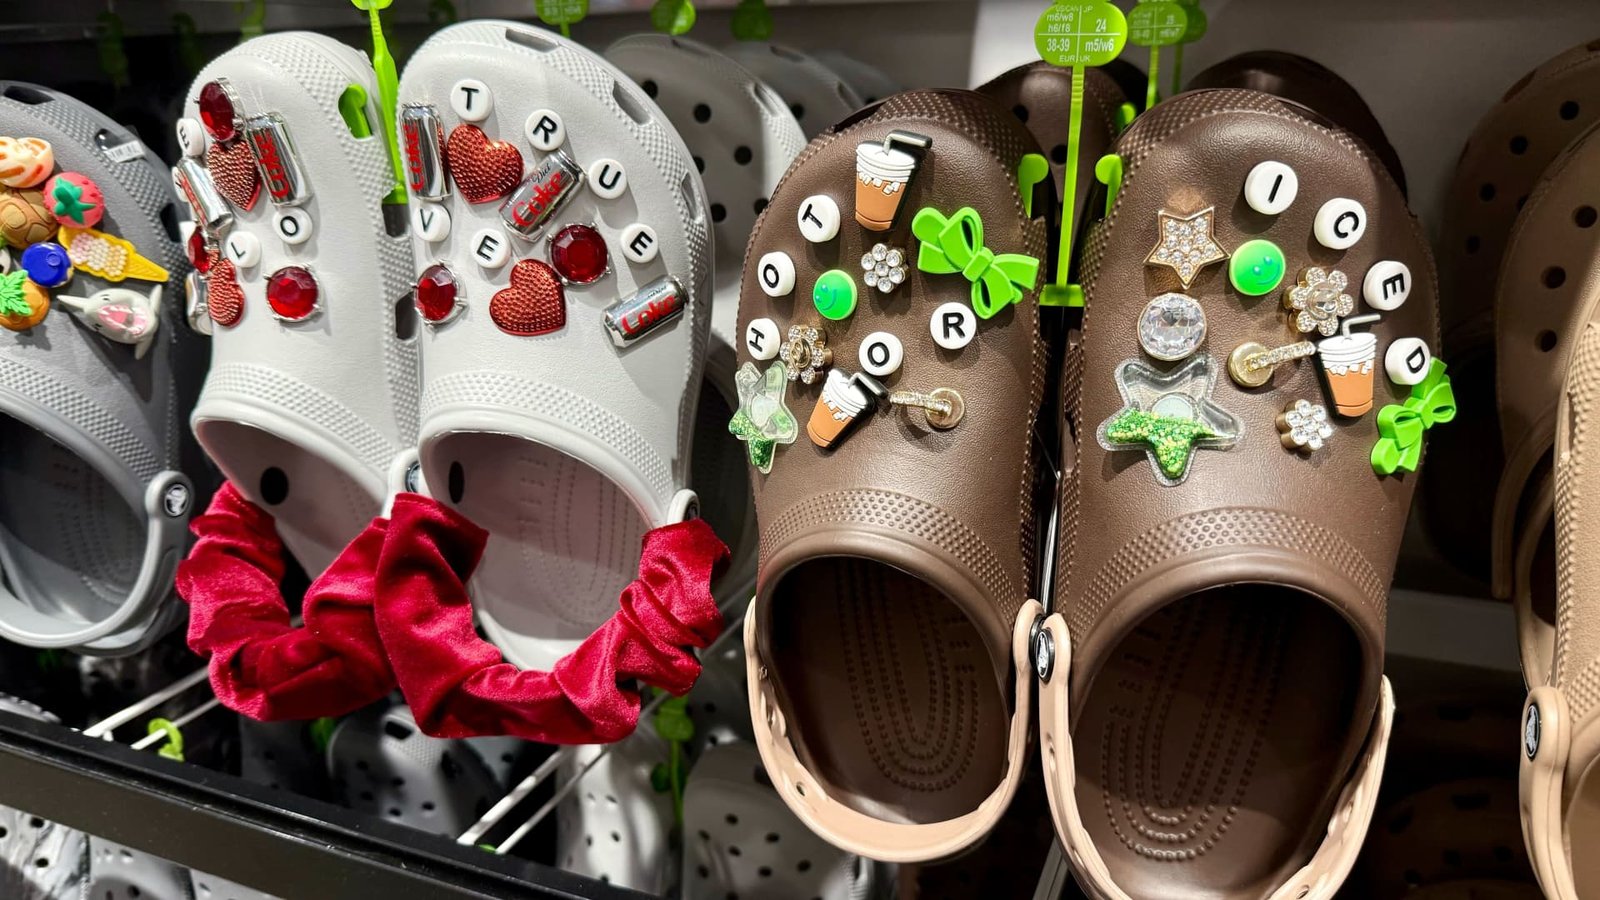
 LivestreamMenuCrocs is beginning to deliver results for investors, aided by its international expansion, product diversification, HeyDude turnaround and its unique social media marketing strategy. Since CNBC flagged the stock’s depressed valuation on Oct. 13, shares have surged 30%, including a massive 25.5% post-earnings rally on Thursday after HeyDude returned to growth and management hiked 2026 estimates on both the top and bottom lines. Third-quarter earnings increased 26.4% to $3.69 per share after adjustments on revenue of $1.04 billion, which was up 4.6% from a year ago. Analyst consensus was $3.31 a share, according to FactSet. The company now expects full-year revenue to rise 3% from 2025, up from previous guidance of a 1% to 2% gain. The forecast for adjusted EPS is $14.45 to $14.65, up from its previous range of $13.70 to $14.00. Why is Crocs succeeding while larger competitors like Nike struggle? The divergence stems from a combination of targeted operational and strategic execution. HeyDude returns to growth After several years of negative growth, the HeyDude brand looks to have turned the corner with 6.1% revenue growth year-on-year in the third quarter. The inflection to positive growth came earlier than expected, according to Bank of America analyst Kendall Toscano. She wrote that the beat was propelled by the wholesale channel which “increased 14%, driven by stronger-than-expected at-once and replenishment orders, with sell-in and sell-out improving meaningfully as product diversification drove better productivity.” Crocs international growth Crocs brand international revenue grew by 11.8% year-on-year compared with Street estimates of 6.6%. “China, India, and Japan performed well, supported by product innovation and digital engagement, CROX continues to view this market as underpenetrated,” wrote Raymond James analyst Rick Patel. He said the international division is “the primary growth engine” of the company. Some of that success can be attributed to Crocs’ long-time focus on social selling and digital advertising. In a CNBC interview Thursday, Crocs CEO Andrew Rees credited the brand’s China edge to early adoption of social selling on platforms like Douyin, China’s version of TikTok, where digital selling is two to three years ahead of global markets. He noted Crocs jumped on TikTok Shop the moment it launched in the U.S., quickly capturing the top two best-selling footwear spots on the platform. Crocs’ product mix resonates with consumers Meanwhile, Rees attributed some of Crocs’ success to “innovative new product at a great value.” Crocs shoes are largely priced in the $50 to $70 range, which is “relatively affordable” when customers are under economic pressure, he said. The company capitalized on the ballet flat craze by offering the popular style in a full spectrum of colors, prints and customizable options. By keeping price tags under $50, it is easy for consumers to grab more than one pair. “Newer lifestyle product such as the Ballet Flat resonated globally, reinforcing our view that the growth algorithm is becoming increasingly diversified beyond the core Classic Clog,” Barclays analyst Adrienne Yih wrote. Where does Crocs stock go from here? Crocs continues to build a loyal customer base that is, as its branding suggests, ” Wonderfully Unordinary .” “For many of our consumers, purchasing Crocs shoes is not a one-time transaction, but the beginning of an ongoing journey of personalization and self-expression. As leaders within the personalization space, we’re committed to finding new ways for consumers to express themselves,” said Rees on the third-quarter earnings call. CROX 3M mountain Crocs stock over the past three months. As for the shares, Crocs valuation is still reasonable at under 10 times forward earnings. “There is upside to the guidance, as CROX bought back ~500K shares between the end of 3Q26 and October, and that repurchase was not reflected in the guidance,” Williams Trading analyst Sam Poser wrote. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET. THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL’S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR. Click here for the full disclaimer.Read More
Crocs stock jumped 25% after earnings. Here’s why that might be just the beginning
Since CNBC flagged Crocs’ depressed valuation on Oct. 13, the stock has surged 30%, fueled by a massive 25.5% post-earnings rally on Thursday.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports