

Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
 LivestreamMenuJim Cramer and portfolio director Jeff Marks closed out a wild market week on Friday at the Investing Club’s fourth Annual Meeting at the New York Stock Exchange. They reviewed all 31 stocks in the Club’s portfolio in the wake of Tuesday’s election, which has cast doubt on the future of the artificial intelligence buildout. Jim made it clear that he believes there could be more turbulence ahead for AI stocks, but he also sees non-tech opportunities for those with cash on hand. FedEx and Kimberly-Clark are the names he recommended buying here. He said to wait for more selling in Johnson & Johnson and Eli Lilly before scooping up shares. Here’s our stock-by-stock review of the entire Investing Club portfolio: Apple : We view Apple as an “own it, don’t trade it” stock. The iPhone maker has a major advantage in the AI race because it can leverage the technology of its partner, Alphabet, without spending billions building its own data centers. Easing tariffs and a potential peak in memory prices could provide additional upside. Amazon : Investors overlooked the strength of its latest quarter, particularly the growth in its cloud unit, AWS. Unlike some hyperscalers, Amazon builds its own data centers rather than relying on heavily indebted neocloud providers, giving it greater control over its AI expansion. Boeing : We bought the post-earnings sell-off and would like to add more. Although the planemaker pushed back its $10 billion free cash flow target by roughly a year, we remain confident in CEO Kelly Ortberg’s turnaround efforts. Lower oil prices and resilient travel demand should support aircraft orders, making the recent weakness an opportunity. Bank of New York : CEO Robin Vince’s turnaround continues to deliver stronger profitability and operating efficiency. With limited credit risk and an attractive valuation, we see BNY as a compelling way to diversify the portfolio away from technology while maintaining exposure to a high-quality financial company. Cardinal Health : We trimmed our position following another excellent quarter to avoid giving back substantial gains. The pharmaceutical distributor continues to execute exceptionally well, particularly in its specialty business, but the stock’s nearly vertical rally warranted taking some profits. Capital One : Despite the credit card company’s inexpensive valuation and healthy credit metrics, investors are concerned that Democrats could renew efforts to cap credit card interest rates following their midterm victories. However, it’s unlikely the proposal would become law, as previous attempts have not resulted in anything material. So, we hold on, while being mindful of the headline risk. Costco : The wholesaler’s improving sales trends and stabilizing membership renewal rates reinforce our confidence in Costco. Management appears to be refocusing on the company’s core strategy of delivering exceptional value and driving sales volume. Though shares aren’t cheap at roughly 46 times earnings, we prefer Costco over Walmart . Salesforce : We remain confident in Salesforce as it partners with leading AI labs, most notably Anthropic, to integrate its software applications into their platforms. These partnerships reinforce our belief that Salesforce can benefit from AI rather than be disrupted by it. CrowdStrike : As artificial intelligence makes cybersecurity threats more dangerous, CrowdStrike stands to be one of the biggest beneficiaries. We remain bullish, but have periodically trimmed to rightsize its weighting in the portfolio. DuPont : We sold some shares of the supplier of industrial materials ahead of earnings, but remain encouraged by CEO Lori Koch’s execution following the Qnity spin-off. Its healthcare, water and industrial businesses provide exposure to attractive non-AI areas, while construction-related demand has held up better than expected. Eaton : The electrical equipment supplier remains an excellent company, but its exposure to data center construction makes it vulnerable to a slowdown in AI spending. With both Eaton and GE Vernova in the portfolio, we may need to trim one to reduce our overall exposure to the buildout. FedEx : This is a stock to buy right here. CEO Raj Subramaniam continues to cut costs and prioritize higher-value shipments, while new warehouse robotics could further improve efficiency. With management optimistic about the holiday season and oil prices potentially declining, FedEx can continue taking share from rival UPS. FedEx Freight : We still like the less-than-truckload shipping company following last week’s strong quarter, which demonstrated the benefits of operating independently. However, FedEx’s remaining 20% stake creates an overhang that may be keeping large institutional investors on the sidelines. We’d prefer to wait until that block of shares is sold before making a more substantial purchase. GE Vernova : We still believe in GE Vernova’s long-term growth prospects, supported by strong turbine demand, grid modernization and a backlog extending into the early 2030s. But, as mentioned with Eaton, we’re weighing whether to reduce exposure to AI industrials as investors sour on the broader data center trade. Alphabet : Although Google Cloud continues to deliver exceptional growth, we’re concerned that Gemini could increasingly cannibalize Google’s core search business. The company’s decision to issue shares rather than repurchase them also dents our confidence, making Alphabet our least favorite of the major hyperscalers. Goldman Sachs : We added to our position on Thursday and would be happy to buy more. At roughly 12 times earnings, the stock looks inexpensive given its strong investment banking and trading businesses, which should benefit from heightened market volatility. Goldman is also a lead underwriter on Anthropic’s planned IPO, which could be another potential catalyst if the offering helps restore confidence in the AI trade. Home Depot : Our thesis hasn’t entirely gone according to plan, as housing market activity remains subdued. But shares have performed much better since early October as bond yields retreated, underscoring why we’ve stayed patient and the importance of diversification. Intel : This position has become a terrible mistake after the chipmaker issued disappointing guidance last week. No way around it. Jim apologized for not fully recognizing how the CPU renaissance could be derailed by a PC slowdown and a factory fire. Management will need to rebuild credibility. Johnson & Johnson : The drugmaker and medical technology giant has been a terrific winner for us since we switched out of Bristol Myers Squibb this spring. J & J has a robust drug pipeline, and one of its existing cancer drugs just secured expanded approval from the FDA. Kimberly-Clark : The Huggies parent reported better-than-feared third-quarter results on Thursday, and the closure of the Kenvue acquisition on Monday is a big milestone. We’re optimistic that CEO Michael Hsu will improve operations at the owner of Tylenol and Neutrogena. Plus, Kimberly pays a nice dividend. Jim said that if you wanted to build a 100-share position, buy 25 shares right now. Eli Lilly : A longtime holding for us, Lilly has the leading injectable GLP-1s and an impressive pipeline of next-generation assets in its pipeline. We trimmed some Thursday out of discipline. But if there’s another sell-off in Lilly, this would be a name to buy. Linde : This is another long-term stalwart in the portfolio. It’s had a nice gain this year, benefiting from supplying gases to semiconductor manufacturers. The one blemish is its home healthcare unit, known as Lincare. However, the company has taken the problem seriously, reinforcing our trust in senior leadership. Meta Platforms : We must stay mindful of Meta’s plans to commence an at-the-money stock offering next year. Though shares have been hit in the AI sell-off, that has made us feel better about our trim in September during the height of the Muse agent excitement. This name can rise over time. Microsoft : The rare hyperscaler that’s remained free cash flow positive, Microsoft has righted the ship in a remarkable way over the past two quarterly reports. CFO Amy Hood is a disciplined executive. It’s become a must-own. Micron : We’re not in a hurry to add to our position given the uncertainty around the AI trade right now. The potential start of a monster buyback program in December is a promising catalyst. We do regret not peeling off any stock into its big run from September into early October. Nvidia : Speaking of large buybacks, Nvidia has a more than $200 billion authorization, and we want to see the chipmaker deploy it aggressively and routinely be in the market offering support when shares are under pressure. We’re not deviating from our “own it, don’t trade it” mantra. Palo Alto Networks : Similar thesis to fellow cybersecurity vendor CrowdStrike. One thing with Palo Alto that really shines is CEO Nikesh Arora’s track record of making smart acquisitions before the target company’s business really inflects. CyberArk in the identity security space is a recent example of this. Qnity Electronics : The semiconductor materials supplier reported an excellent beat-and-raise quarter earlier this week. In such a fraught moment for AI names, the market didn’t give Qnity any credit. Though off its year-highs, we’re not putting Qnity in the troubled camp. It benefits more from the rise in chip volumes than from price. Starbucks : CEO Brian Niccol has the coffee chain firing on all cylinders and outperforming competitors. Starbucks’ decision to not raise prices to keep up with inflation helped win customers. Now, margins are starting to improve. TJX Companies : Last quarter was shocking — and not in a good way —as its most important reporting segment—home to T.J. Maxx and Marshalls—disappointed. So far, we’ve been rewarded for buying the dip. Need to see an improvement in the upcoming quarter to restore our faith in the off-price retailer we’ve loved for years for its reliability. Wells Fargo : The asset cap is gone, and we’re looking for a strong 2027. Shares look cheap, and CEO Charlie Scharf has straightened out the company and invested in building out an investment bank and other fee-based businesses. We take a longer-term view with this one. (See here for a full list of the stocks in Jim Cramer’s Charitable Trust.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
Here’s a rapid-fire update on all 31 of our stocks, including 2 to buy now
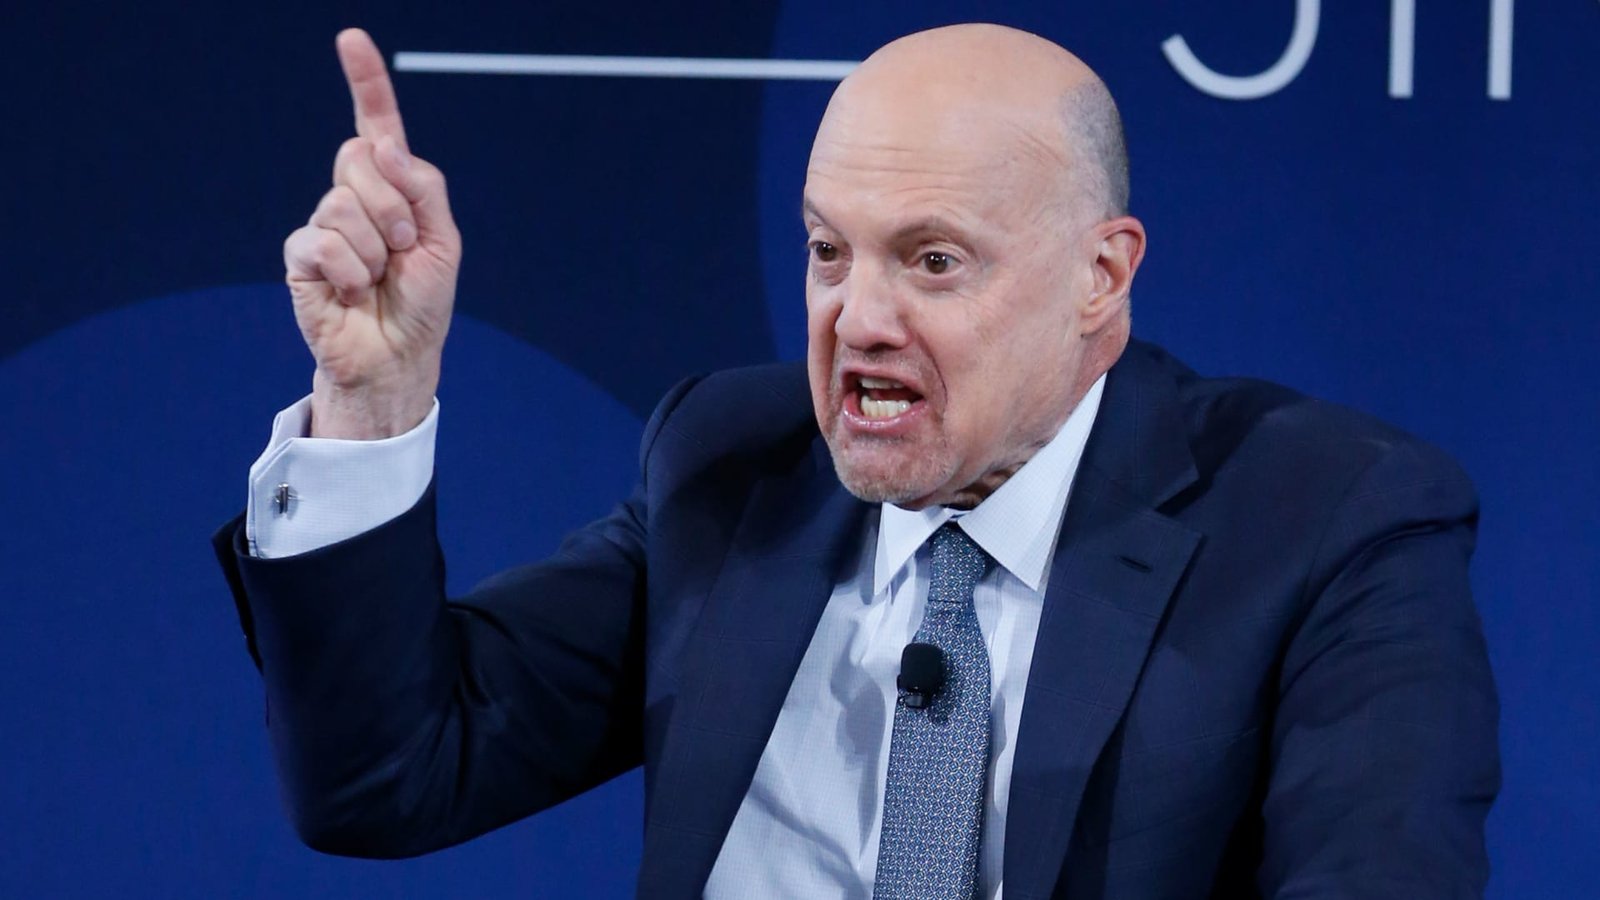
We closed out a wild market week on Friday at the Investing Club’s fourth Annual Meeting at the New York Stock Exchange.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News


Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports


