Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
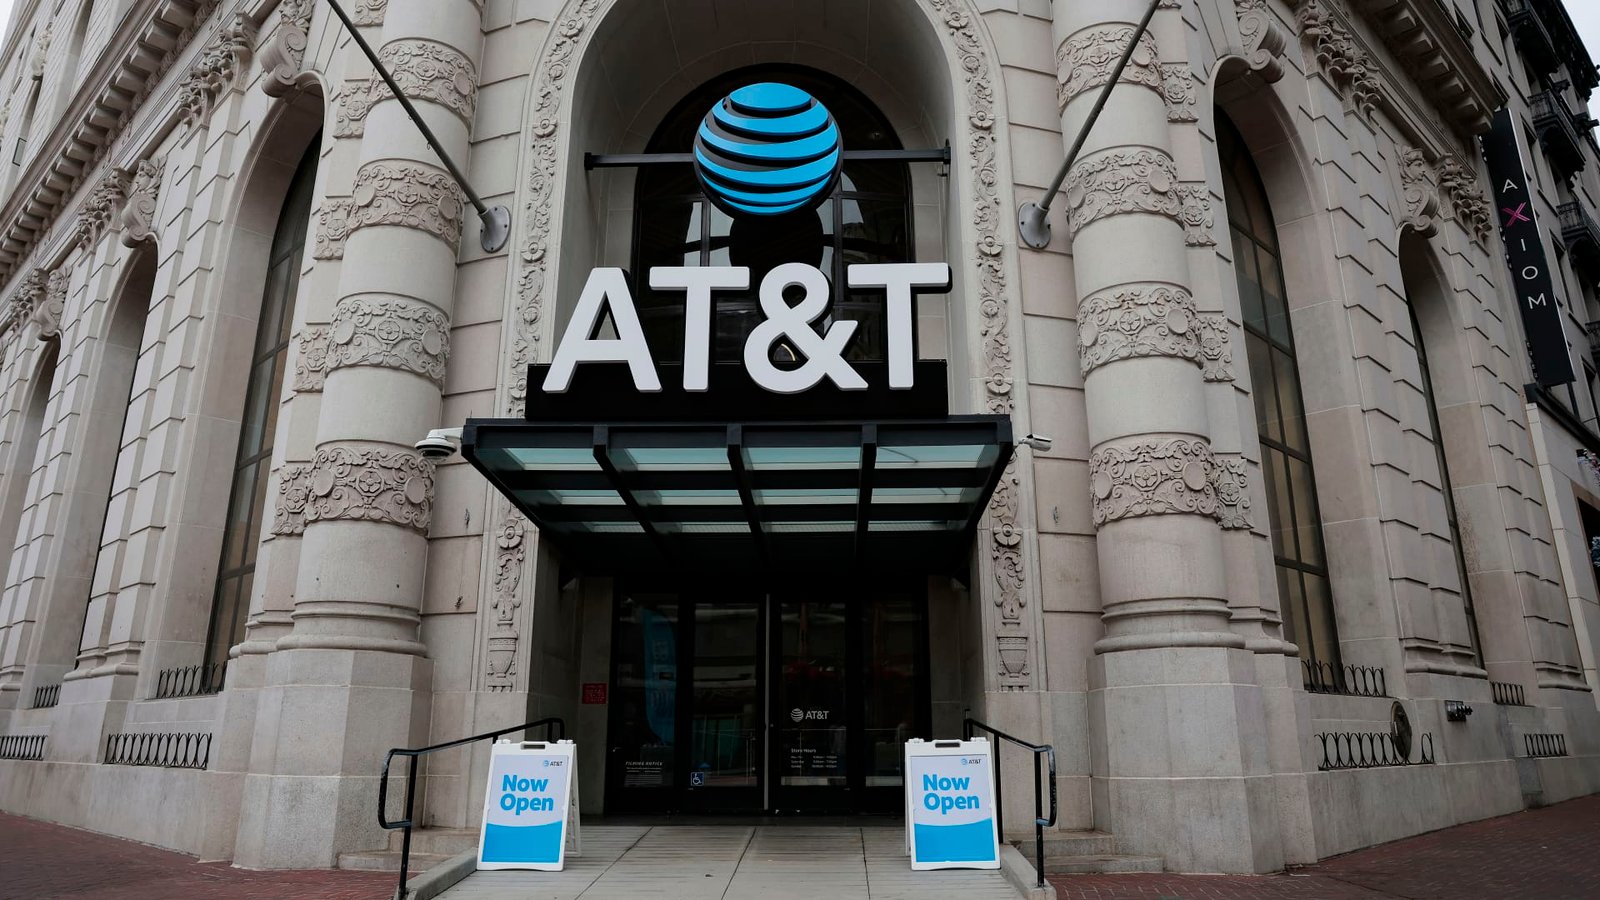
 LivestreamMenuAnalysts at Bank of America said there’s plenty of buying opportunities that can act as safe havens, even as the stock market remains jittery. The Wall Street investment bank sees more room to run in stocks such as AT & T. Other companies rated buy at Bank of America and screened by CNBC Pro include: US Bancorp, Krispy Kreme , Madison Square Garden Entertainment and L3 Harris Technologies. Krispy Kreme There are several positive catalysts ahead for the donut store owner and franchisee, according to analyst Sara Senatore. After Krispy Kreme’s latest earnings report, Bank of America came away feeling more confident despite a host of consumer headwinds. “DNUT held its F26 adj. EBITDA guide despite edible oils and fuel moving higher since 2Q, which we view as the clearest evidence yet that the turnaround savings are durable,” Senatore wrote. Senatore also noted the continued growth of Krispy Kreme’s Fresh Delivery service, which brings products into grocery and retail stores. Meanwhile, the stock is up 20% this month. “Our Buy rating is supported by Krispy Kreme’s distinctive and popular product offering, ability to leverage existing capacity to drive higher returns and long term opportunity to grow U.S. and Canada access points to 15,000,” Senatore said. Madison Square Garden Entertainment Musician Harry Styles helped the entertainment and concert company to another robust earnings report, Bank of America said recently. “While Harry Styles provided an outsized contribution, we believe the quarter reinforces the earnings power of MSGE’s irreplaceable venue portfolio and the opportunity for continued growth through utilization, pricing and ancillary spending,” analysts led by Peter Henderson wrote. In addition, the bank says Christmas should provide even more upside. “The Christmas Spectacular provides another earnings driver, with 231 planned shows (vs 215 last year) and advance ticket revenue pacing ahead,” he said. Madison Square Garden shares are up 48% this year. L3 Harris Technologies The aerospace and defense company is firing on all cylinders, according to Bank of America. Analyst Ronald Epstein recently met with L3 Harris’ new CEO and walked away feeling more bullish on the stock. “He gave three clear priorities: 1) improve and optimize execution, 2) grow the international business, which is 24% of revenue today, and 3) stay away from transformational M & A,” Epstein said. The bank also said it likes L3’s wide ranging portfolio and noted it’s well positioned to participate in the space sector. “We believe the new team will be well received by investors,” he said. The stock has climbed in five out of the past six weeks, rising almost 5% in the last five days alone. AT & T “Reiterate AT & T as our Top US telecom stock pick We reiterate our Buy rating and $34 price objective after better than forecast 3Q26 results. AT & T is our top telecom pick on best mix of wireless and fixed assets, a balanced approach to subscriber gains and profitability, attractive dividend yield, share repurchase program and improving FCF and EPS growth.” US Bancorp “At 9.7x 2027E EPS vs. 10% average annual EPS growth FY27/28 and 1.7x YE27E TBV vs. 18% ROTCE, valuation remains compelling for a turnaround still in its early innings … We expect the stock to outperform as double-digit EPS growth underpinned by fixed asset repricing and diversified fee revenue streams, combine[s] with management commitment to positive operating leverage.” Madison Square Garden Entertainment “While Harry Styles provided an outsized contribution, we believe the quarter reinforces the earnings power of MSGE’s irreplaceable venue portfolio and the opportunity for continued growth through utilization, pricing and ancillary spending … The Christmas Spectacular provides another earnings driver, with 231 planned shows (vs 215 last year) and advance ticket revenue pacing ahead.” Krispy Kreme “DNUT held its F26 adj. EBITDA guide despite edible oils and fuel moving higher since 2Q, which we view as the clearest evidence yet that the turnaround savings are durable … Our Buy rating is supported by Krispy Kreme’s distinctive and popular product offering, ability to leverage existing capacity to drive higher returns, and long term opportunity to grow U.S. and Canada access points to 15,000.” L3 Harris “[The CEO recently] gave three clear priorities: 1) improve and optimize execution, 2) grow the international business, which is 24% of revenue today, and 3) stay away from transformational M & A … We believe the new team will be well received by investors.”Read More
Bank of America says these stocks have major upside potential in an uncertain market
Bank of America named several stocks that still have more room to run despite market jitters.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports