Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
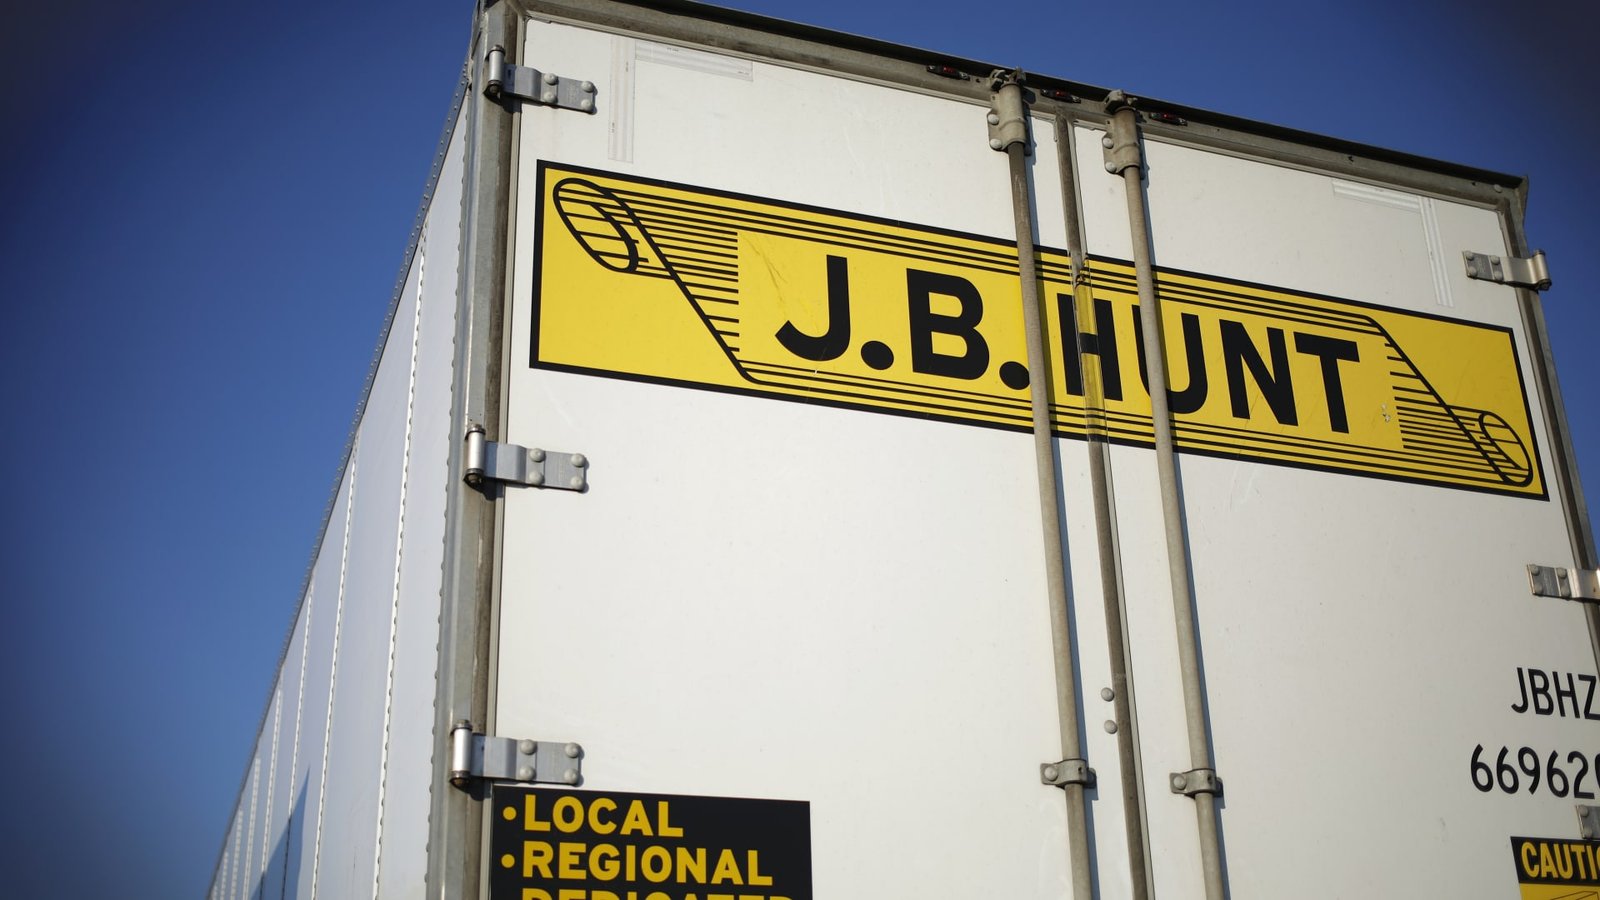
 LivestreamMenuJ.B. Hunt Transport Services is poised to bounce back, even as investors wring their hands over trucking company’s rising costs, according to Citizens. The investment firm upgraded the transport stock to market outperform from market perform. It has a $300 price target on shares, suggesting roughly 27% upside from Wednesday’s close. “The catalyst for our ratings upgrade is an 18.3% pullback in JBHT shares since its strong 2Q26 earnings release in July, bringing the shares to a more attractive level at 110% of the S & P 500 [price-to-earnings] on our 2027 [estimate for earnings per share (EPS)],” analyst Jeff Kauffman said Thursday in a note to clients. Shares of J.B. Hunt plunged 13% on Wednesday after the company warned investors it foresees an up to 10% quarter-over-quarter earnings decline. CFO Brad Delco attributed the hit to rising costs tied to recruiting, advertising, onboarding, training and sign-on bonuses. The stock has slid more than 11% over the past three months. JBHT 3M mountain Shares are down more than 11% over the past three months. However, Kauffman noted that J.B. Hunt’s higher costs will eventually be offset by surcharge and rates, leading its shares to regain ground. “While [an increase in costs] is an industry-wide concern given the 37.3% increase in on-highway diesel prices since the July 4th weekend, it is also JBHT-specific to a modest degree as the tightest driver shortage we have been hearing about is in intermodal drayage,” Kauffman wrote. “In the long run, these costs will be offset by surcharges and rates, but in the short run, it will be a 2026 EPS drag.” Citizens’ call falls in line with consensus on the Street. Of the 25 analysts covering J.B. Hunt, 14 have a buy or strong buy on the stock, LSEG data shows.Read More
Citizens says buy the dip on this trucking stock
The investment firm upgraded the transport stock to market outperform from market perform.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets news People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports