Commentary: Which G7 economy is the poster child for debt woes?
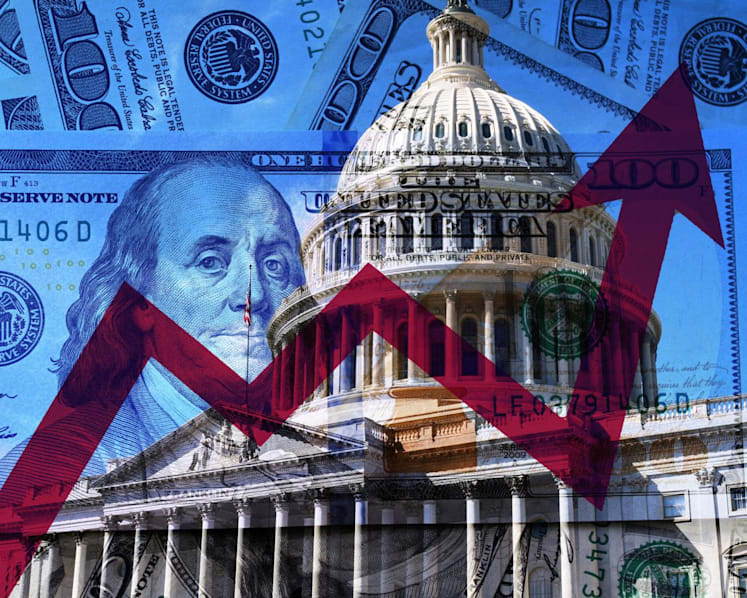
Among the G7, France and the US are heading into a wall, says Chris Giles for the Financial Times.
The logo of the G7 Finance Ministers and Central Bank Governors’ meeting is displayed at Niigata station in Niigata, Japan, May 10, 2023. REUTERS/Issei Kato
Read a summary of this article on FAST.
Get bite-sized news via a new
cards interface. Give it a try.
Click here to return to FAST
Tap here to return to FAST
FAST
LONDON: At its annual meetings last week, the International Monetary Fund (IMF) pre-empted the Trump administration’s demand that it get “back to basics”. Out went climate concerns and women’s rights in favour of a discussion on the parlous state of the public finances, especially in leading advanced economies.
Opening the meetings, IMF managing director Kristalina Georgieva said: “What is our loudest call to policymakers right now? Make urgent repairs to the fiscal house before the cracks widen.” Her message was directed at G7 countries too big for rescue financing from the fund.
Apart from the US Treasury Secretary Scott Bessent, who did not turn up at the meetings in Bangkok, most finance ministers nodded along and pointed to domestic forecasts of deficit reduction. Promises of immediate action were absent.
POOR RECORD OF FISCAL REPAIR
That is understandable. Public finances can run on unsustainable paths for a very long time before anything blows up.
Guess Word
Crack the word, one row at a time
Buzzword
Create words using the given letters
Mini Sudoku
Tiny puzzle, mighty brain teaser
Mini Crossword
Small grid, big challenge
Word Search
Spot as many words as you can
The record of fiscal repair among G7 countries is, in fact, worse than Georgieva outlined. Over the past decade, the IMF has repeatedly had to revise higher its expectations of G7 deficits.
Before the pandemic, the fund would generally expect deficits to settle at around 2.5 per cent of gross domestic product. This month’s forecasts predict stability at over 6 per cent, a figure that will put debt on an ever-rising path and eventually force at least one G7 country into crisis.
Canada and Germany are entirely immune from being the countries at the sharp end of a market rout. Both have low debt and a history of prudence. Germany has raised its deficits recently to fund defence and investment expenditure, which should never have been cut so hard in the first place. This pair has little to worry about.
I can also tentatively rule Japan out of the running as the poster child for profligacy. Although its net debt is the second highest in the G7 in 2026, it has regularly run much smaller deficits than forecast over many years. While politicians such as Prime Minister Sanae Takaichi talk a good game about fiscal expansion, the finance ministry keeps a tight hold of the reins.

After Japan, things get more difficult. Italy has one of the highest net debt levels in the G7 but the Eurozone crisis of 2010 to 2015 prompted it to run persistent primary surpluses, which it has consistently achieved. Its debt ratio is also stable. This is not the recipe for a crisis.
The United Kingdom was perhaps excessively praised by the IMF for its fiscal consolidation plans last week. Next week’s Budget is likely to show slippage and Britain has a nasty habit of being an unreliable boyfriend on the deficit, always promising probity without delivering it. It needs to show it can achieve deficit reduction, not just talk about it.
HEADING INTO A WALL
That leaves France and the US. Both have a record of not only promising lower deficits that never arrive but also having high deficits and rapidly rising levels of debt. On the IMF’s latest forecasts, both will exceed Japan’s net debt ratio by 2031, and only Japan has a record of beating IMF predictions.
Politics in both is hostile to the necessary reforms for deficit reduction.
In France, far-right leader Marine Le Pen speaks of responsibility but has opposed the pension age reform that is central to healthier public finances. More centrist politicians cannot pass a budget.
In the US, neither political party sees any benefit in fiscal prudence as an electoral strategy.
The IMF was careful to say that reform was urgent rather than predicting an imminent disaster. But fiscal problems are rather like demographics in being extremely easy to predict apart from the moment the dam breaks.
Among the G7, France and the US are heading into a wall. The consequences will be ugly. We just do not know which country will crash first.
Source: Financial Times/sk
Sign up for our newsletters
Get the CNA app
Stay updated with notifications for breaking news and our best stories
Get WhatsApp alerts
Join our channel for the top reads for the day on your preferred chat app
Get bite-sized news via a new
cards interface. Give it a try.
Click here to return to FAST
Tap here to return to FAST
FAST