Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
 LivestreamMenu
- For most investors, the best advice is to do nothing when it comes to a core investment like the S&P 500 Index and any money being invested for long-term financial planning like retirement: Set it and forget it, as the saying goes.
- But with tech stocks rising to represent as much as 40% of the U.S. large-cap equity market, many experts have recommended a move into equal-weight S&P index funds to avoid the concentration risk.
- In August and September, the equal-weight approach posted its longest losing streak since 2022. Now, it’s tech stocks that are looking shaky again.
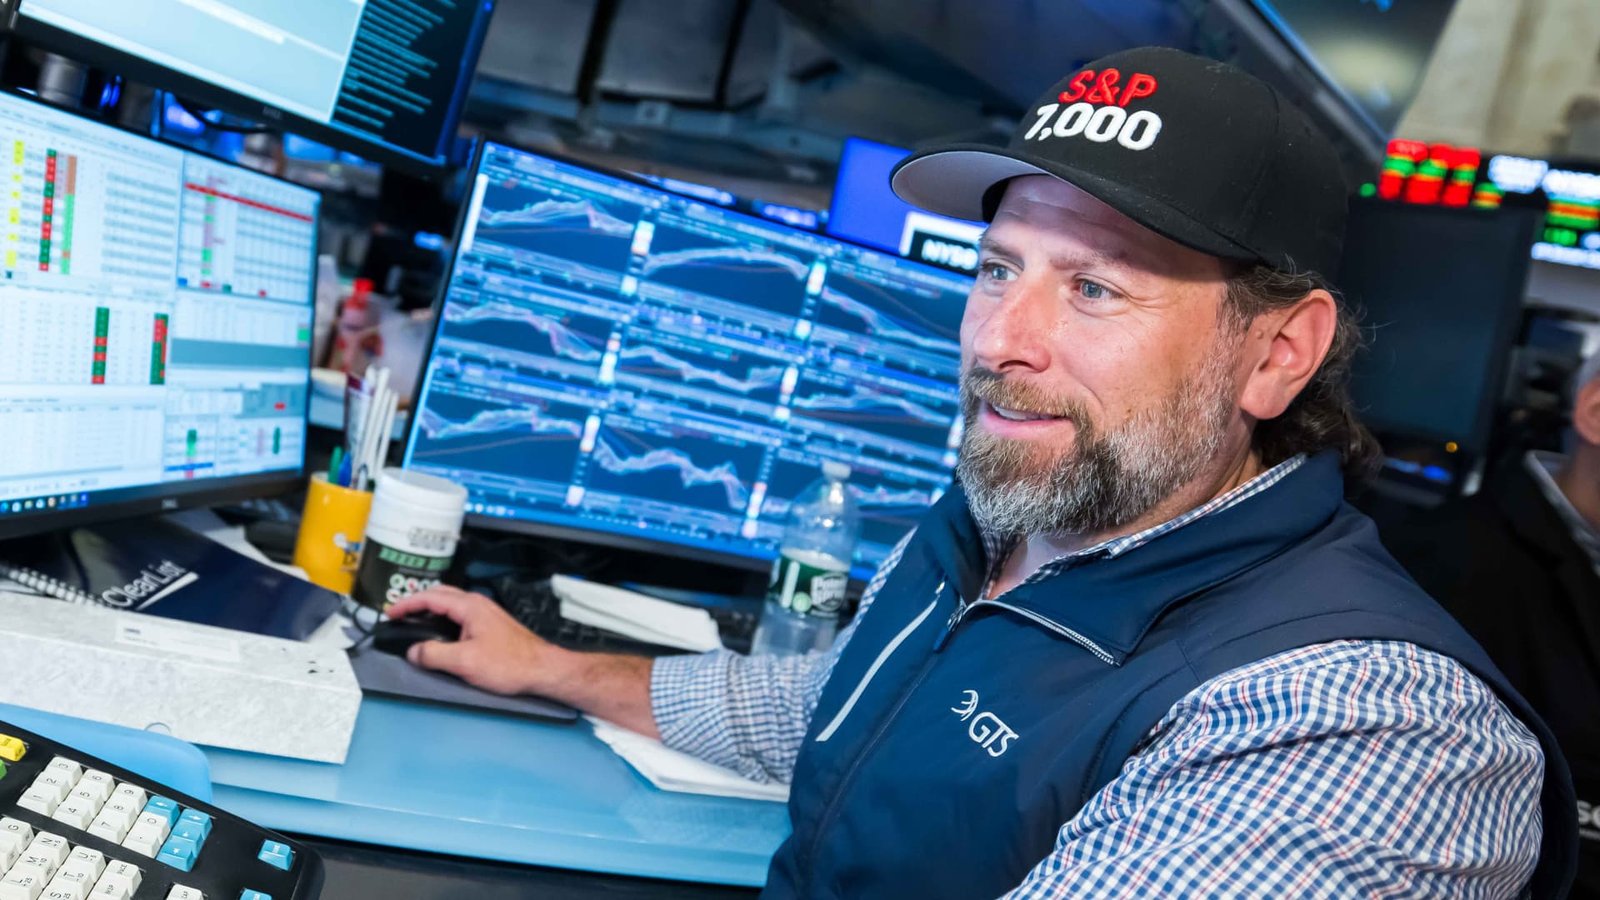
Traders celebrating at the New York Stock Exchange on April 15, 2026, as the S&P 500 closed above the 7,000 level for the first time.NYSE
Long-term investors who follow one simple piece of advice have tended to benefit from it: as the market twists and turns, do nothing. But the S&P 500 of today, and the bull market of the past decade, are unique in some ways, led by a concentration at the top in a handful of tech stocks that has few historical precedents.
One “something” that investors have been advised by experts to consider is a move into equal-weight S&P 500 funds to mitigate the risk of having such a high level of exposure to one trade. Well, that didn’t exactly work out the way it was supposed to in 2026.
What did investors who adopted the equal-weight approach get? To date, another year trailing the standard market-weight S&P 500 in performance. September was the most brutal month of all for equal weight, capping its longest multi-week losing streak since 2022, with the index falling more than 4%.
To be clear, investors aren’t losing money going with equal weight, but they have been making less than investors who stuck with the standard S&P 500.
In recent weeks, the gains made by the index have been highly concentrated, with the S&P 500 hitting new highs even as more of the 500 stocks that comprise the benchmark hit new lows than highs individually. Market breadth, the jargon for how many stocks across the index are contributing to gains, has fallen to its lowest level since the dotcom bubble, according to a recent Goldman Sachs analysis. Meanwhile, going back to the start of 2024, a recent analysis from The Kobeissi Letter finds that a basket of 42 AI stocks generated 67% of the S&P 500’s price return.
Stock Chart IconStock chart icon Performance of the market-weighted S&P 500 over the past five years versus the performance of its equal-weight counterpart.
An analysis this week from DataTrek Research noted that the equal weight S&P 500 has “consistently lagged the market cap weighted version of the index over any given 1-year holding period for almost four years. Moreover, the gap is both larger and has run longer than any point in the last +20 years.”
But that has left the market cap-weighted S&P “dramatically overweight,” the tech sector, it wrote, and it means equal weight is still at least a “partial substitute” to deal with the risk.
The technology concentration in the S&P 500 isn’t going away. Tech stocks now represent about 16% of the equal-weight S&P 500 versus still nearly 40% in the standard index. And now it is tech stocks suddenly looking like the market’s shakiest members again, maybe not entirely unrelated to the recent run.
Don’t throw equal-weight investing concept out
Equal-weight does still offer a potential response, but the correct way to think about it might be to remove any thought of it being an either/or choice.
“The answer is mostly don’t just own an equally weighted ETF,” said Todd Rosenbluth, head of research & editorial at TMX VettaFi.
Rather, he says to combine the cap-weighted ETFs and equal-weight options within a portfolio. That means on the market-weight side, allocating to ETFs such as Vanguard’s VOO or State Street Investment Management’s SPYM — which has become a massive winner this year thanks to its ultra-low expense ratio, undercutting iShares’ IVV, and seeing its assets balloon by over $50 billion after becoming the default Trump Account investment.
On the equal-weight side, it can still mean allocating to an ETF like Invesco’s equal-weight S&P 500 fund, RSP, which holds the same amount of each of the 500 stocks, though weights can shift between quarterly rebalancing periods. Or, Rosenbluth says, investors can adopt the equal-weight approach at the sector level, using an ETF like the ALPS Equal Weight Sector ETF, EQL, which can serve the same purpose of reducing market concentration in technology stocks.
He says the recent period of underperformance for equal weight is no reason to throw out the concept. In fact, as tech stocks sputter again, it’s a moment to reconsider how to employ the concept.
“The recent strength in the cap-weighted ETFs is a further sign of investors putting too few eggs in one basket. If you are a long-term investor who worries the market is being driven by a few stocks, you have alternatives to consider,” he said.
Some experts dismiss the equal-weight mantra and say that if an investor wants to enact a strategy reflecting this approach, just invest in a mid-cap fund in addition to a core S&P 500 holding. Rosenbluth says investors can attempt to balance out the top-heavy S&P 500 through the addition of mid-cap funds, with iShares’ core mid-cap portfolio IJH one example.
“They provide exposure to a different set of companies with a mix of growth and stability traits. But these are not large-cap companies. So you are adding different companies to your portfolio for potential diversification benefits,” he added.
Todd Sohn, chief ETF strategist at Baird Strategas, says investors do need to have their eyes wide open in a market where Nvidia is larger than the entire consumer discretionary sector of the S&P 500. To him, the message to take away is “all about surrounding the core of a portfolio with ‘low Tech, low correlation’ alternatives.”
He says considering an actively managed approach to the “SMID-cap” segment of the market, stocks bridging the gap between small-cap and mid-cap, is a way to manage risk going forward. Or at a minimum, he adds, split an allocation between passive SMID and active SMID.
But Sohn adds that diversifying away from the S&P 500 risk in this environment can also mean thinking about sectors such as natural resources and energy, from metals & mining names to underlying commodities. “Real assets are a diversifier in this environment,” he said.
And in fixed income, while recent days have seen bond yields ease off, leading some experts to suggest the worst of the yield surge may be over (though the reasons for that could be tied to a more skeptical outlook on the economy and stock market), Sohn recommends sticking with high-quality, short-duration investment grade fixed income.
Sohn says there are moments in time when equal-weight S&P works, but that’s been more of an “easy button” to press in the past, and it is not equal to the task of trying to surround the AI-heavy core of portfolios now.
DataTrek’s research shows that the equal weight S&P flipped from outperforming the market cap-weighted index in the decade of 2004-2014 (by 3.2 points on average) to underperforming since 2015 (average of -2.8 points). The global financial crisis and the equal-weight index’s underweight in financials helped a lot.
But since the start of this decade, it has only outperformed in 2021, during the height of the speculative stock bubble, and in 2022, when tech stocks took a particular pummeling relative to the rest of the market.
“From mid-2023 to the present, equal weight has consistently underperformed over almost any given 1-year holding period, its longest rough stretch since at least 2004,” DataTrek wrote in its analysis.
What is an investor to conclude?
DataTrek says that is up to the investor. You can decide it is “no longer a valid investment approach in a world that concentrates incremental profitability and therefore equity value in a relative handful of largely AI-related businesses.”
Or, “that the market has overestimated the value of the world’s largest Tech companies, and a reckoning is nigh. The 2008 – 2018 experience lends credence to the second argument. Tech’s long history of structural outperformance, driven by continual reinvention and disruptive innovation, supports the former.”
Ultimately, DataTrek says investors are lucky to have ETFs to enact both approaches. “We do not see the two versions as competitors, but rather useful partners in portfolio construction,” it wrote.
 watch nowVIDEO06:42’Fast Money’ traders talk if the bull market is running out of steamFast MoneyChoose CNBC as your preferred source on Google and never miss a moment from the most trusted name in business news.Read More