Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
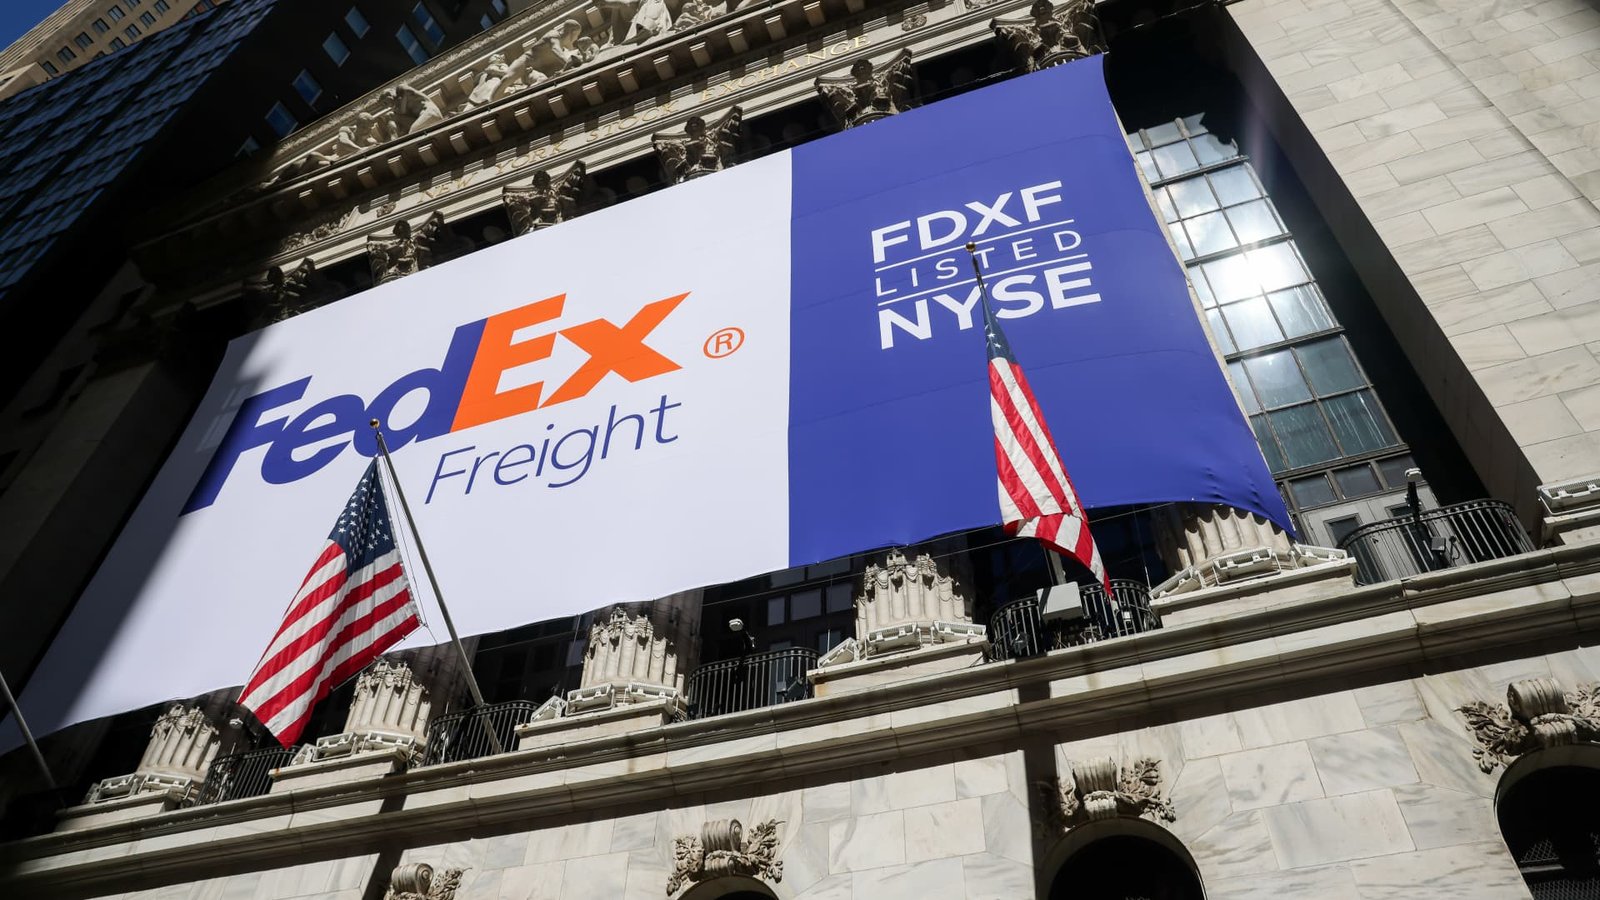
 LivestreamMenuFedEx Freight on Thursday night took a positive step forward in its young journey as a standalone public company. In its first official earnings report since being spun off in June, the less-than-truckload shipping provider delivered a top and bottom line beat and offered encouraging commentary on its self-help improvements. Revenue in the three months ended in September rose 8% to $2.44 billion, beating the LSEG consensus of $2.33 billion. Adjusted earnings per share (EPS) totaled $1.49, exceeding the consensus of $1.36, LSEG data showed. Bottom line Shares rose about 3% in extended trading, a welcome market reaction considering how badly the stock has struggled. After a decent debut in June, FedEx Freight has been drifting lower, seemingly with no end. Anytime a stock is spun off, there can be an adjustment period as investors who received shares due to ownership in its former parent decide to dump it. Plus, elevated fuel prices have weighed on stocks across the transportation industry, complicating matters for FDXF shares. As a reminder, FedEx Freight is a less-than-truckload carrier. LTL services consolidate shipments from multiple customers onto a single trailer. Think of these shipments as too large for standard parcel delivery, such as something over 150 pounds or a few pallets of product, but not big enough for the customer to need a whole truck. Its competitors include Old Dominion Freight Line , XPO and J.B. Hunt . FDXF ALL mountain FedEx Freight’s stock performance since its June debut. Though it hasn’t been fun to endure this drawdown in FDXF, we haven’t bailed on the name because our investment thesis centers on FedEx Freight making operational improvements now that it’s no longer part of FedEx Corp . We recognized that it cannot be accomplished overnight. That’s what made Thursday’s earnings report such an anticipated event — a chance to update investors on its progress and show what’s in store for next year. Aside from an August investor conference, we haven’t heard from Freight management since late June, when the company discussed the results of its final quarter inside FedEx. For example, Freight believes it has more leverage in pricing negotiations as a standalone company than it did under FedEx, where contracts were bundled with package delivery and other transportation services. “Since June 1, we have successfully renewed approximately 25% of our contractual portfolio and achieved our strongest renewal pricing performance in recent years,” FedEx Freight CEO John Smith said Thursday night. “Given that approximately two-thirds of our revenue is generated under negotiated customer pricing agreements, we believe our contractual renewal performance provides meaningful support for future yield improvement.” Another benefit of being on its own: FedEx Freight has built up a dedicated salesforce focused on the less-than-truckload market, where the company is pursuing winning more business in attractive industries. “When you think about some of the verticals where we see some improvement, one of them is in aerospace. We landed a few new accounts, as well as grown some of the existing accounts. And we’re up, through the first four months, about 3%,” Smith said. “That’s one example. We’re seeing movement in food. We’re seeing movement in some of technology. Probably the one that we’ve seen the most success in is the retail space, and we continue to grow that. We feel pretty good about our plan, and how we’re going after and attacking these verticals. So, more to come, and I think you’ll see more progress as we move forward on our next quarter and into 2027. We still prefer FedEx Corp over FedEx Freight at this juncture, and our position weightings in the portfolio reflect this sentiment. But Freight’s stock has come down hard despite generally solid results, so we’ll continue holding this spin-off for now. We’re reiterating our buy-equivalent 1 rating. However, we are reducing our price target to $160 from $175 to better reflect the price-to-earnings multiple compression the trucking group has experienced over the past four months due to the restart of the Middle East conflict and associated rise in fuel prices. For its part, FedEx reported better-than-exected results of its own Wednesday night. Though shares were down a few percentage points in Wednesday’s extended trading, likely due to a soft current-quarter outlook, the stock encouragingly finished up 1% in Thursday’s regular session. That suggests investors agreed with us and were unfazed by the guide. Commentary In addition to the strong headline results, FedEx Freight reported a 1.1% year-over-year increase in revenue per shipment (ex-fuel surcharges) to $316.78, helping to more than offset a 0.7% decline in average daily shipments. Also notable, the cadence of average daily shipments has been improving each month since March. For the reported period, shipments were down 3.4% in June, improving to minus 2.2% in July, minus 0.7% in August, and flipping to up 0.9% in September. Another positive: 98% on-time service and pick-up reliability should also help the company steal some share from others in the LTL space, during the crucial shopping season. The company’s claims ratio and the frequency of claims have both continued to trend lower since 2022, exiting the period at 0.43% and 0.27%, respectively. This is a sign of improved customer service quality, which is good to see no matter what industry you’re talking about. Guidance Fourth-quarter guidance is as follows: Revenue of $2.30 billion to $2.37 billion, ahead of the $2.2 billion expected, according to LSEG. Adjusted operating income between $185 and $205 million, ahead of the $172 million FactSet consensus estimate. Adjusted operating margin between 8% and 8.6%, versus expectations of 7.7%, according to FactSet. Adjusted EPS of between 65 cents and 75 cents, ahead of the 53-cent LSEG consensus estimate. — Portfolio analyst Zev Fima contributed to this earnings analysis. (Jim Cramer’s Charitable Trust is long FDX, FDXF. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
FedEx Freight delivers a much-needed quarterly beat. Where we stand on shares now
Shares have struggled since their June debut. But this is a nice step forward.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News

Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports