Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
 LivestreamMenu
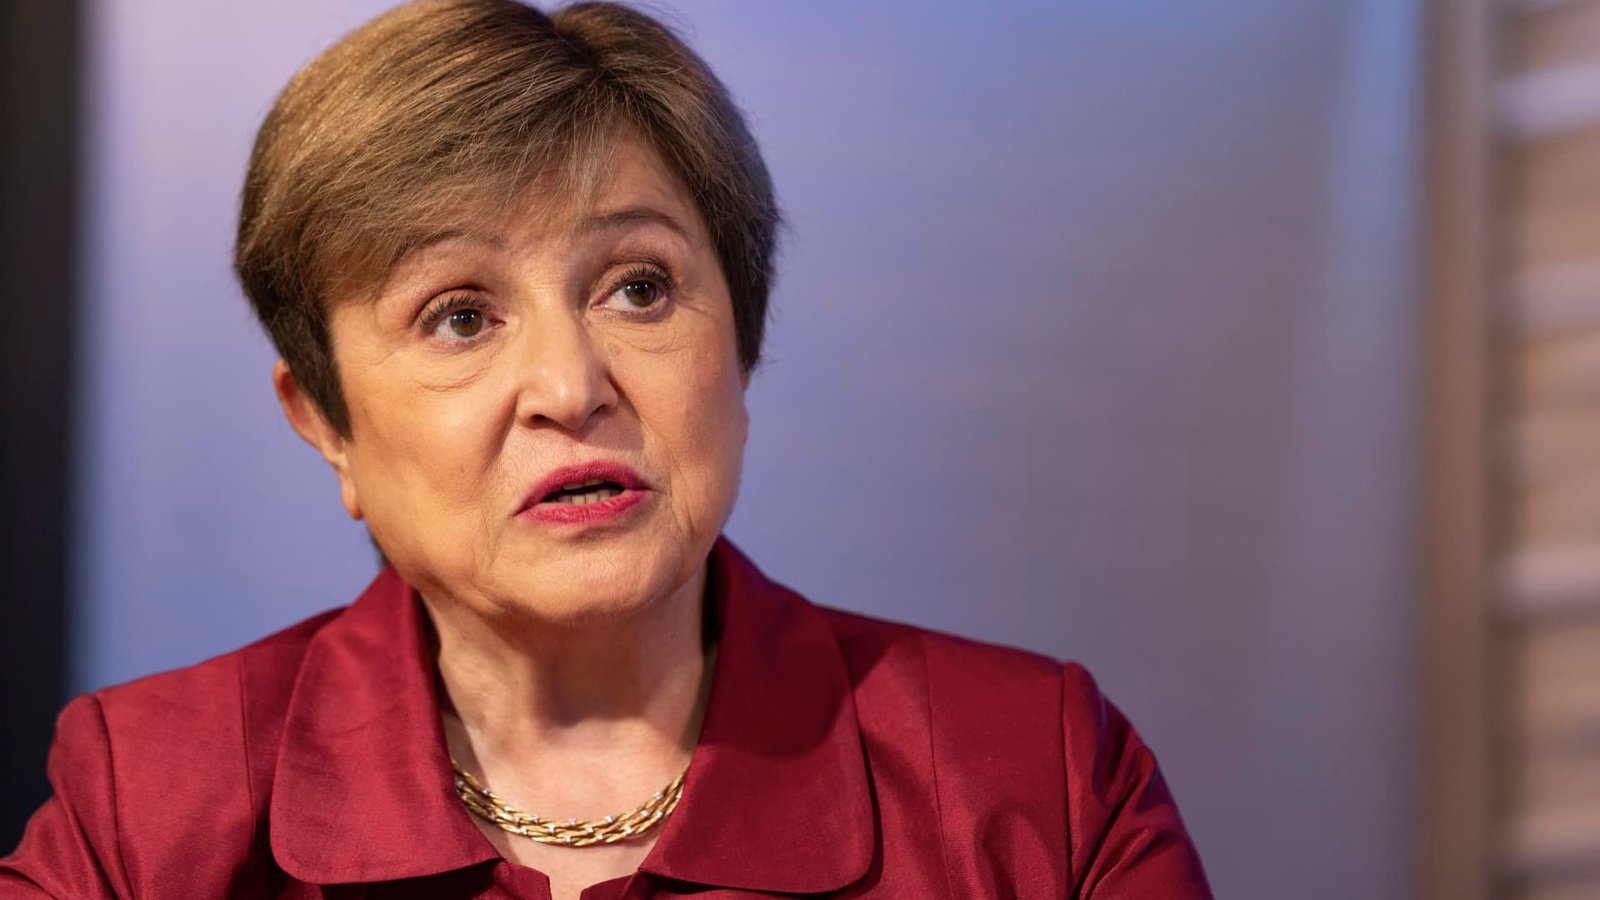
- IMF Managing Director Kristalina Georgieva said Wednesday that the French government must reduce its deficit to reassure bond markets of its credibility.
- France is about to start budget negotiations, with the government targeting a fiscal adjustment worth tens of billions of euros.
- The country is also facing a fresh political crisis in the form of nationwide student protests, which have turned violent.
 watch nowVIDEO06:08IMF’s message to France: Get your house in orderSquawk Box Europe
The head of the International Monetary Fund had a blunt message to the French government in a CNBC interview on Wednesday: bring your finances under control.
France is currently in the throes of another political crisis, with violent student protests now stretching into their third week.
The movement – which has seen young people across the country demonstrate discontent with long study days, teacher shortages and rundown schools – comes as the French government seeks to win over a politically fractured parliament and convince lawmakers to agree to tens of billions of euros worth of spending cuts.
Political instability in France has put pressure on the country’s government bonds, known as OATs. Investors now demand a higher yield than they do for bonds issued by the Italian government, with French 10-year bond yields rising by more than 100 basis points since the start of the year.
“What we see in France is a complication of, on one side, the consequence of borrowing shock after shock after shock, climbing on this staircase that does not lead to heaven, and on the other side, a political dynamic scene in France that creates more difficulties for the finance ministry to put a clear path for tightening,” IMF Managing Director Kristalina Georgieva told CNBC’s Lisa Kim on the sidelines of an event in Singapore.
She noted that there is a “very clear recognition in France that deficit needs to be brought under 5%.”
France is subject to the EU’s excessive deficit procedure, with the bloc recommending the country bring its national deficit closer to a reference value of 3%. Last year, France’s deficit reached 5.1% of GDP.
But when asked if the current situation in the French bond market echoed the euro zone sovereign debt crisis of the early 2000s, Georgieva suggested Europe was better protected now.
“The French economy is growing,” she said. “And I think we need to remember that, [compared] to the previous time, we have a much more mature system in Europe. We have the strength of the European Central Bank. We have other instruments that Europe has developed to protect against financial stability risks.”
But she added: “Yet again, my message is — get your house in order.”
Asked whether the multi-billion-euro fiscal adjustment being proposed by the French government would be more difficult now against the backdrop of the student protests, Georgieva conceded that “it’s going to be tough, no question about it.”
She noted that since the Covid-19 pandemic, populations had become accustomed to governments “running to the rescue” of people and businesses when a shock occurs.
“As difficult as it is, there has to be active communication to explain to people why getting to a better place is actually in their interest, and I think we need more voices to speak about it, not only from government but also from trade unions, from the business community, to bring people together on a mission to improve the prospects for better economic future,” she said.
“Bond markets respond to fundamentals, and the fundamentals have changed,” she added. “Inflation is up, interest rates are up, government debt is high. Bond markets are looking for signal that the government borrowing is going to be contained, and we are encouraging governments please send the signal because otherwise we may we may see further climbs up.”