Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
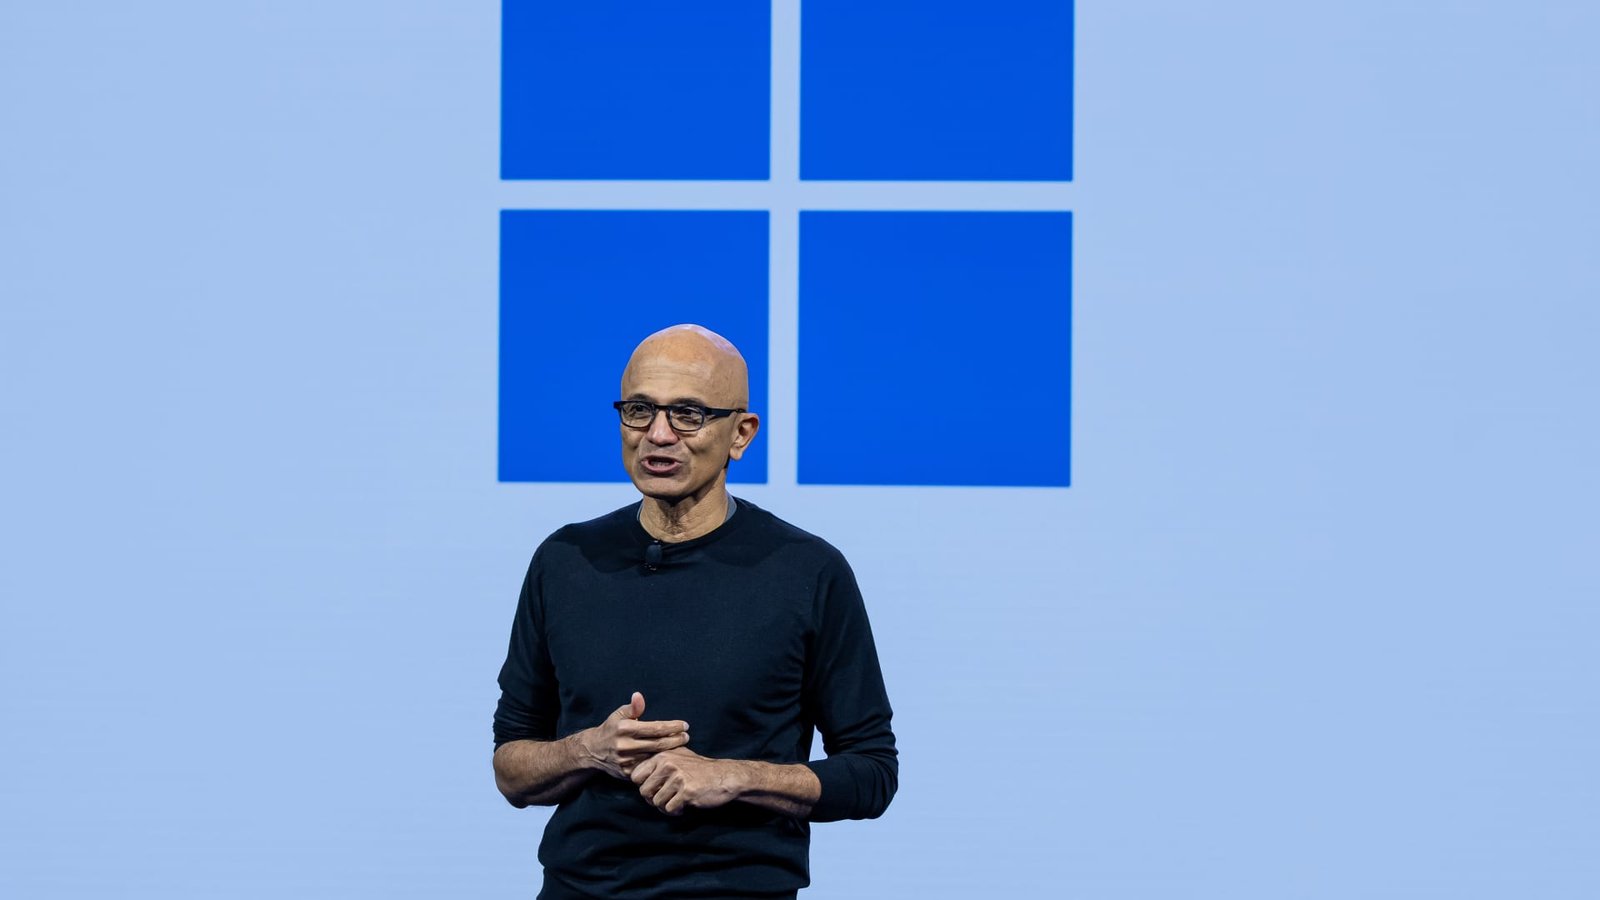
 LivestreamMenuMicrosoft has climbed back to record highs after a turbulent year for the tech giant’s stock. Those who held on should briefly enjoy the view — and then find lessons from the rocky ride to make money again in the future. Before Tuesday, it had been almost a year since Microsoft last closed at a record: Oct. 28, 2025, at $542.07 a share. The next evening, Microsoft signaled that its spending on artificial intelligence infrastructure would accelerate in the coming quarters, sending shares down about 3% in response. In that moment, it was impossible for investors to know what awaited them: a brutal, monthslong decline that saw shares lose more than one-third of their value, driven in part by some existential questions about the company’s future in an AI-first world. Fast forward to present, and like a phoenix rising from the ashes, Microsoft has rallied back to secure its first record close in nearly 12 months, ending Tuesday’s session at $543.45. Though it pulled back nearly 2% Wednesday in a terrible market, the journey here is no less remarkable. It’s easy to sit back and say, “Of course, we knew it would come back.” But victory laps aren’t what make you a better investor. On the other hand, a diligent study of the dynamics that got the stock back here can do that. There are lessons we can pull from this experience that we will carry forward with us. What went wrong This time last year, Microsoft was basically sitting on top of the world. It had a stake in OpenAI that seemed to get more valuable by the week . The AI infrastructure buildout wasn’t a political nightmare, and cloud unit Azure was growing consistently ahead of expectations. Then, the ground underneath Microsoft started to shift. On its fiscal 2026 first-quarter earnings call in October 2025, CFO Amy Hood said its capital expenditure growth rate in that fiscal year would exceed that of the prior year. Previously, Hood had signaled for a slowdown in capex growth. Shares fell 2.9% in that first session post-earnings. The reaction signaled that investors were growing increasingly concerned that revenue tied to the capex spending wasn’t showing up fast enough to be comfortable with the projected level of outlays. It didn’t help that over the 2025 holiday season, Anthropic’s Claude Code went viral on the back of the Opus 4.5 model release. This much-more capable version of the code-writing tool further brandished Anthropic’s frontier image. In the process, it made offerings like Microsoft’s Copilot AI assistant seem far less attractive and therefore monetizable than hoped for. The power of Claude Code — and its Claude Cowork productivity tool — also added fuel to concerns that AI would disrupt the software industry , giving rise to the “SaaSpocalypse.” The thinking was that companies could use these new coding tools to create bespoke applications internally; and even the packaged software that would survive might be threatened by AI if companies hire fewer human workers and, by extension, need fewer per-person software licenses. The fears around Microsoft’s standing were on display when the company reported earnings on Jan. 28 after the closing bell. The results demonstrated that Microsoft still needed to improve its “growth-to-spending” ratio, as we noted at the time. Put another way, Microsoft was spending too much in the minds of investors and not showing enough of a payoff quickly enough. With that earnings release, we also learned that 45% of Microsoft’s massive commercial backlog was from the profitless, cash-flow-negative OpenAI. That new disclosure didn’t help sentiment, either. Shares tumbled 10% the following session — its biggest one-day drop since falling nearly 15% on March 16, 2020, during the early days of the pandemic. To be sure, demand was not the issue. As we wrote at the time , “Microsoft has some issues to sort out to either get more Azure capacity online or to better balance capital expenditure growth to improve margins. The recent stock decline is disappointing, but we’re betting CEO Satya Nadella and CFO Amy Hood will figure it out.” However, sentiment around Microsoft would get worse. A key concern: the amount of Azure computing resources that Microsoft was committing to the internal development of Copilot, which, at this point, was being viewed as a total disappointment in the face of fierce competition. There was OpenAI and Anthropic, of course. But Microsoft looked even worse now that Alphabet had gone from black sheep to market darling, thanks to the release of Gemini 3 in late 2025. The revelation that Microsoft was holding back capacity — and in turn limiting Azure revenue — for a product that wasn’t even seriously in the AI conversation, made the spending concerns even more understandable. So, too, was the decline in the stock. As Melius Research analyst Ben Reitzes wrote in his Feb. 9, 2026, downgrade of Microsoft: “Due to things like Cowork from Anthropic, Microsoft’s powerful 365 suite could see challenges and may need to give Copilot away just to stay relevant — hurting growth and margins in its most profitable Productivity segment. This reality will consume internal capacity of Azure, limiting beats there too. … Azure’s lack of ability to beat is inextricably linked to Copilot. If Copilot adoption and capabilities are not up to par, Microsoft needs to spend more on AI modeling and R & D and whatever else consuming internal Azure capacity for themselves. We are increasingly realizing the folly in our logic only a few weeks ago — we were worried about Copilot woes, but overlooked it because we loved Azure’s prospects. If you think Copilot is a dud, it requires more investment in internal capacity since it will need to be given away. Voila – Azure can’t beat because Microsoft needs the capacity for themselves – period. The linkage of these 2 issues have thus killed the Azure narrative until proven otherwise.” Upstarts were encroaching on Microsoft’s enterprise software turf, and not only did the company not seem to have the horses to fend them off, but it was sacrificing revenue in the process of beefing up its defenses. While management could argue that was the right long-term move, we know Wall Street loves short-term thinking. Make no mistake, we certainly expressed our frustration with Microsoft’s performance throughout the spring, including after earnings in April , and into the summer. Jim Cramer was an especially vocal critic of Copilot, believing that the number of paid subscribers relative to those paying for Microsoft’s broader software suite was paltry. The company’s high-stakes Build conference in early June wasn’t enough to lift the stock, and that month would bring widespread carnage across the broader software stock universe. Microsoft’s low close of the year came on June 25 at $252.83 a share. Shares had started to perk up into July — and then came its fiscal fourth-quarter earnings report later in the month. That’s when many of issues plaguing the stock started to turn around. First off, the company didn’t raise its spending outlook. While that didn’t necessarily speak to any improvements with Copilot development, it made clear that investors had indeed likely overshot to the downside in a panic. Moreover, Microsoft was able to bring more Azure capacity online quicker than Wall Street had excepted. That it grew its commercial backlog with customers outside of the frontier labs — in effect reducing its reliance on the likes of OpenAI and Anthropic, though that remains material — also helped sentiment. Not for nothing, the number of paying Copilot subscribers increased to over 30 million from over 20 million in April. This is also right about the time that the highly levered Situational Awareness hedge fund started to blow up, alleviating some of the negative sentiment around software. The fund, run by a former OpenAI researcher, had been a huge proponent of the “short software, long hardware” trade. That was enough to help the stock get back to the $500s in early August, even as Copilot wasn’t fully figured out. Fast forward again, to late September, and we got the news that would ultimately help Microsoft reach a new all-time high. Microsoft launched a retooled version of Copilot and outlined a strategy focused on the corporate world it already dominates. Not long after, Reitzes upgraded Microsoft back to a buy rating , pointing to the overhauled Copilot strategy and emerging concerns about the reputation of the frontier labs. The lessons learned So, why did we stick with it? That’s the question that really matters now, as we look to pull a lesson from this past year of Microsoft price action. First off, we had faith in management. That’s not to say you should invest on hope, but it is to say that the team running a company is one of the most important factors to consider when it comes to single-stock investing. For Microsoft CEO Satya Nadella and CFO Amy Hood, their track records speak for themselves. Nadella, who took over the top job in 2014, brought Microsoft into the cloud computing and software-as-a-service era , while Hood has consistently proven herself to be one of the best CFOs in the game. Hood has been Microsoft’s finance chief since 2013. Second, we understood that while Microsoft was burning enormous amounts of capital to build more AI infrastructure, the spending was in its control. In other words, it was a self-inflicted “wound,” and not something more concerning like a deterioration in demand. As a result, we understood that if management decided it needed to pivot, they could do so until investors got more visibility into monetization opportunities. To put it simply, this was a high-quality company that needed to prove itself again, not a company that was lucky to be successful and was now seeing its luck run out. Under Nadella, Microsoft had faced disruption before and come out stronger on the other side, benefiting from the cloud-computing revolution and the embrace of the SaaS model. Some of Jim’s longstanding investment rules apply here too: Own the best of breed; it is worth it : Microsoft certainly fits the bill here for the reasons we laid out above. The management team is as good as it gets, and the company’s rock-solid balance sheet is a big advantage too. Nobody ever made a dime panicking : Plenty of investors were panicking about the “SaaSpocalypse” in the first half of this year. While perhaps not as acute in shares of Microsoft versus a name like Adobe , Figma and Intuit , as the move played out, it became increasingly clear that investors were starting to overreact about potential AI disruption for enterprise software companies. While some level of concern was justified because of elevated uncertainty, the panic likely meant the move was overshooting to the downside. That the market has become so algorithmically driven — and that so many names were being bucketed into sell orders thanks to “ETFization” — also didn’t help. For example, bad news out of ServiceNow didn’t mean everyone sold NOW stock, it meant plenty of people dumped their software exchange-traded funds. The most prominent example is the sold the iShares Expanded Tech-Software Sector ETF (IGV), which holds everything from pure-play enterprise software to cybersecurity, and yes, Microsoft (currently the third-biggest holding in the fund). Buy and homework, not buy and hold : Of course, acknowledging that there is panic in the air doesn’t mean you ignore it simply because you’re too cool for school. Sometimes, panic is warranted (like when the folks running the Federal Reserve “know nothing!” ) So, if you’re not going to panic, you better have a good reason and you only get that by doing the homework. In the case of Microsoft, it became clear that at least some of the capacity constraint was due to that internal desire to advance Copilot. If more compute had gone to external demand, Azure growth and overall revenue would’ve bene better. We didn’t like that that was the case, but it did mean that we were that much closer to better understanding the issue. Step one to fixing an issue, of course, is being able to identify it. With the problem better understood, we better understood what needed to be done. As such, Jim and others on Wall Street started to get more vocal about the need to turn Copilot around. When analysts and shareholders have identified a core issue they have, it’s harder for management to ignore and can therefore increase their sense of urgency in addressing the issue. Patience is a virtue — giving up on value is a sin : Ultimately, it all comes back to valuation. As we watched shares decline seemingly day after day, week after week, month after month, we never lost track of the price-to-earnings multiple. As Microsoft’s stock price declined, so too did its price-to-earnings multiple. This indicated to us that for all the concern being baked into the price, earnings estimates weren’t being cut nearly as fast. In fact, the estimates were largely going up, according to FactSet data. So, shares really were becoming much cheaper, making the potential reward if our faith in management was rightly given, that much greater. Microsoft started the year at roughly 28 times forward earnings. By late June, it had compressed all the way to 18. Bottom line As thrilled as we are that Microsoft has clawed its way back, and as much money was made on Microsoft, far more will be made in the years to come by understanding why this call worked out. By focusing on only best-of-breed names (with some exception, like when you spot an incredible turnaround opportunity), you give yourself the best chance of making money in the future. By then doing all you can eliminate emotion from your analysis — across the spectrum, from hope to panic — you can better ensure objectivity. Of course, it’s much easier to eliminate emotion when you are well-educated, so doing the homework is a non-negotiable. Finally, when you’ve done all that, you’ll know if you’re sitting on value or not. If you’ve got value, all there is to do is be patient. More often than not, if the analysis was correct, that patience will be rewarded, as it has been for us with Microsoft. Funny enough, without starting all over, we would argue a similar dynamic has played out with Meta in the past few weeks. And, in the interest of fairness, had we had a bit more patience with Alphabet, we would not have exited that name last year before it went on a huge run. Fortunately, we had enough awareness to acknowledge our mistake and get back in before it could climb even higher — underscoring a few other rules Jim has come to abide over his decades of experience: don’t dig in your heels when you’re wrong, swallow your pride. When the facts change, so too must your mind, or, at the very least, you must gut check your initial thesis. We did it with Alphabet, and while we missed last year’s monster run, we still managed to get back in in time to make money. Thankfully, with Microsoft, we never left. (Jim Cramer’s Charitable Trust is long MSFT, META, and GOOGL. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
Microsoft’s wild ride back to record highs in 1 chart — and the lessons learned
Our faith in the team of CEO Satya Nadella and CFO Amy Hood has paid off.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports