Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
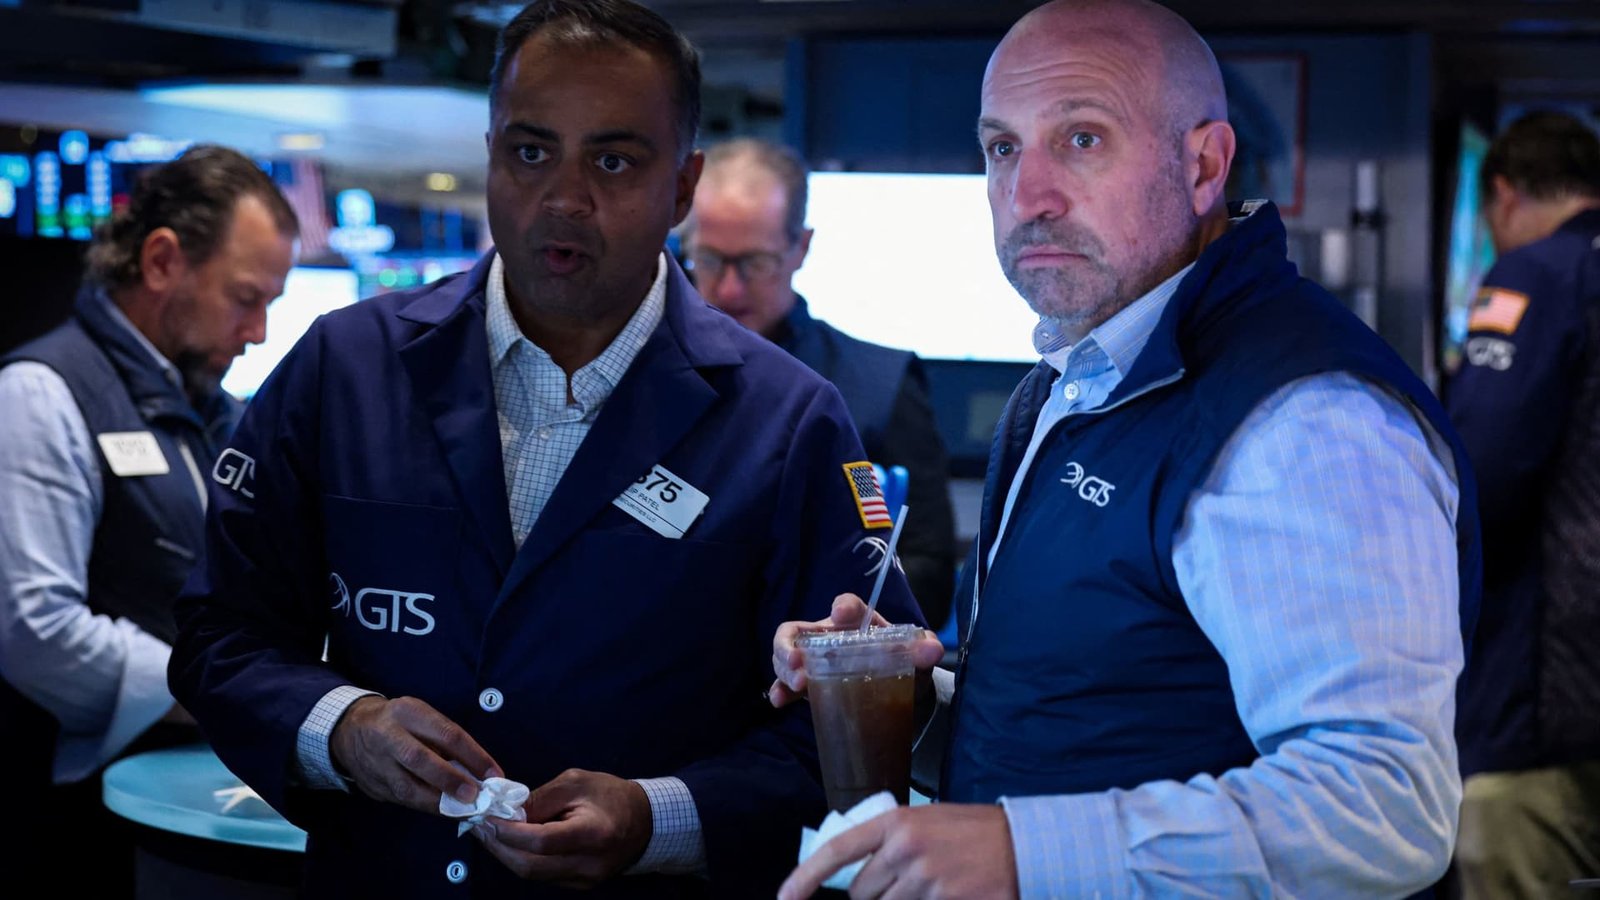
 LivestreamMenuSeptember lived up to its choppy reputation, with investors closing out the month with mixed performances. The S & P 500 and Dow Jones Industrial Average posted monthly declines, while the Nasdaq Composite rose for a second month. It was the third monthly pullback in four months for the S & P 500, while the Dow broke a five-month-long advance. Equities were volatile throughout September, with traders recalibrating monetary policy expectations seemingly day by day, as inflation showed little signs of easing and Treasury yields broke out to multiyear highs. Now comes October, another month with a bad rap. Indeed, some of the biggest monthly declines have taken place in October — including a 22% pullback in 1987 after the “Black Monday” crash — and a 17% plunge in 2008 during the global financial crisis. But October’s fraught reputation belies its typical strength. Data from the Stock Trader’s Almanac shows the S & P 500 averages a 0.7% gain in October, going back to 1976. The benchmark is also positive 60% of the time by the end of the month. The market’s October performance is even better in midterm election years. The S & P 500 averages a 2.4% advance in years with midterms, according to Citadel Securities. The Nasdaq-100 and Russell 2000 perform even better, averaging gains of 3.9% and 3.1%, respectively. To be sure, the market will have to clear several hurdles in order to march higher this month. Chief among them are sky-high Treasury yields. Ten-year note and 30-year bond yields are trading close to levels last seen in 2002. On top of that, the Federal Reserve is set to meet Oct. 27-28. While traders are now pricing in only a 37% chance of a rate hike, according to the CME Group’s FedWatch tool , those odds stood at nearly 70% just one week ago. Breadth isn’t looking too great, either. The S & P 500 ended September with 389 stocks lower for the month . “There is still plenty of stress beneath the surface,” Scott Rubner, head of equity and equity derivatives strategy at Citadel Securities, said in a note. “But positioning is cleaner, valuations are lower, earnings are returning and several of the market’s largest buyers have considerably more capacity to participate.” JPMorgan’s trading desk is also bullish to kick off October. “We now see a more favorable setup for markets as bond yields find a level and oil prices are likely to trend lower, albeit in a choppy fashion,” they said in a note.Read More
October by the numbers: A typically strong month with a scary reputation
Some of the biggest monthly declines have happened in October.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports