Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
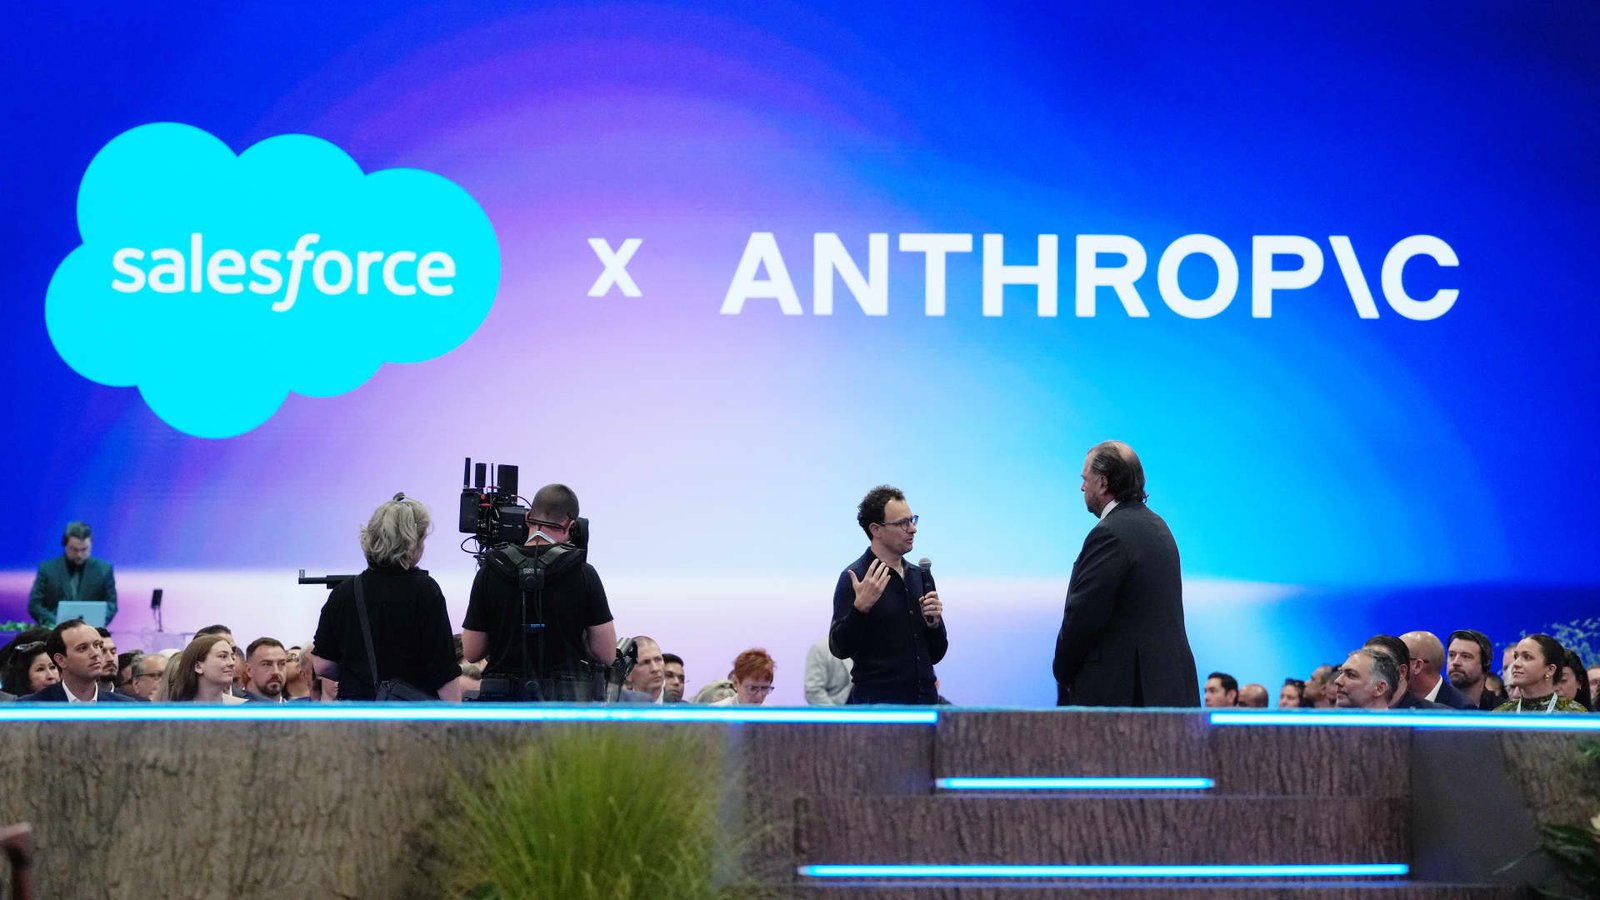
 LivestreamMenuThe “SaaSpocalypse” may be over, but so too may be a business model adored by Wall Street. That’s one of our big takeaways coming out of Salesforce’s influential Dreamforce conference this week in San Francisco, where the enterprise software giant detailed its plans to thrive in the evolving, AI-focused corporate landscape. The days of an application for “this” and another application for “that” are fading. However, the value of all the customer data stored within Salesforce’s apps is only increasing because it helps make AI systems like Anthropic’s Claude and OpenAI’s ChatGPT more useful. The company’s goal is to help clients maximize their data in the way that’s best for them. That no longer means being forced to log into Salesforce’s marketing, customer service, commerce and sales apps. Salesforce successfully figured out how to adapt its business for the AI era. Now, Wall Street just needs to figure out how to model it. For years, the seat-based business model was all the rage in the world of enterprise software — one person, one license, one fixed subscription price. With a low marginal cost of adding new seats, the software-as-a-service (SaaS) model was very lucrative for companies like Salesforce, and investors loved it. However, just as applications have been redesigned to be better used by autonomous AI systems called agents, rather than the humans prompting those agents, so too has Salesforce’s distribution and monetization strategy. The increased flexibility should help the company succeed over time. The flip side is that it also introduces a new level of uncertainty for Wall Street to model into financial projections — and that could influence how the stock trades in the medium term. Nevertheless, CEO Marc Benioff has demonstrated he’s worth betting on as this process plays out. He’s successfully pushed back on extreme predictions that AI was going to send every enterprise software stock to zero, as customers built their own bespoke applications and have fewer humans working for them. The “SaaSpocalypse” narrative started to quiet a bit this summer, and shares of Salesforce started acting better. Then came Salesforce’s earnings report on Aug. 26, which forcefully sent the bears packing and sent the company into Dreamforce with the wind at its back. CRM YTD mountain Salesforce’s year-to-date stock performance. At Dreamforce, the dominant theme was that the way that users interact with the Salesforce platform is changing, and Salesforce is wisely changing with them. Patrick Stokes, president of applications and marketing, laid this out during an investor presentation on Wednesday afternoon. The old way of grabbing information in a Salesforce app meant users had to 1) know where to look and 2) click through menus to load the information, synthesize the information, and figure out how to apply it. A salesperson or customer service rep would be repeating this process many times a day. They also needed to be trained (time and money) so they could learn where to look and what’s available. The new workflow amounts to a simple prompt and conversational dialogue with your agent, which is plugged into the Salesforce data ecosystem and, as a result, can interpret your prompt and do the legwork for you. The agent’s user interface may be Claude, Slack, ChatGPT, or Salesforce’s own Agentforce Coworker interface. Salesforce isn’t the only tool used by organizations each day. And that’s why an agentic-ready platform like what Salesforce has built and is now improving upon is so critical. Enterprise organizations are moving away from the old school — open an app, click through a million menus, and so on. Instead, they want tools that can be connected to and plugged into an agent and ready to accept prompts. Going this route, users can simply ask a question and leave it to the agent to figure out where the answers lie. This is the idea behind Salesforce’s Claudeforce partnership with Anthropic, announced alongside earnings in August, which allows all of the data, business logic, security, and permissions inside Salesforce’s traditional applications to be accessible through Claude. At Dreamforce, the company unveiled a broader “AIforce” that does the same thing for other platforms, including its own Slack messaging app and Agentforce Coworker. Here’s how Stokes put it: “It’s kind of aggregating software into one environment because no longer do I have to do a discrete task in Salesforce and then a discrete task in SAP, and a discrete task in Workday. I can if I have a task that requires all three of those systems… if they’re all in that Cowork environment, it’s now all aggregated and that agent can go off and kind of work and operate across those systems in ways that, frankly, we’ve been trying to build integrations for, for the last 50 years. And now we have this entirely new way to kind of drive these integrations. So, it’s a big, big revolution.” Of course, with any “big revolution” comes uncertainty. The market may now agree that enterprise software with the mission-critical, system-of-record nature of Salesforce is no longer going the way of the dinosaur. But while the “SaaSpocalypse” may be behind us, the exact pace of sales and earnings growth in this agentic, application-agnostic world remains a topic of debate. During the Wednesday investor presentation, chief executive Benioff said he’s been spending a lot of time meeting with customers and understanding their needs, particularly on pricing. His answer was quite insightful: “Every customer wants something slightly different on pricing. Some customers want per user pricing. It gives them predictability. They understand the cost structure. It makes sense to them. Some customers want per agent pricing. Some customers want consumption pricing. Some customers want usage pricing. Some customers want transaction-outcome pricing — that is, I’ve completed the transaction, therefore I’m paying for that. And some customers want business outcome pricing, which I have never seen before, but now they’re like, if you save me so much money, I’ll give you a percentage of that. If you make this much money, I’ll give you a percentage of that. No one majority of customers can you drop in any one of these buckets. So, what we’ve said to our entire sales organization is we are giving you ultimate flexibility to write the best deal for that customer.” We love that Salesforce has proven its ability to adapt the product to the new world, and it is applying that same level of flexibility to pricing. But herein lies the next chapter of the software debate. A change in how the company signs deals — with this much flexibility in possible terms — makes it that much harder for Wall Street analysts and investors to model out sales growth and the overall profit margin based on the sales mix. That means higher levels of uncertainty. Shares of Salesforce deserve to be up some 60% from their late June lows. Or, perhaps more accurately, they never deserved to be down in the low $150s with a forward price-to-earnings multiple of 10. But on the other side of Dreamforce, the question is where they go from here, at around $240 apiece and roughly 15 times earnings. Long term, we believe the answer is higher. We also recognize the new contract/revenue dynamics may well serve as an overhang until the Street has a better sense of what it means for the overall growth rate. Salesforce left its financial guidance unchanged at the investor presentation, including its fiscal 2030 revenue target of at least $63 billion. “Given all the innovation at CRM and the high customer interest we witnessed, we are not sure there are many investors left that would question the terminal value of the company,” analysts at Barclays wrote in a note to clients Thursday. They maintained their buy rating and $276 price target. “However, what is still debatable is the monetization and the share of value that CRM can capture in this new world. It will take time for a comprehensive answer here, which might limit how far shares can run in the short-term.” Analysts said they spoke to many customers who were “actually relatively happy with their seat-based model as it provided good visibility and has been a well-established vehicle to buy CRM’s solutions.” On the other hand, analysts at William Blair told clients they increasingly expect “consumption or outcome-based pricing to be most popular.” These two excerpts underscore the debate. This isn’t to say we have any intention of walking away. Indeed, we have faith management will adapt pricing successfully, just as it has the product. It is to say, however, that the “easy money” has probably been made. Getting shares back to the $300s likely depends more on management’s ability to explain what it’s seeing, over time, on customer preferences on pricing, than it does on its ability to convince the Street that Salesforce is a mission-critical application. Benioff has clearly done that successfully. Now it’s onto the next challenge. (Jim Cramer’s Charitable Trust is long CRM. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
The ‘SaaSpocalypse’ is over. How Salesforce now plans to thrive in an AI world
Investors are now focused on Salesforce’s evolving pricing strategy in the age of AI.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets news People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports