Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
 LivestreamMenu
- The third quarter was notably volatile, particularly for stocks and bonds.
- Despite Wall Street’s rally slowing, New York’s major averages outperformed a number of international rivals.
- Oil prices surged, while AI-linked equities saw a mixture of major gains and some losses.
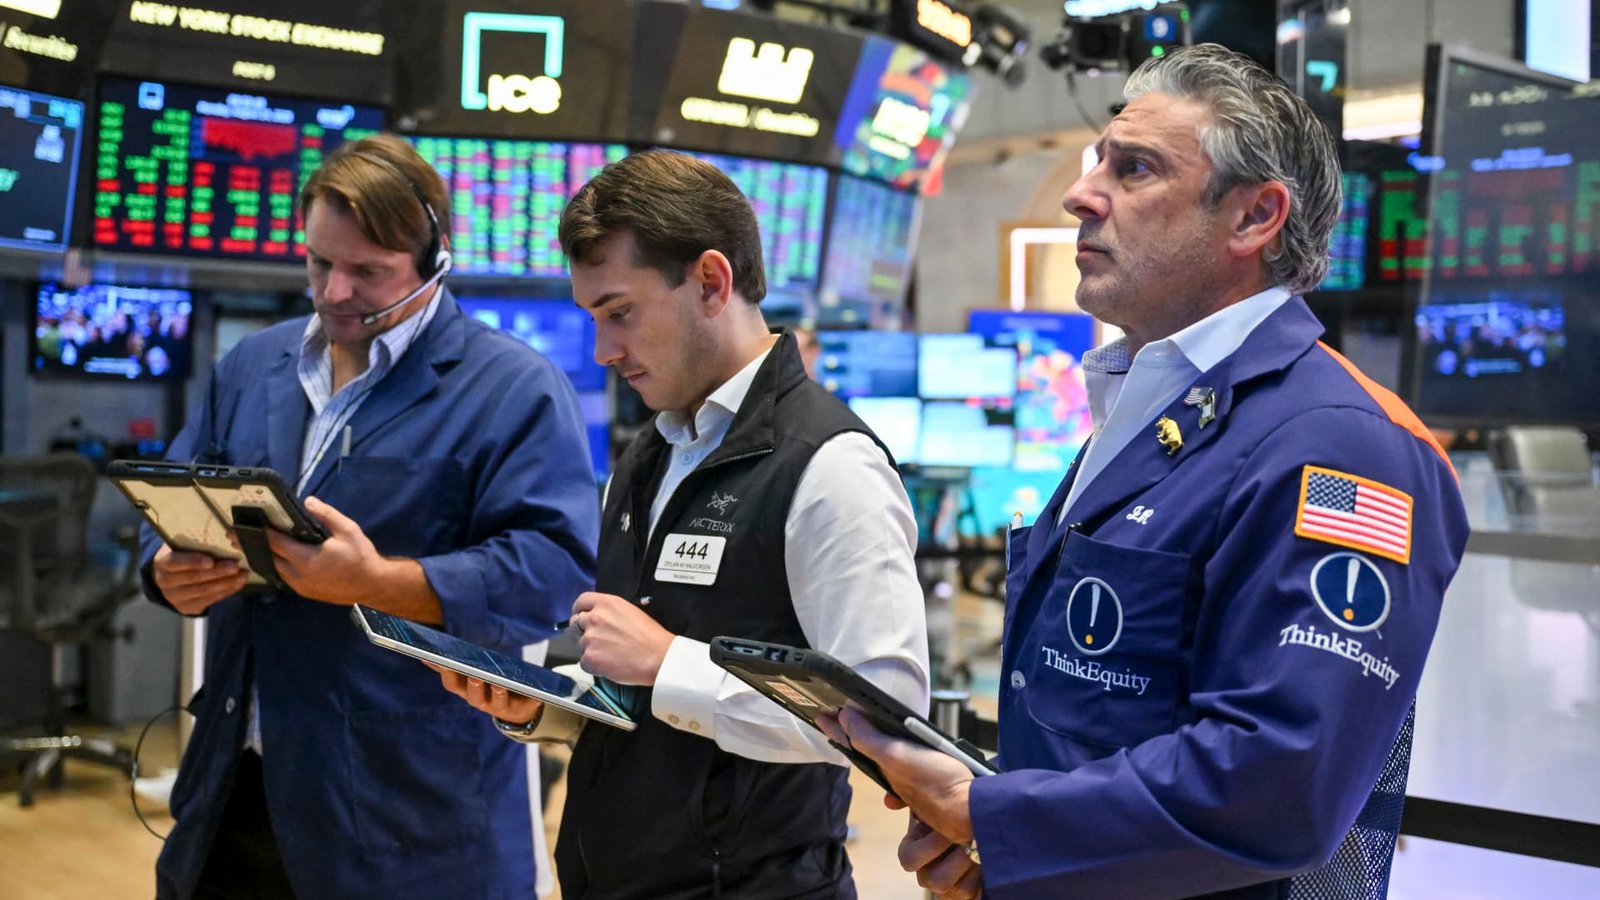
Traders work on the floor of the New York Stock Exchange (NYSE) during morning trading on Aug. 24, 2026 in New York City.Angela Weiss | AFP | Getty Images
The three months to September — the second full quarter of trading since the U.S. and Israel’s war with Iran started — brought more volatility for stocks.
Traders closely monitored headlines around developments in the Middle East, with the conflict lapsing into a standoff as U.S. President Donald Trump vowed to wreak “Economic D-Day” on Tehran and reportedly rejected an Iranian ceasefire proposal.
Stock rally falters
The Strait of Hormuz remained blocked, fueling fears for energy markets and of inflation, but equities broadly notched returns in the third quarter.
There was, however, a notable slowdown.
Wall Street’s major averages ended the third quarter in mixed territory. The S&P 500 index added 2.03%, while the Dow Jones Industrial Average fell 1.9% and the tech-heavy Nasdaq Composite ended the quarter 2.2% higher.
The average change across the three indexes was just 0.6%, marking a slowdown in the rally that saw double-digit gains in the previous quarter.
The slowdown was amid a pivot away from AI, with the sector experiencing bouts of turbulence. July saw routs driven by profit-taking following Samsung‘s record earnings and concerns about competition from China, while AI names saw volatility the following month amid concerns about financing and capital expenditure.
In September, AI and tech stocks struggled amid calls from prominent AI figures — including Anthropic chief Dario Amodei and OpenAI CEO Sam Altman — to slow down how fast the technology is developed amid safety concerns.
South Korea’s tech-heavy Kospi index shed almost 20% over the quarter, while the Philadelphia Semiconductor Index lost more than 11%.
AI heavyweights were also mixed. Nvidia shares gained more than 14%, and Microsoft surged 37.5% over the quarter, as both companies reported strong financials and robust demand, while Oracle and Broadcom both lost more than 6%. Meta stock surged almost 30%, as the company’s Muse AI personal agent was downloaded hundreds of thousands of times in the United States within weeks of launching.
Outside of the U.S., market performance was mixed. Major European indexes posted marginal gains. In Asia, South Korea’s tech-heavy Kospi fell 19.3%, while mainland China’s CSI 300 shed 12.5%, and Australia’s benchmark S&P/ASX 200 was flat.
Emerging markets were also mixed. The MSCI Emerging Markets index fell 1% in the three months ending September. MSCI indexes linked to Nigeria, Bulgaria, Colombia, Poland, Ukraine and Greece all posted double-digit gains.
Bullishness lingered, however, as AI and corporate earnings optimism outweighed headwinds for many investors.
In a Monday note, Mark Haefele, chief investment officer at UBS Global Wealth Management, said his team continues to hold a positive outlook on equities and is positioning for further market gains.
“Investors should consider combining a broadly diversified core equity allocation with targeted exposure to transformational innovation and cyclical opportunities, while reducing excessive dependence on individual stocks or a narrow group of technology companies,” he advised. “We continue to favor AI, power and resources, and longevity, and recommend broad exposure across sectors and regions.”
Bonds sell-off
Global government bonds were gripped by a sell-off in the third quarter, as a lack of diplomatic breakthroughs on ending the Iran war fueled bets on higher inflation and interest rate hikes.
As the bond market came under increasing pressure, yields on 10-year and 30-year Treasury notes hit their highest levels since 2007 and 2002, respectively. The U.S. has some of the highest government borrowing costs in the G7 group of advanced economies, with the benchmark 10-year Treasury yield holding above 5% and the 30-year yield trading above 5.5%
Bond yields and prices move in opposite directions.
Yields on bonds issued by other governments such as Japan, Germany, the U.K. and France also hit multi-decade highs.
In their weekly market commentary, BlackRock strategists said that market expectations for further Fed tightening may be overstated.
“The global bond selloff accelerated last week, pushing long-dated U.S. Treasury yields to their highest levels in over 20 years … on expectations for further rate hikes,” they said. “We think markets may be getting ahead of themselves. A hike that strengthens Fed credibility, against a backdrop of stronger growth, is in our view on net good news for risk assets.”
Oil above $100
The impasse in the Middle East reignited the oil rally.
In the three months to Sept. 30, front-month futures tied to global benchmark Brent crude oil soared 42% higher to $103.53 per barrel. It marked the contracts’ third-highest quarterly gain in the past decade, falling behind the first quarter of this year — when the Iran war broke out — and the height of the Covid-19 pandemic in 2020. Front-month futures tied to U.S. West Texas Intermediate crude oil rose 30.1% to $90.42 a barrel.
Stock Chart IconStock chart icon Crude oil futures
In a Sept. 28 note, analysts at TD Cowen said uncertainty around crude oil remains.
“We continue to believe the range of outcomes for this commodity are wider and more difficult to predict than others,” they said. “Once the conflict ends, and assuming normalized demand, the balances will be determined by if countries pump at prewar levels or max capacity … plus China buying patterns and Iran ability to sell into the market.”
Dollar holds onto gains
The U.S. dollar index was marginally higher by the end of the quarter, but held onto gains seen since the start of the Iran war.
At the end of September, the dollar index — which measures the greenback against a basket of major currency rivals — was trading at around 101.451, marking a 3% year-to-date rise.
Stock Chart IconStock chart iconU.S. dollar index
In 2025, a broad de-dollarization trend took hold as investors weighed the potential impact of Trump’s tariffs regime, with the dollar index shedding around 9% over the course of the year.
Matthew Ryan, head of market strategy at London-headquartered financial services firm Ebury, said in a note on Wednesday that rising global bond yields were continuing to drive investors to safe haven assets like the dollar.
“We still think that the move has perhaps gone a little bit too far, and we wouldn’t be at all surprised to see a mild correction in the coming days should oil prices, bond yields and risk sentiment stabilize,” he said.