Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
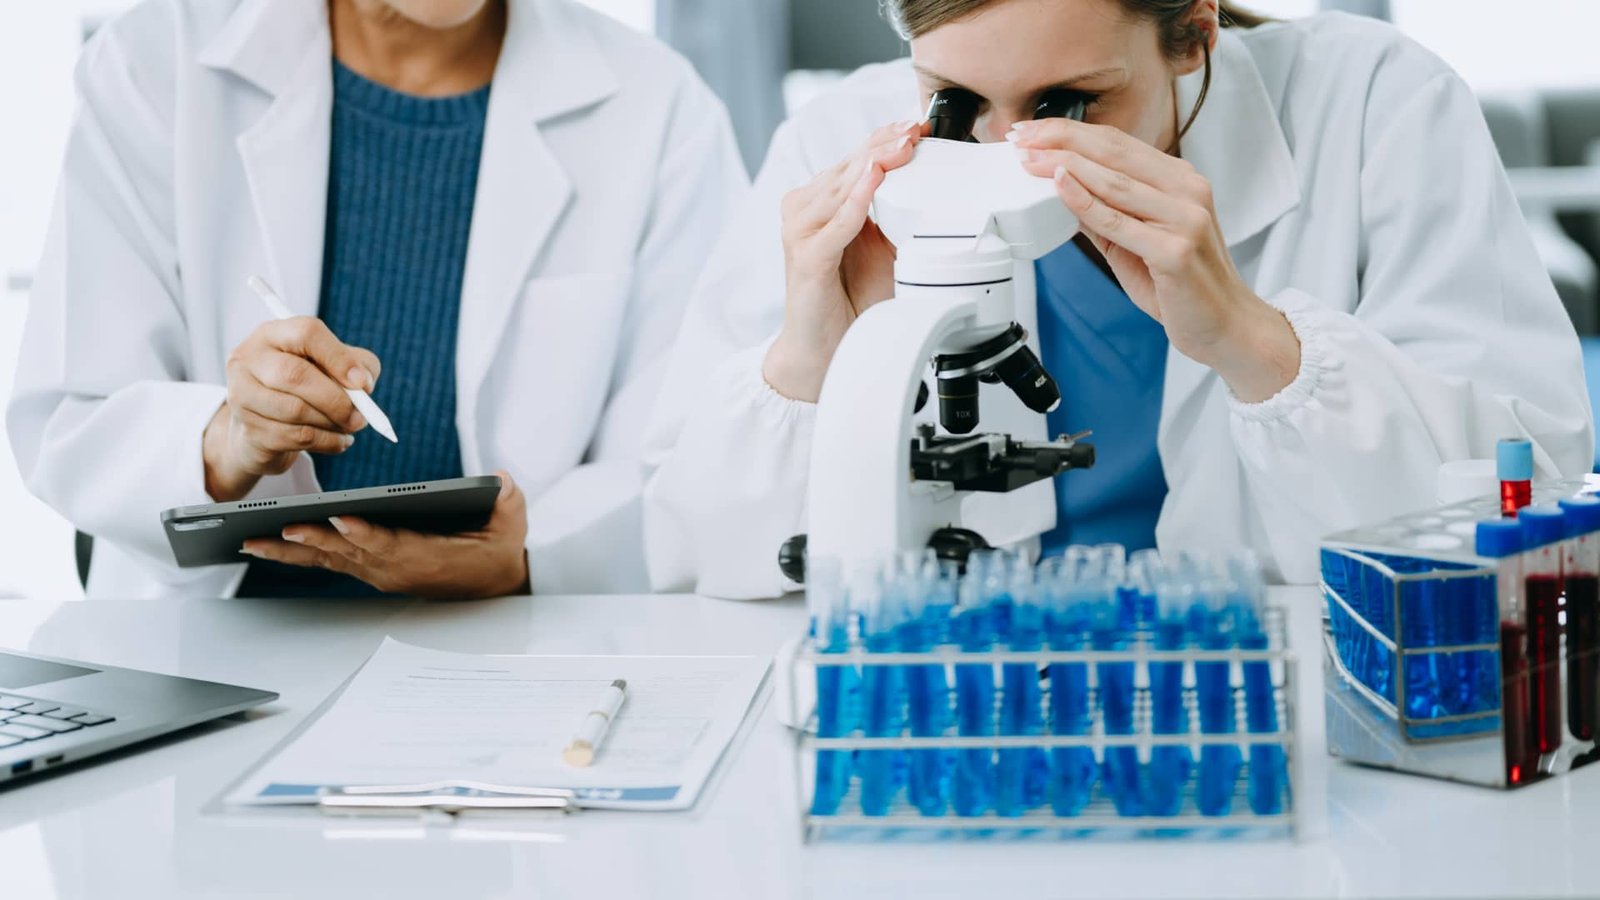
 LivestreamMenuKura Oncology ‘s growing cancer drug sales and promising pipeline could fuel a rally in its stock, according to JPMorgan. Analyst Priyanka Grover initiated coverage with an overweight rating and a year-end price target of $30, implying 180% upside to Wednesday’s close of $10.71. Shares were trading up about 1% on Thursday. The bullish call centers on Kura’s transition into a commercial-stage company after Komzifti received Food and Drug Administration approval in November 2025 for adults with acute myeloid leukemia carrying a NPM1 mutation whose cancer has returned or failed to respond to treatment. Early sales of the once-daily pill point to “aggressive physician adoption,” Grover wrote. Since Komzifti’s commercial launch, net product revenue has increased from $2.1 million in the final five weeks of 2025 to $9.1 million in the second quarter of 2026. JPMorgan sees an opportunity to expand its use to newly diagnosed patients, estimating roughly $1.5 billion in potential worldwide peak sales across those markets. Kura has “clear potential” to capture meaningful share of the leukemia market, JPMorgan said. KURA YTD mountain Kura Oncology’s YTD performance. Grover’s sum-of-the-parts analysis also weighs the potential of its experimental cancer drug, darlifarnib, which is designed to block specific tumor growth signals. JPMorgan estimates the drug could have $600 million in potential worldwide peak sales. JPMorgan said darlifarnib provides the San Diego-based company with “a potential second oncology franchise.” In an April data study, Kura Oncology said a combination of darlifarnib and cabozantinib, another targeted therapy to treat advanced cancers, “demonstrated robust antitumor activity.” Kura shares have “significant upside potential,” JPMorgan said, as clinical trials progress and the market better appreciates opportunities from both treatments.Read More
This biotech making precision medicines for cancer could nearly triple, says JPMorgan
Kura Oncology’s pipeline of drugs show promise for the biotech stock.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports