Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
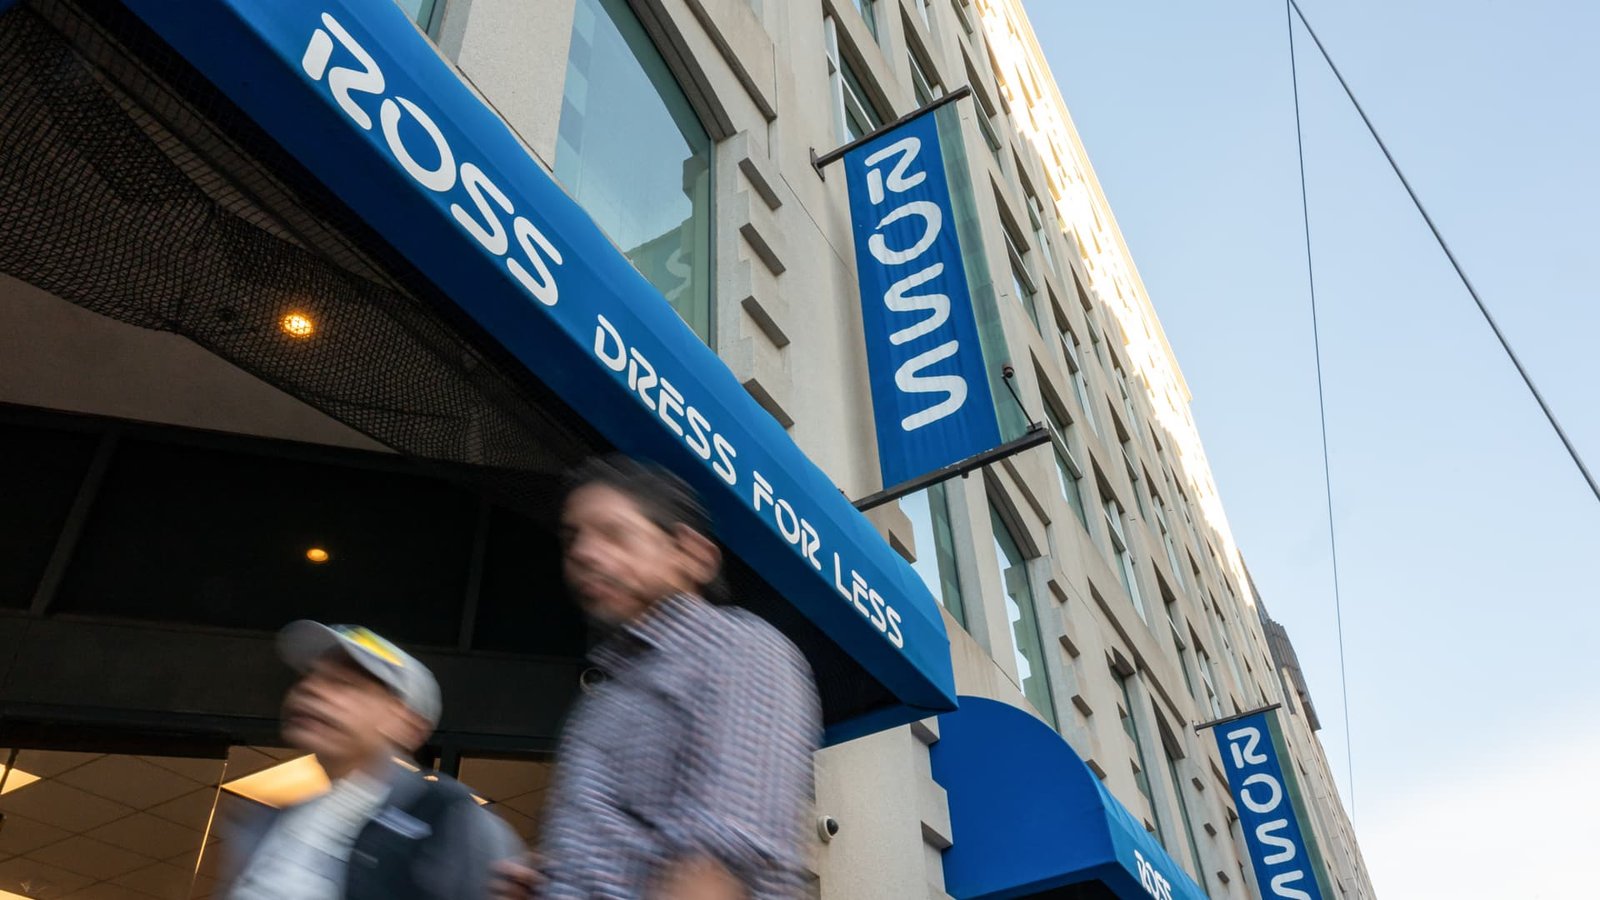
 LivestreamMenuRoss Stores is becoming more productive under new CEO James Conroy, which should help boost its stock, according to UBS. The investment bank upgraded the retailer to buy from neutral. It also raised its price target on shares to $315 from $239, implying 37% upside from Friday’s close. “The ROST pivotal question is if its recent same store sales growth momentum can persist beyond this year. …The answer is yes,” analyst Jay Sole said Monday in a note to clients. Ross has lagged TJ Maxx’s productivity by a wide margin, but changes in merchandising, marketing and improved in-store operations should help it close the gap, according to UBS. Conroy joined Ross Stores in February 2025. By the end of that year, Ross’ productivity rose 24% while that of its competitor jumped 44%, Sole said. “The market doesn’t appreciate how much ROST closing this gap will drive [same-store sales] growth in [fiscal year 2027] and beyond,” he said. As productivity improves, Ross should be able to grow its revenue at a compound annual growth rate of roughly 8.5% over the next two years, per UBS. That’s about 260 basis points above the Street’s consensus estimate for Ross’ revenue, according to the bank. UBS’ call falls in line with consensus on the Street. Of the 21 analysts covering Ross Stores, 14 have a buy or strong buy on the stock, while seven have a hold rating on it, LSEG data shows. Shares have fallen 4% over the past three months.Read More
This discount retailer is catching up to its main rival under its new CEO, UBS says
Ross Stores is likely to become more productive under its new CEO, which should give its shares room to run, per UBS.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News


Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports