Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
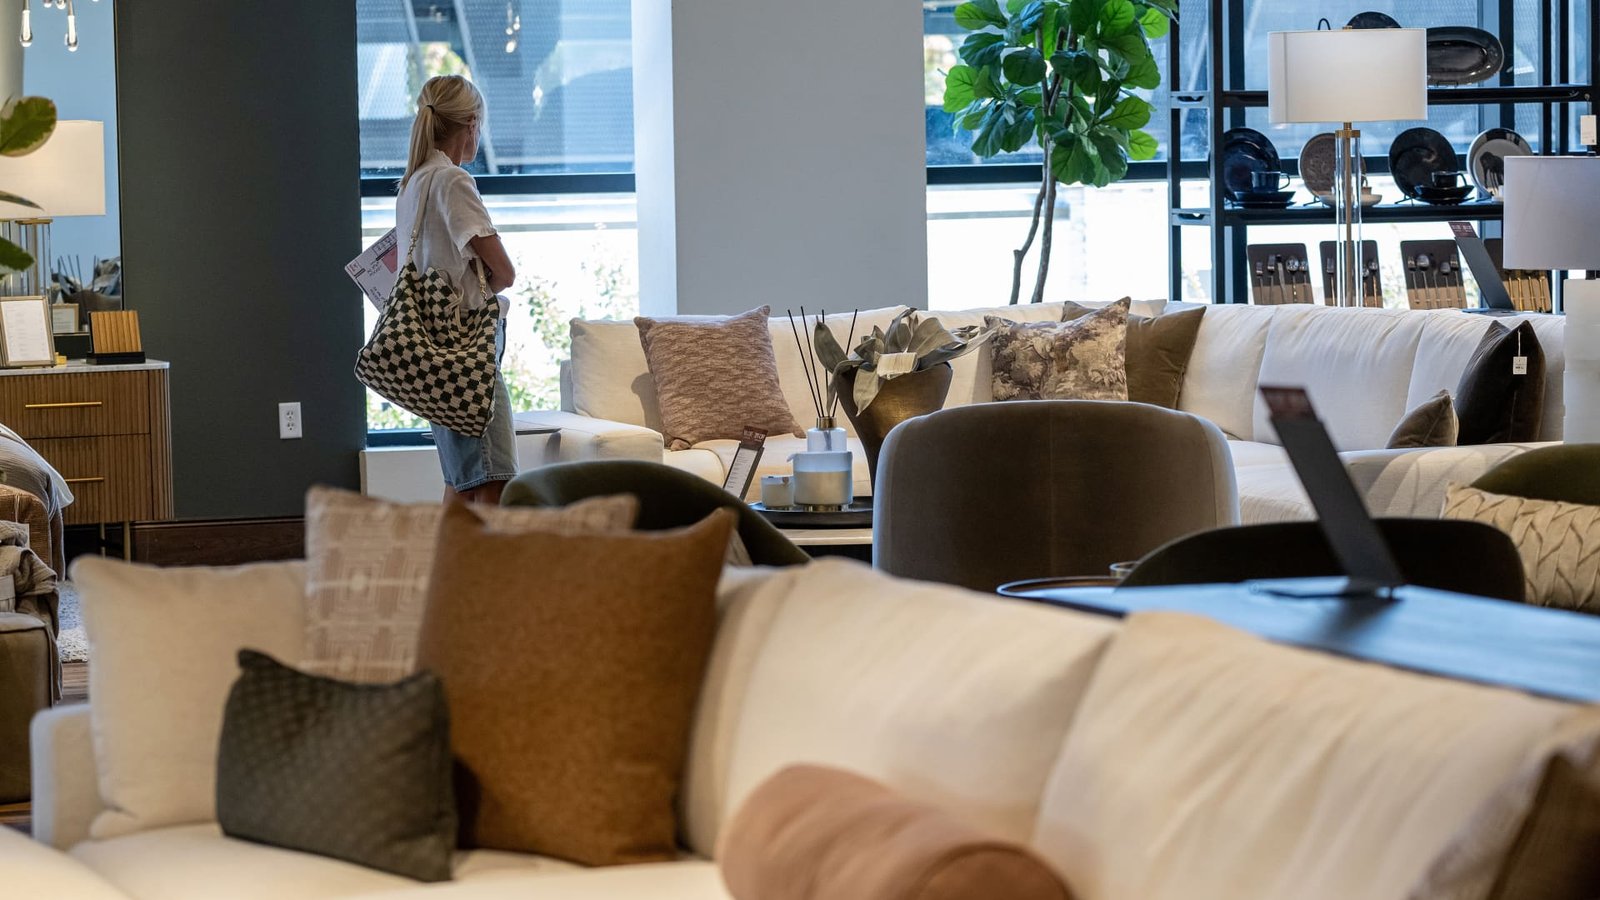
 LivestreamMenuArhaus is likely to break back in the green as it ramps up its digital marketing and other efforts to expand its customer base, according to Jefferies. The investment bank upgraded the home furnishings stock to buy from hold. It raised its price target on shares to $10 from $9.50, implying 28% upside from Friday’s close. “We upgrade ARHS to Buy with newfound optimism on the retailer’s strategy to elevate brand awareness via broadened catalog circulation & digital marketing,” analyst Jonathan Matuszewski said Monday in a note to clients. Shares of Arhaus have fallen nearly 31% year to date as macroeconomic and geopolitical issues have led consumers to tighten their purse strings and put pressure on margins. However, there are signs that the tide could be turning. ARHS YTD mountain Shares are down 31% in 2026. Over the past four weeks, Arhaus’ website traffic has more than doubled on a year-over-year basis, per Jefferies. And, sales seem poised to grow as the company expands circulation for its semi-annual catalog, the investment firm’s analyst noted. “Assuming modest conversion on new households receiving mailings, we see potential for a 75-200 [basis points] comp lift in ’27 from this initiative,” Matuszewski said. Arhaus is also in the early stages of a business-to-business strategy, which could drive even more value to its stock, according to Jefferies. “Our analysis of the [business-to-business] opportunity implies an annual comp tailwind of 150-200 [basis points], which we deem incremental to Street estimates,” Matuszewski wrote. Jefferies’ call goes against consensus on Wall Street. Of the 15 analysts covering Arhaus, seven have a buy or strong buy on the stock, while eight have a hold on it, LSEG data shows. Shares rose more than 6% following the upgrade.Read More
This struggling home furnishings stock is on the cusp of a comeback, Jefferies says
The investment bank upgraded the home furnishings stock to buy from hold.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets news People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports