Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
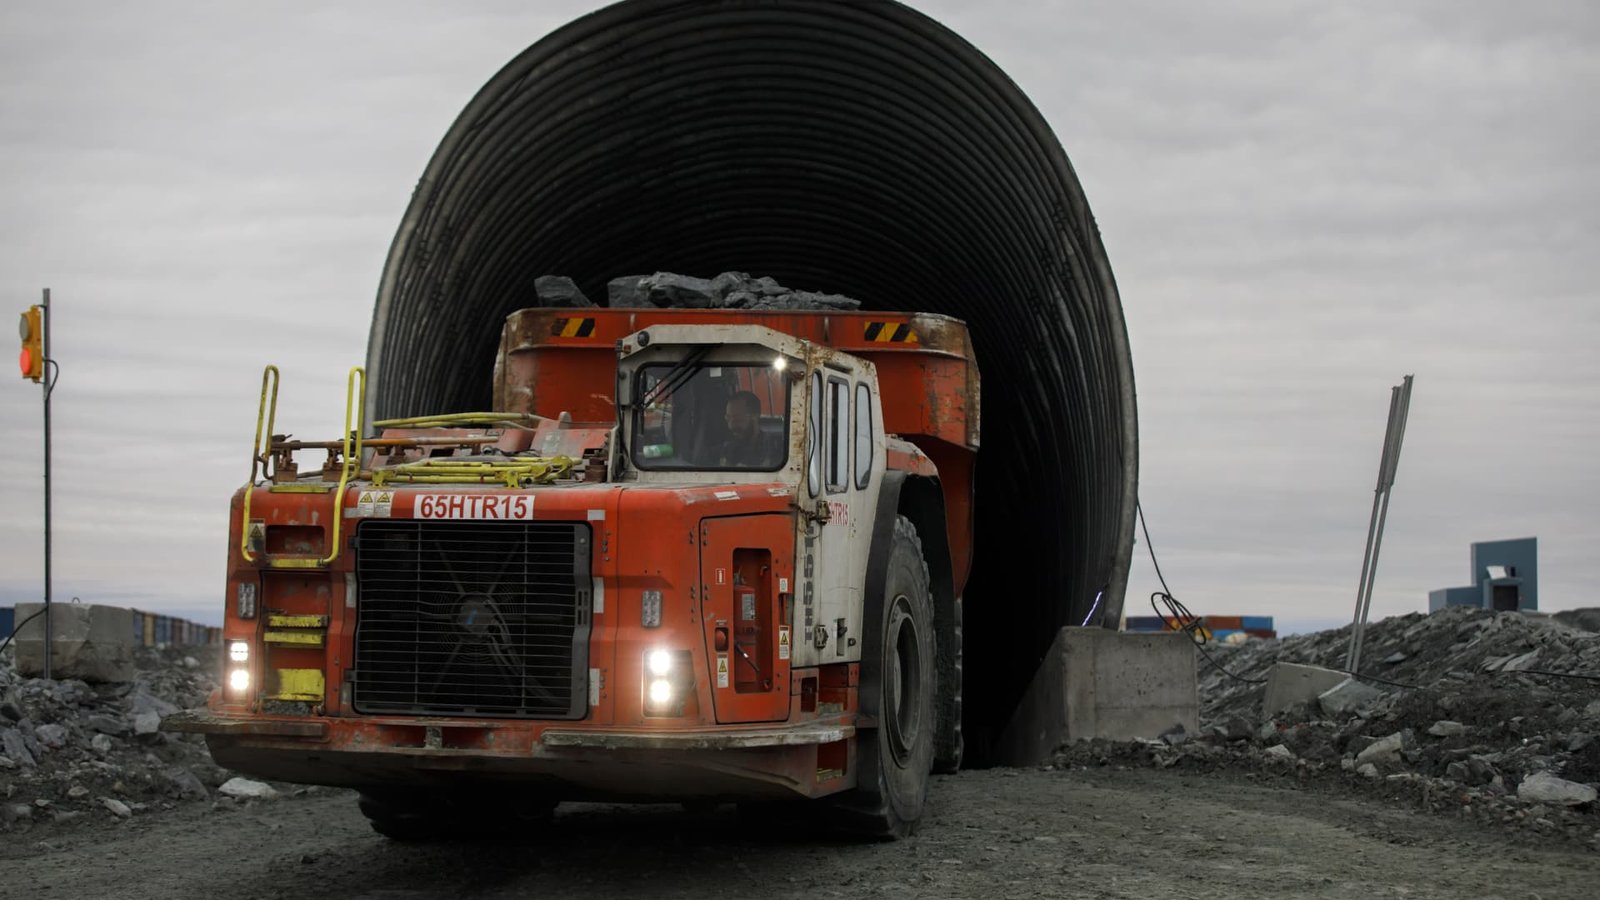
 LivestreamMenuI’ve been investing in gold and gold miners for 20 years, and one thing I’ve learned is that if you like gold, you should love a great gold miner. My favorite right now is Agnico Eagle Mines . Founded in 1957, Toronto-based Agnico Eagle has grown from a small Canadian silver mining business into the world’s second-largest gold producer . The company operates mines in Canada, Australia, Finland and Mexico, with the majority of its gold production coming from Canada. Key points Agnico Eagle remains highly profitable despite rising production costs. Strong cash flow allows the company to reward shareholders through dividends and buybacks. Central bank buying and limited gold supply support the long-term outlook. Gold has had an incredible run. During the two-year bull market that began in March 2024, gold rallied 164%, while gold miners surged 348%. Agnico Eagle did even better, gaining 382%. Mining stocks can amplify moves in the underlying metal. When gold prices rise, miners can benefit from higher selling prices and expanding profit margins, potentially delivering even bigger gains for shareholders. Why I’m buying Strong margins despite rising costs One key measure of a gold miner’s profitability is all-in sustaining costs (or AISC). That includes the cost of producing gold and maintaining existing mining operations. Agnico Eagle’s AISC rose to $1,648 an ounce in the third quarter, up from $1,331 a year earlier. Investors didn’t like the increase, and shares fell following the earnings report. But consider this: Agnico Eagle sold its gold for an average of $4,264 an ounce during the quarter. Even with higher production costs, there’s still a substantial gap between what it costs to produce gold and what the company gets for selling it. Costs could come down, too. If diesel prices fall, that could give a major boost to Agnico Eagle’s margins. Record cash flow is rewarding shareholders Agnico Eagle generated $852 million in free cash flow in the third quarter, giving it plenty of money to reward shareholders. Management expects to return more than half of its 2026 free cash flow through dividends and buybacks, assuming current gold prices and operating conditions hold. That’s a big part of the appeal for me. Unlike physical gold, which doesn’t pay investors anything while they hold it, Agnico Eagle offers the potential for both share-price gains and income. I think gold has more room to run Central banks around the world have been buying gold to diversify their reserves and reduce their reliance on traditional currencies and financial assets. I expect that demand to continue. Persistent government deficits and concerns about the purchasing power of fiat currencies also make gold attractive as a store of value. AEM YTD mountain Agnico Eagle Mines, YTD Then there’s supply. New gold mines take years to develop, and relatively few major projects are coming online. That makes it difficult for producers to quickly increase supply to meet demand. Why now? Gold and mining stocks have pulled back sharply from their highs earlier this year. Agnico Eagle has been hit particularly hard. As of November 2, shares were roughly one-third below their 52-week high. The stock also came under pressure following its latest earnings report, as investors focused on rising production costs. But I see the sell-off as an opportunity. Agnico Eagle is still generating substantial cash, and I believe the long-term outlook for gold remains favorable. Bottom line Gold miners can be volatile. If gold prices fall or operating costs remain elevated, Agnico Eagle’s margins and stock price could suffer. But I believe the company offers an attractive combination of profitability, shareholder returns and exposure to a gold market with strong long-term fundamentals. The recent pullback makes that opportunity even more compelling. Tim Seymour is the founder and CIO of Seymour Asset Management . He has over 28 years of investment experience as a hedge fund and portfolio manager, allocator and capital markets professional across multiple asset classes. Disclosures: Seymour owns with the firm. All opinions expressed by the [CNBC Pro contributors] are solely their opinions and do not reflect the opinions of CNBC, or its parent company or affiliates, and may have been previously disseminated by them on television, radio, internet or another medium. This content is provided as part of our editorial output for informational purposes only and does not constitute financial, investment, tax or legal advice or a recommendation to buy any security or other financial asset. The content is general in nature and does not reflect any individual’s unique personal circumstances. The above content might not be suitable for your particular circumstances. Before making any financial decisions, you should strongly consider seeking advice from your own financial or investment advisor. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET. THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL’S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR. Click here for the full disclaimer.Read More
This gold miner is a cash machine. Why I think the sell-off is an opportunity
Fast Money trader Tim Seymour makes the case for buying Agnico Eagle after its sharp pullback, pointing to strong profitability and continued demand for gold.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News

Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports