Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
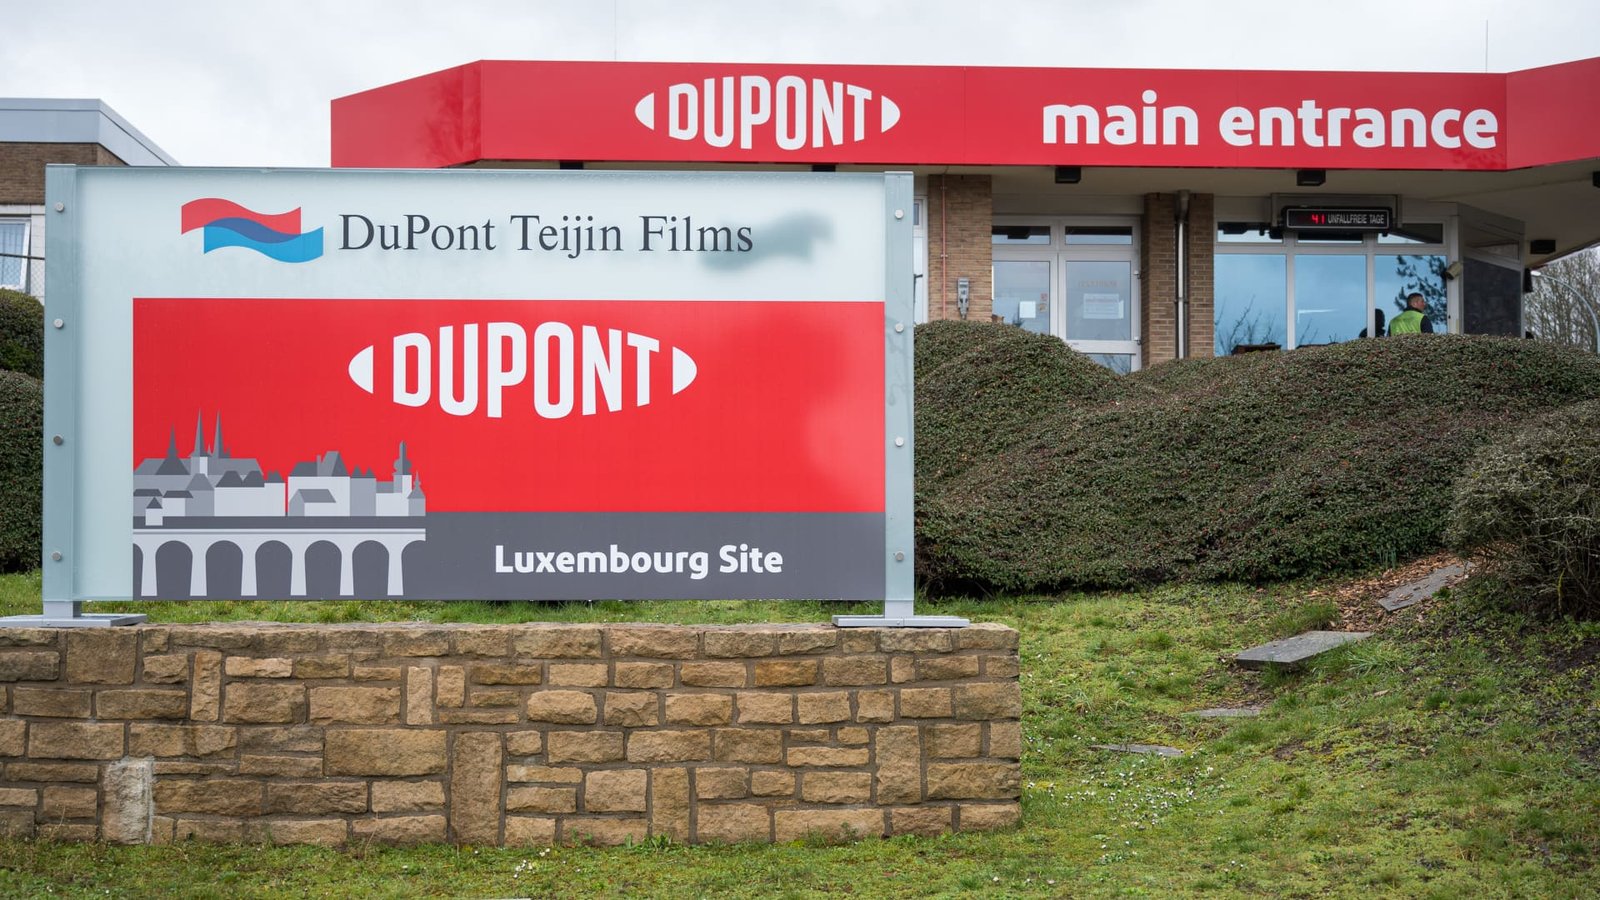
 LivestreamMenuDuPont shares surged more than 9% Tuesday after the specialty materials supplier reported strong quarterly results and issued upbeat guidance. We remain fans of the company, but are unsure what will propel the stock higher from here. Revenue in the third quarter rose 4.1% year over year to $1.87 billion, beating the LSEG consensus of $1.84 billion. Earnings per share (EPS) , excluding items, came in at $2.09, well above the $1.87 estimate, according to LSEG data. After normalizing for last year’s Qnity Electronics spin-off , adjusted EPS rose 31% year over year. Shares are on track to close at a record high for the first time since February. DD 1Y mountain DuPont 1-year stock performance Bottom line DuPont is navigating disruptions stemming from the Middle East conflict while demonstrating greater focus and profitability following the Qnity spinoff. Margins and earnings topped expectations, as did DuPont’s fourth-quarter earnings guidance. The company also boosted its full-year profit outlook. DuPont is seeing productivity improvements across the company and reducing costs in certain areas. Management said it has successfully raised prices with surcharges to offset higher incremental input costs stemming from the war. Something exciting to watch will be how DuPont’s embrace of artificial intelligence further boosts productivity and drives more sales. CEO Lori Koch said on the DuPont earnings call that AI agents have cut a front-end process from three months to “only five days.” The company is also using AI at its manufacturing plants to reduce maintenance costs; its sales and customer service teams are adopting the technology as well. The stock deserves to be up on these numbers. Still, we decided to lock in profits on Tuesday’s pop because we’re not sure what the next catalyst will be to drive the stock higher, and we’re wary of parabolic moves. The stock has felt stuck in no man’s land at times this year, so we want to take advantage in case the momentum that began in mid-October fades. We still have a small position to participate if the upside continues, and could buy more if shares retreat for reasons unrelated to the company’s performance. One big reason we like DuPont is that it adds diversification to our portfolio. In contrast to GE Vernova and Eaton — which reported a strong quarter of its own Tuesday — DuPont is an industrial company not heavily exposed to the data center buildout. DuPont benefits in some ways from the AI boom (more on that shortly), but most of its exposure to the theme disappeared with the Qnity spin-off a year ago. Qnity is all about semiconductor and consumer electronics manufacturing. The remaining DuPont sells materials for healthcare packaging, garments, and medical devices; water filtration and purification technology for clean drinking water and industrial applications, including semiconductor and pharmaceutical manufacturing; and specialized products and materials used in construction, automotive, and aerospace, among other industries. DuPont shares are up around 47% in the past 12 months, including Tuesday’s move. That’s well above a roughly 11% advance for both the S & P 500 and the index’s industrial sector. DuPont is seeing broad-based strength across its four defined end markets: healthcare, water, building technologies and industrial technologies. The water business was the only one that didn’t see mid-single-digit organic growth in the third quarter, and that can be chalked up to war-related headwinds in the Middle East. That’s a key market for DuPont’s desalination technology, which makes seawater safe to drink. Koch said DuPont now expects some large water projects planned for the second half of this year to be pushed out into 2027 — delaying about $15 million in sales. The upshot is that growth in other parts of the water portfolio is helping offset the impact in the Middle East, especially in semiconductors, which saw third-quarter growth “in the 20% range.” The chipmaking process requires water so pure that it’s unsafe for humans to drink in meaningful quantities, and DuPont’s ion-exchange technology is used to remove minerals and contaminants. Biopharma is another water end market where DuPont is performing well, and Koch mentioned that DuPont launched a new purification product in October targeting peptide manufacturing, which includes GLP-1 drugs. As we know from our Eli Lilly stake, this is a red-hot market. We’ll pay close attention to how this business performs in the coming quarters. DuPont’s aerospace business was another standout, boosting the Diversified Industrials segment (as seen in the chart above). Better yet, Koch said it was growing at a low double-digit clip, and she expects to see that kind of growth “for the foreseeable future,” thanks to a “quite sizable” backlog. DuPont’s materials are used both outside the plane cabin , such as in the engine to protect against heat and add durability, and within the cabin to make surfaces resistant to scratching and easy to clean. At present, Koch said that aerospace accounts for about 3% of DuPont’s sales. More generally, management offered a constructive, high-level outlook for 2027, even though official guidance won’t be provided until its fourth-quarter earnings report. “If we look at strictly an end-market perspective, generally 2027 feels similar to 2026, with the exception of we are not quite sure obviously what the Middle East does,” Koch said. One difference: the automotive business is expected to improve in 2027, moving from low-single-digit declines to slight gains. “Given that top-line algorithm and the productivity initiatives that we still have in place, and you would continue to expect us to be able to compound some margin expansion, on top of a top-line opportunity that’s pretty similar to this year,” Koch said. Finally, DuPont used its impressive cash generation to repurchase $350 million of its own shares during the quarter. That was across both an accelerated repurchase program and more traditional buyback activity. The company also expects to buy back $250 million in the fourth quarter. While we like management’s aggressiveness because it believes the stock is undervalued, we would also like to see DuPont make an acquisition to further lean into the healthcare and water end markets. That could be the upside catalyst we’re looking for. Koch said DuPont is looking at M & A opportunities and argued that it has the capacity to both repurchase shares and make a deal. “But we are not going to make a hasty decision and do a deal just to do a deal. We are going to make one that is right down the middle of the fairway, and you can see really good returns on our end,” she said. This is the push-pull of capital allocation. Right now, we trust and appreciate the diligence being shown by Koch and CFO Antonella Franzen. We’re reiterating our hold-equivalent 2 rating and keeping our price target of $165. Guidance Here’s DuPont’s revised full-year 2026 guidance: Net sales of approximately $7.19 billion (versus a previously reported range of $7.16 billion to $7.19 billion). Organic sales growth of 4.5% (up from the prior outlook of slightly above 4%). Operating EBITDA of roughly $1.785 billion (up from $1.75-$1.77 billion). Adjusted EPS in the range of $7.47 to $7.52 (versus $7.17 to $7.32 previously). Here’s the fourth-quarter guidance versus FactSet estimates: Net sales of roughly $1.825 billion, in line with the consensus of $1.824 billion. Organic sales growth of 8% Operating EBITDA of approximately $455 million, exceeding the $451 million expectation. Adjusted EPS in the range of $1.90 to $1.95, topping the $1.87 consensus. (Jim Cramer’s Charitable Trust is long DD, GEV, Q, ETN and LLY. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
Why we’re keeping a hold rating on DuPont despite its beat-and-raise quarter
The stock could beat its February record high close.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports