Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
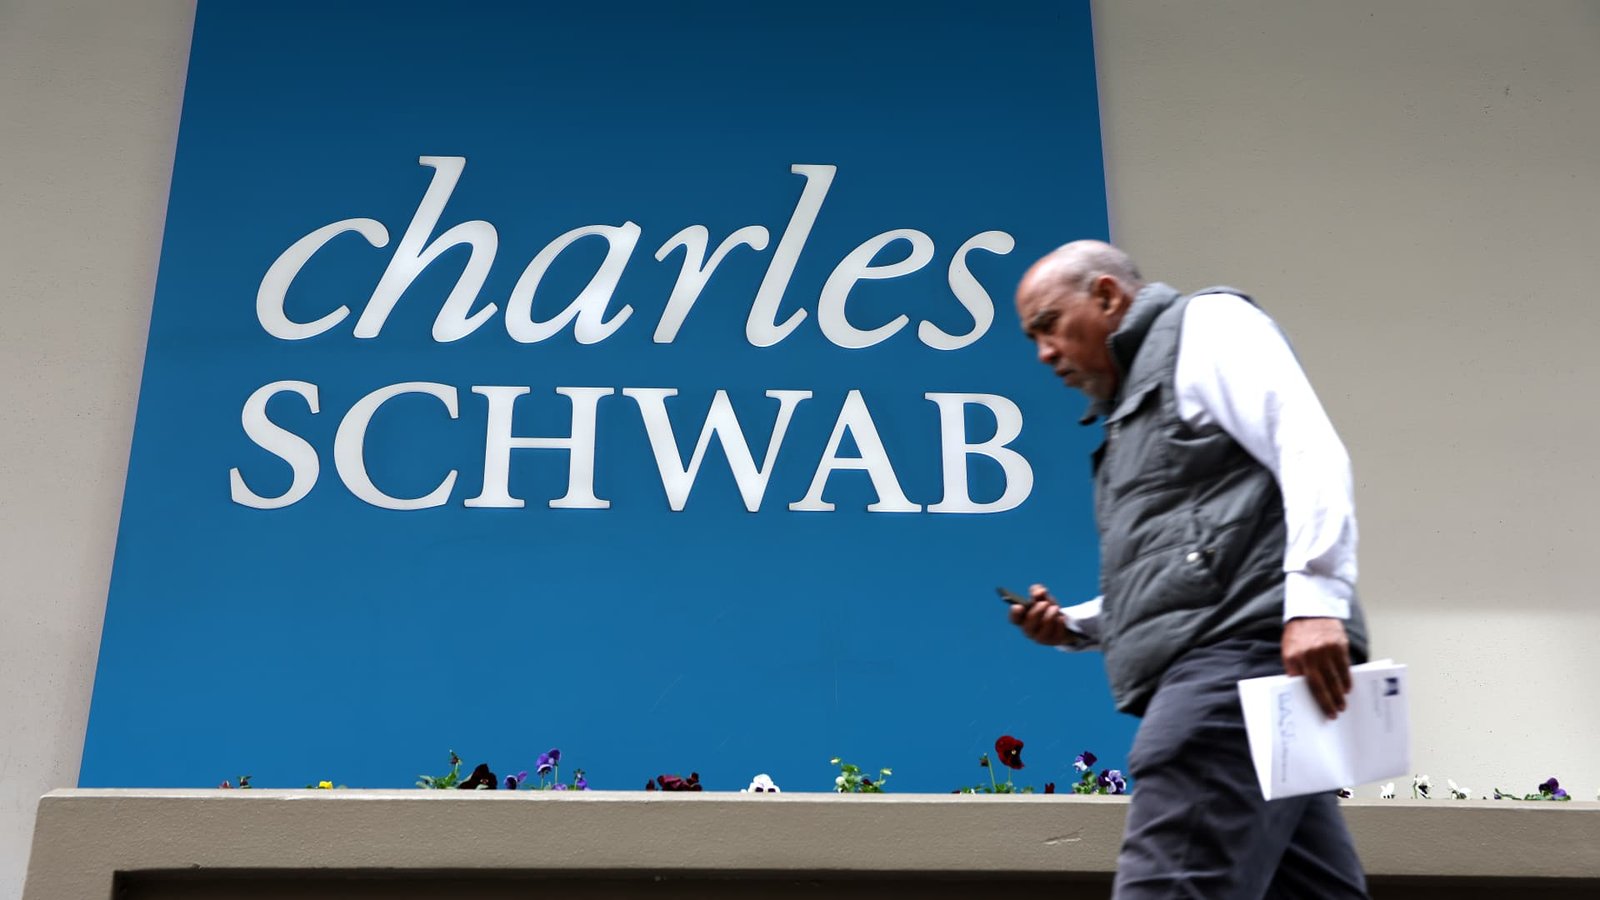
 LivestreamMenuWould you trust an AI agent with your bank account information and let it move your money without asking you first? Gerard Cassidy, a top banking analyst with nearly four decades in the business, frequently poses that question to clients, investors, and consumers. He told CNBC that nearly everyone gives the same answer. No. “It’s just too risky,” offered Cassidy of RBC Capital Markets. Still, it’s at the heart of growing concern on Wall Street over whether artificial intelligence could upend the banking industry. With the recent proliferation of agents and their ability to comparison shop for higher-yielding investments (just like buying a sweater), financial stocks have taken a hit. Agent-automation threatens one of the industry’s biggest advantages: customers who leave their money where it is because it takes too much time and effort to find better alternatives. The debate has taken center stage during the latest bank earnings season, with executives pushing back on the notion that AI agents could fundamentally change how consumers manage their money. AI agents are not supposed to be capable, yet, of independently moving deposits between banks. That’s a key distinction from AI-assisted shopping, where agents with prior authorization can complete purchases. While there have been some reports of agents accessing bank accounts, according to Axios and other media publications, the ability of agents to research financial products, run comparisons, and report back recommendations to their users has sent a chill through the financial industry. The prospect of AI-driven banking disruption kicked into high gear after Meta Platforms launched its wildly popular Muse personal agent on Sept. 8. Since then, shares of companies seen as vulnerable, such as Bank of America (down 18%), Wells Fargo (down 6%), JPMorgan Chase (down 5%), and Charles Schwab (down 14%), were sharply lower through Wednesday’s close. There are other reasons for the weakness in financial stocks, including the Federal Reserve’s September interest rate increase and questions about whether a prolonged hiking cycle awaits. But the threat of disruption in the air certainly never helps. ‘Trust, trust, and trust’ Veteran banking analyst Mike Mayo agreed with Cassidy, telling CNBC most consumers value the convenience and security of their existing banking relationships more than earning slightly higher returns. “I’m very strongly in the camp that the risk should be taken seriously, but it’s exaggerated,” argued Mayo of Wells Fargo. “The three most important words in banking are trust, trust, and trust.” A survey from Deloitte underscores that reluctance. It found that 72% of bank customers hesitate to share their financial information with generative AI tools, while just 49% trust the accuracy of AI-generated banking information, compared with 79% who trust information from bank websites. Charles Schwab CEO Rick Wurster said relatively few clients are attempting to access their accounts through unauthorized AI agents. “While people love AI and they’re using it heavily, they’re not ready to turn their financial life over to AI,” Wurster told CNBC in a post-earnings interview. Wells Fargo CEO Charlie Scharf pointed out that customers have long been able to move their money into higher-yielding accounts with just a few clicks, yet many choose to stay put. “The idea that that’s going to contribute to mass movement to higher-rate alternatives I think is completely overdone, especially for the time period we can see,” Scharf said on the bank’s third-quarter earnings call. The potential threat to bank profits, however, is real. Banks make money partly by collecting deposits and lending or investing those funds at higher rates. If AI agents make customers more willing to move their savings, banks could be forced to pay more interest to keep that money, squeezing their profits. Not all accounts would be equally vulnerable. Analysts said checking accounts are more insulated because they are tied to everyday payments, while savings accounts, where customers are more focused on earning higher yields, could face greater competition. For investors, rising deposit costs or slowing deposit growth would be warning signs that AI agents are beginning to disrupt the industry. But third-quarter earnings showed no clear evidence of such a shift. “I don’t plan on changing my earnings estimates anytime soon due to the AI agent threat on bank deposits,” said Mayo, who has been covering banks for 30 years. JPMorgan CEO Jamie Dimon said the bank is blocking external agents that rely on customers sharing their login credentials. “We’re not going to allow just any outside agents to come in inside the company because it’s just too risky for clients and for JPMorgan,” Dimon said during the bank’s earnings call. Cassidy raised another unresolved issue: who would be responsible if an authorized AI agent mistakenly transferred money to the wrong account and the funds couldn’t be recovered? Unlike credit card fraud, where established consumer protections exist, responsibility for mistakes made by autonomous agents remains unclear. Bank of America CEO Brian Moynihan similarly emphasized the need for customer authorization. “We strongly believe there should be a human in the loop to authorize money moving out of your account,” he told CNBC . Banks are not sitting still To be sure, banks aren’t sitting out on the technology. Schwab recently launched its own AI assistant named Charley, while JPMorgan began a targeted pilot for its own AI tool called Smart Cash, which aims to predict a user’s cash flow and move funds to maximize yield. Analysts see opportunities for AI to boost employee productivity, strengthen fraud prevention, personalize financial products and reduce costs. Those benefits could help offset any longer-term pressure on profits from increased competition for deposits. “Banks are AI beneficiaries, not AI roadkill,” Mayo said. He also sees parallels to previous technological advances, including online banking and fintech, which have made moving money easier without triggering the widespread disruption some investors feared. “I’ve seen this movie over the last three decades, and it has never played out the way the dire concern predicted,” he said. “I think this time will be no different.” (Jim Cramer’s Charitable Trust is long GS, WFC. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
AI agents could disrupt bank deposits. Why Wall Street may be overreacting
Analysts say the fears that AI agents could disrupt the banking industry are overblown, for now.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports