Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
 LivestreamMenuBroadridge’s core franchise is difficult to displace, with its governance and technology systems deeply embedded across financial institutions, making switching complex. Tokenization is creating more business for Broadridge, not less. Broadridge is already participating in the transition to tokenization through products such as its distributed ledger repo platform, which processed roughly $360 billion of tokenized collateral per day in September. Artificial intelligence has so far looked more like a productivity tool than a direct threat to Broadridge’s business. At roughly 16.4 times forward earnings, the stock trades well below its five-year average despite posting 8% recurring-revenue growth and 12% adjusted earnings growth in fiscal 2026. Broadridge Financial Solutions operates behind many of the routine functions that allow financial markets to work. It distributes proxy materials and processes shareholder votes, while its technology is used by large financial institutions for trade processing, books and records, settlement and other back-office functions. Those businesses have historically produced steady recurring revenue and earnings growth, but Broadridge shares have fallen 20% in 2026 as investors have questioned whether new technologies could make some of that infrastructure less valuable. While artificial intelligence and tokenization are changing how financial institutions operate, Broadridge’s existing business remains deeply embedded in the financial system. AI is beginning to automate portions of Broadridge’s own operations, raising the possibility that more of its operational work can be automated. At the same time, the early development of tokenized markets is creating new technology needs for the banks, brokers and other institutions the company already serves. Together, those developments make technological change less of a threat to Broadridge than investors currently assume and, in parts of the business, is a source of growth. Governance moat Broadridge’s governance business is built around a structural feature of the U.S. equity market: most individual investors do not appear directly on the shareholder register of the companies they own. Instead, shares are generally held in “street name” through a brokerage firm or other intermediary. When companies need to communicate with investors or conduct a shareholder vote, those beneficial owners still have to be reached. Broadridge handles much of that process. It distributes proxy materials, collects voting instructions and reports the results through the system. In fiscal 2026, the company processed communications for more than a billion equity positions. That scale would be difficult for a new competitor to reproduce. Broadridge is connected to issuers, broker-dealers, custodians and investors across the market, and the service has to work accurately across all of them. Regulation adds another layer. Broker-dealers are required to forward proxy materials to beneficial owners, while much of the reimbursement framework is governed by industry rules rather than freely negotiated by Broadridge. Its technology business also operates in heavily regulated areas. Financial institutions use Broadridge for functions including trade processing, books and records, settlement and collateral management. Broker-dealers face detailed requirements around maintaining and preserving those records, including when third parties perform the work. Replacing one of these systems therefore involves more than selecting new software. Financial institutions also have to ensure that a new platform continues to satisfy regulatory and operational requirements. Implementation can also be lengthy because the systems touch multiple parts of a financial institution. That doesn’t make Broadridge immune from competition, but it makes switching more complicated than replacing a typical enterprise software product. Tokenization demand Tokenization could eventually alter some of those existing workflows. In a more fully on-chain financial system, ownership might be recorded directly on a blockchain, some corporate actions could become automated and shareholders could potentially vote through digital infrastructure. That could simplify some functions Broadridge performs today. The current tokenized-equities market, however, looks quite different. Ondo Finance CEO Ian De Bode said that, as of October, roughly 90% of the tokenized-stock market was structured as notes backed by shares held within the traditional financial system. When Ondo’s token holders want to vote, the company collects their voting preferences and casts the corresponding votes through Broadridge. That is how most tokenized stocks work. They are not shares originally issued on a blockchain. Instead, an issuer holds the underlying stock within the traditional financial system and creates a blockchain-based instrument backed by those shares. The token changes how the investor holds or transfers the exposure, but the underlying security remains within existing brokerage or custody infrastructure. Voting shows why that matters. A tokenized note may not directly carry the voting rights associated with the underlying share. But the issuer can collect a token holder’s voting preference and then exercise the corresponding vote using the shares it owns, and the channel it uses to do so is the same one every other beneficial owner uses. For now, tokenization therefore still intersects with much of the existing financial infrastructure. That is likely to remain important as financial institutions begin adopting the technology. Banks already operate extensive systems for client accounts, trading, custody, settlement, books and records and compliance. Adding tokenized assets introduces another set of technology that has to work alongside those systems. Traditional and tokenized markets are likely to coexist for years. A hybrid market The shift to tokenization is unlikely to happen all at once. For years, financial institutions may have to operate across both traditional and blockchain-based systems, with some securities held and settled through existing infrastructure while others increasingly move on-chain. That hybrid environment creates its own set of problems. Banks and brokers still need to reconcile ownership records, accounts, collateral and corporate actions across different systems, while issuers still need to know who owns their securities and who is entitled to vote or receive distributions. That could work in Broadridge’s favor. Much of its existing business is built around connecting institutions and reconciling complex financial-market infrastructure. Rather than eliminating that need immediately, tokenization may initially add another layer that has to be integrated with the systems already in place. Broadridge’s existing institutional relationships give it a head start as customers adopt tokenized technology. Its distributed ledger repo platform , or DLR, is an early example.nagement expects activity to increase as clients already signed onto the platform finish implementation and move more volume onto it. Broadridge is also developing tokenization capabilities beyond repo through its broader DLX platform. Those businesses are still small compared with Broadridge overall, so tokenization is not yet a major earnings driver. But DLR provides evidence that institutions are already willing to pay Broadridge for products built around distributed-ledger technology. Tokenization also feeds the governance business. Broadridge’s investor-communications revenue is influenced by the number of investment positions requiring communications and voting services. New investment products and easier market access have historically contributed to growth in those positions. Tokenized equities broaden access to U.S. securities, particularly among international investors using cryptocurrency-based platforms. Not every tokenized asset will translate into additional revenue for Broadridge. But broader participation in financial markets expands the number of positions and ownership structures requiring investor communications. That gives Broadridge several ways to participate as tokenization develops. AI: Productivity tool or threat? AI creates a different question for Broadridge. Banks may increasingly use AI to automate operational work they previously outsourced. Broadridge, however, is also deploying the technology within its own managed-services business. Its agentic AI tools are being used for tasks including investigating trade breaks, resolving exceptions and automating other repetitive operational work, and management has cited meaningful productivity improvements from those deployments. If Broadridge can perform the same work with less manual intervention, AI reduces the cost of providing some services. How much of those savings ultimately remains with Broadridge rather than being passed back to clients remains an open question. But AI doesn’t eliminate the need for the underlying systems. While an AI application may help identify why a trade failed, a financial institution still needs records showing what was traded, which account owns the position and how the transaction should settle. That infrastructure remains central to Broadridge’s business. The setup Broadridge’s stock weakness hasn’t been driven entirely by technological concerns. New contract signings weakened for several quarters as some larger platform deals took longer to close. Because those contracts can take more than a year to convert into recurring revenue, investors closely watch closed sales as an indicator of future growth. Fiscal fourth-quarter results improved considerably, with Broadridge reporting a record $158 million of closed sales. Broadridge faces a difficult comparison when it reports its first-quarter results on Tuesday because the year-ago period included unusually high event-driven proxy revenue. That could make near-term growth look weaker even if the underlying recurring business remains healthy. BR YTD mountain Broadridge Financial Services shares year to date The stock trades at roughly 16.4 times consensus fiscal 2027 earnings, compared with a five-year average closer to 22 times. Fiscal 2026 recurring revenue increased 8% and adjusted earnings per share rose 12%. The investment case doesn’t require tokenization to become a major contributor immediately, nor does it depend on AI dramatically changing Broadridge’s margins. The core business continues to generate recurring revenue and earnings while both opportunities develop. There are still risks. The biggest are execution, client concentration and the pace at which newer businesses become financially meaningful. Broadridge ended fiscal 2026 with a record fourth quarter for closed sales, but one strong quarter doesn’t establish a trend, and large platform deals can take 12 to 24 months to implement. Sustaining bookings and converting the backlog into recurring revenue will be important to watch. The company’s technology platforms are also deeply embedded with large financial institutions, which supports high retention but means the loss of a major client could hurt revenue faster than a new win can offset it. And while DLR already processes hundreds of billions of dollars of tokenized collateral each day, tokenization remains a very small contributor to Broadridge’s overall revenue, so the upside could take years to become meaningful to earnings. For now, however, traditional and tokenized infrastructure are developing alongside one another, and Broadridge is participating in both. With the stock trading at a substantial discount to its historical patterns even as its core business continues to grow, investors don’t need to assume a large contribution from tokenization or AI for the valuation to look attractive. Instead, both provide additional upside if Broadridge continues to capture the transition. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET. THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL’S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR. Click here for the full disclaimer.Read More
Broadridge runs Wall Street’s market plumbing. Tokenization may expand its role
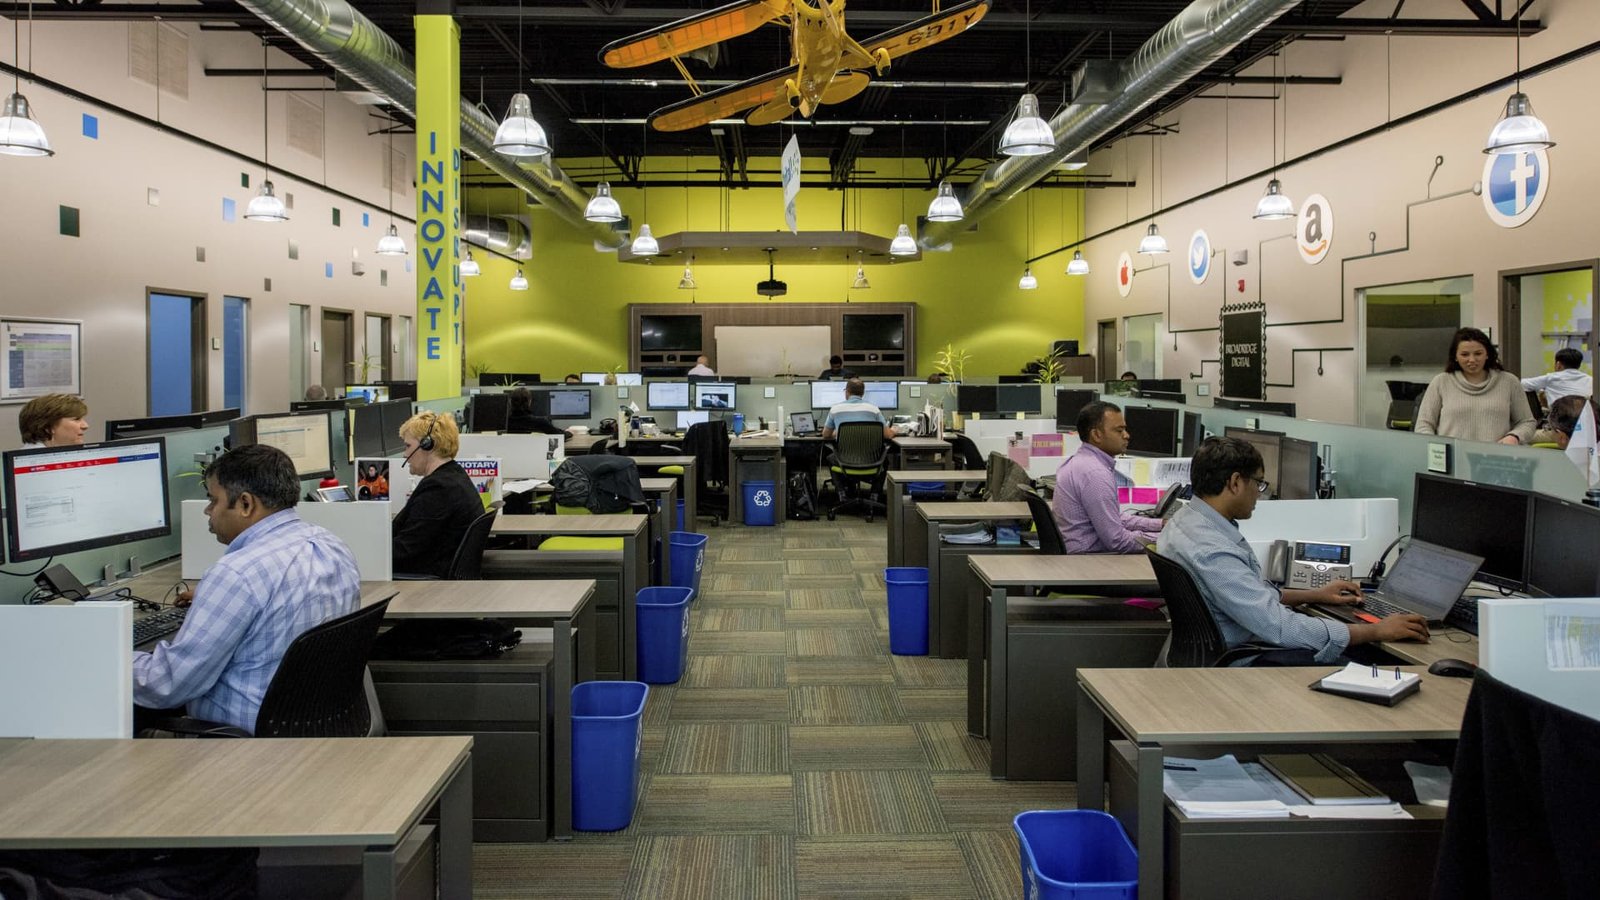
Broadridge’s business is deeply embedded in the financial system, but some investors have viewed AI and tokenization as a threat.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports