Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
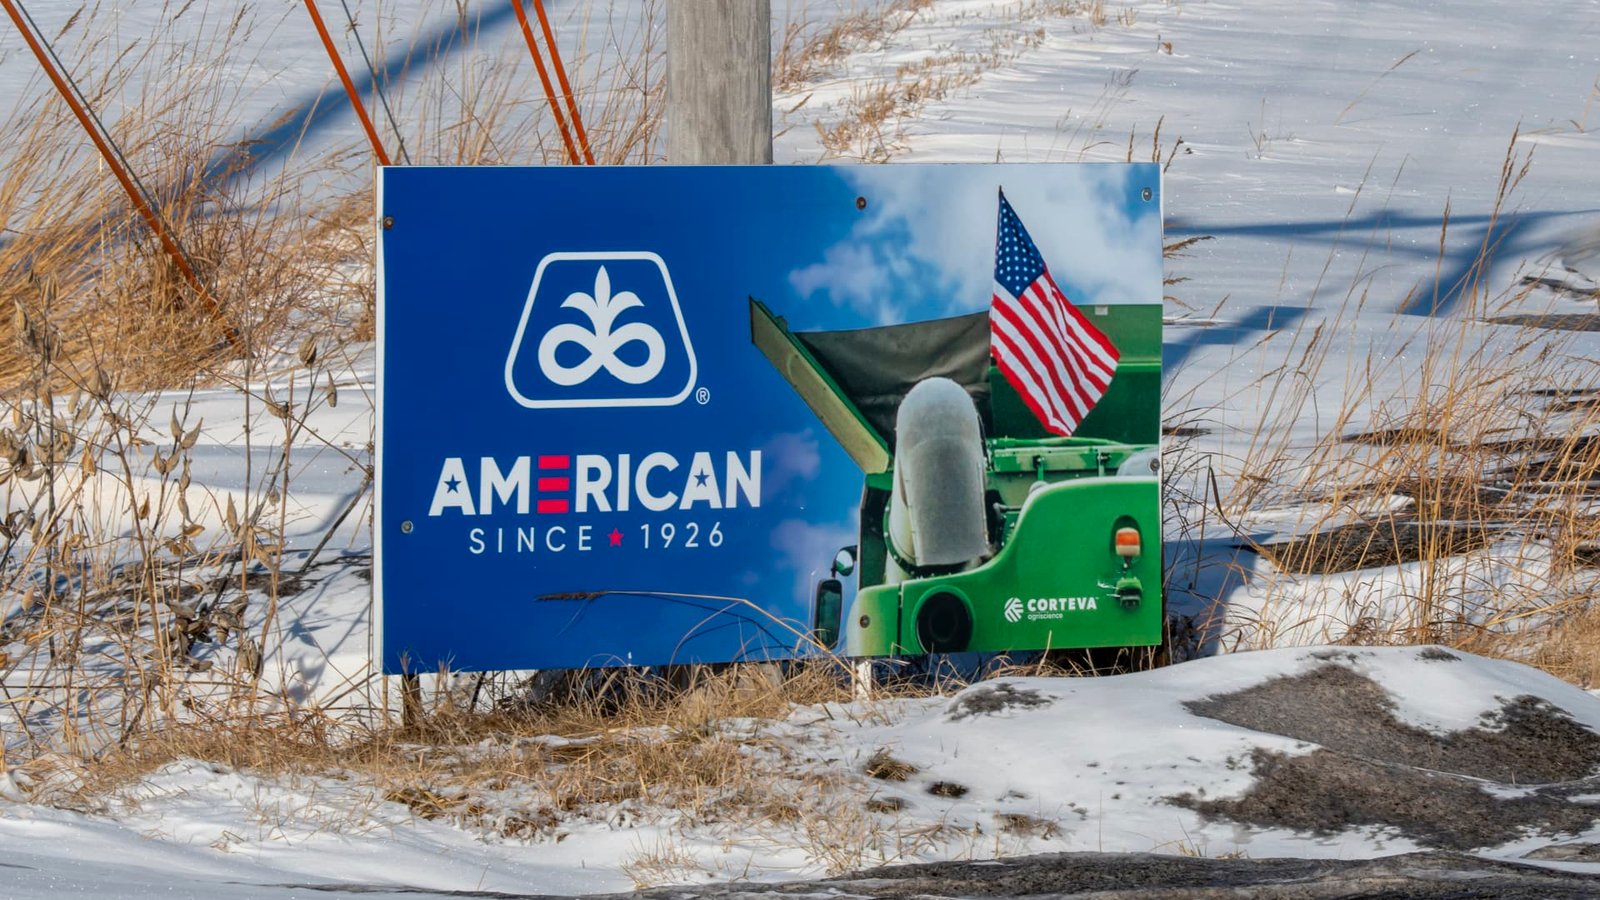
 LivestreamMenuCorteva is bound to move higher as it focuses more on its crop chemical business, according to JPMorgan. The investment bank upgraded the stock to overweight from neutral. It has a $19 price target on shares, implying 53% upside from Monday’s close. Earlier this month, Corteva spun out its seed business into Vylor, with the aim of prioritizing its agricultural chemical business. It’s a move that should lead the firm’s shares higher, according to JPMorgan. “Corteva is the cast off: and we think it is undervalued at the current price,” Jeffrey Zekauskas said Tuesday in a note to clients. “The direction of the company is to in-license new crop chemical molecules from other industry participants. These molecules tend to have good growth profiles and above-average margins.” The analyst added that Corteva is likely to power through some of its legal liabilities, including a lawsuit over its use of so-called forever chemicals in its formulations . He also noted that several price trends in the agricultural commodities market should support Corteva’s share growth. “The crop chemical industry has been characterized by negative price trends over the past three years as corn prices moved lower from above $6.00/bu to about $4.00/bu,” Zekauskas wrote. “Corn prices are now near $5/bu, creating an opportunity for neutral to positive pricing in 2027, which we have not built into our model.” JPMorgan’s call falls in line with consensus on the Street. Of the 23 analysts covering Corteva, 15 have a buy or strong buy on the stock, LSEG data shows. Shares of Corteva have fallen 6% over the past month, partially due to its spinout and ongoing legal issues, but the stock is still up 23% year to date.Read More
Corteva just underwent a big spinoff. JPMorgan says the agriculture stock is now poised for big gains
The investment bank upgraded the stock to overweight from neutral.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports