Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
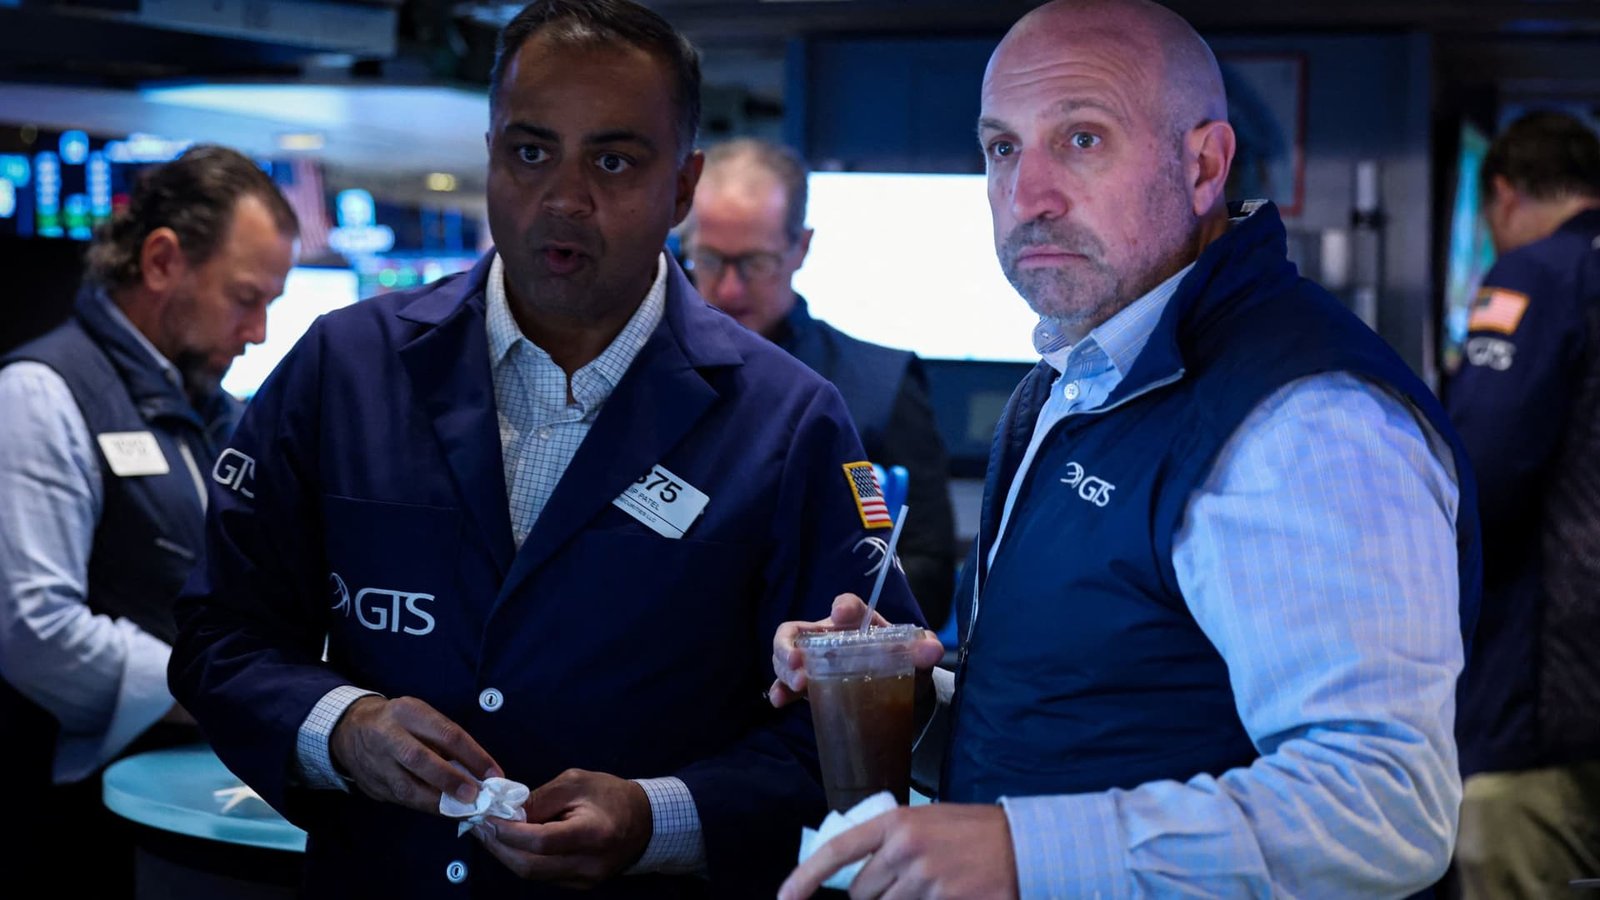
 LivestreamMenuWill earnings actually help the stock market overcome the threat of higher oil and yields? Many investors hope the third-quarter earnings season will do exactly that as it ramps up next week, with the big banks reporting results. Citigroup , Goldman Sachs , Wells Fargo , JPMorgan Chase are set to report Tuesday. Morgan Stanley and Bank of America report Wednesday, as does asset manager BlackRock . Banks are expected to post an earnings growth rate of roughly 10%, in line with how they’ve done historically, according to FactSet data. But more important than the results may be what the bank leaders themselves have to say about the current quarter. Specifically, any commentary they have on the state of the consumer or lending activity in an economy beset by higher oil and yields. “As much visibility as they can provide will help either calm market fears or heighten them,” said Brian Leonard, portfolio manager of Keeley Gabelli Small Cap Dividend Fund (KSDIX) . Any positive commentary out of companies this earnings season could help lift the S & P 500 , which rallied to all-time highs just this week before a sharp escalation in yields brought it back down. Both the 10-year and 30-year U.S. Treasury yields rose to their highest levels going back to 2002 this week. As of Friday afternoon, the major averages were on pace for a winning week. The Dow Jones Industrial Average was up almost 1%, while the S & P 500 was higher by 1.1%, each on track for their second positive week in three. The Nasdaq Composite was on pace to gain 0.6%, heading for its fourth positive week in a row. Earnings strength Earnings have been a major reason why investors have managed to stay optimistic in the current market, even in the face of alarming headlines. According to FactSet’s John Butters, the broader index is expected to post earnings growth of 29.6% in the third quarter, a figure that could climb to 35% if companies broadly beat estimates. If that bears out as expected, then the S & P 500 will have posted a fourth straight quarter of above-25% earnings growth, when the average 10-year earnings growth has been about 12% to 13% — a rapid expansion that speaks to the continued strength of the AI datacenter buildout. The rapid earnings growth also has the effect of compressing multiples. The S & P 500 forward P/E ratio was last at about 19, down from 22 at the end of last year. That means equities look more reasonable at this juncture even as they blast past record after record at an unnerving rate. But strong earnings do not necessarily translate into strong performance, which is what investors will be watching this earnings season. During the last earnings season, in the second quarter, stock reactions diverged from earnings results. FactSet’s Butters noted that stocks that beat failed to perform as well, while stocks that missed weren’t punished as much as they were historically, an unusual pattern. Consumer focus Next week will also bring crucial information on just how much pressure the consumer is facing, with the September consumer and producer price index, as well as retail sales, set to release. Those reports could show what other challenges companies are up against. The consumer price index is expected to show an uptick in inflation, with the headline number rising to 3.6% on a year-over-year basis, according to consensus estimates from FactSet. That would be up from 3.4% in the prior report. Core inflation, however, is expected to have moderated to a 0.2% increase on a monthly basis, decelerating from a 0.3% rise the month before. Wholesale inflation is also expected to have picked up in September, with a 0.5% monthly increase in the headline number, and a 0.25% rise in core inflation. That’s up from increases of 0.4% and 0.2% the month prior, respectively. Retail sales are expected to have moderated sharply to 0.35% last month, down from a 1.2% increase in the prior report. How the data shakes out will give investors a more complete picture on where companies and the consumer are headed next, and whether there are still enough positive forces lifting the stock market to a year-end rally or if the stormy wind gusts can knock it down. Week ahead calendar All times ET. Monday, Oct. 12 Tuesday, Oct. 13 6:00 a.m. NFIB Small Business Index (September) 8:15 a.m. ADP Weekly Employment change (09/26) 10:00 a.m. Existing Home Sales (September) 2:00 p.m. Treasury Budget (September) Earnings: Citigroup , The Goldman Sachs Group , Wells Fargo & Co. , JPMorgan Chase & Co. , Johnson & Johnson , Domino’s Pizza , UnitedHealth Group Wednesday, Oct. 14 8:30 a.m. Consumer Price Index (September) 8:30 a.m. Hourly Earnings final (September) 8:30 a.m. Average Workweek final (September) Earnings: State Street , Morgan Stanley , Bank of America , Progressive , BlackRock Thursday, Oct. 15 8:30 a.m. Initial Claims (10/09) 8:30 a.m. Empire State Index (October) 8:30 a.m. Philadelphia Fed Index (October) 8:30 a.m. Producer Price Index (September) 8:30 a.m. Retail Sales (September) 10:00 a.m. Business Inventories (August) Earnings: J.B. Hunt Transport Services , Interactive Brokers Group , The Charles Schwab Corp. , Marsh & McLennan Cos. , U.S. Bancorp , The PNC Financial Services Group , The Bank of New York Mellon Corp. , Prologis Friday, Oct. 16 8:30 a.m. Export Price Index (September) 8:30 a.m. Import Price Index (September) 9:15 a.m. Capacity Utilization (September) 9:15 a.m. Industrial Production (September) Earnings: The Travelers Cos. , Citizens Financial Group , Regions Financial Corp. , M & T Bank , Truist FinancialRead More
Earnings season kicks into high gear as big banks report next week. Here’s what’s ahead
More important than the results may be what the companies themselves have to say about their outlooks.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports