

Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
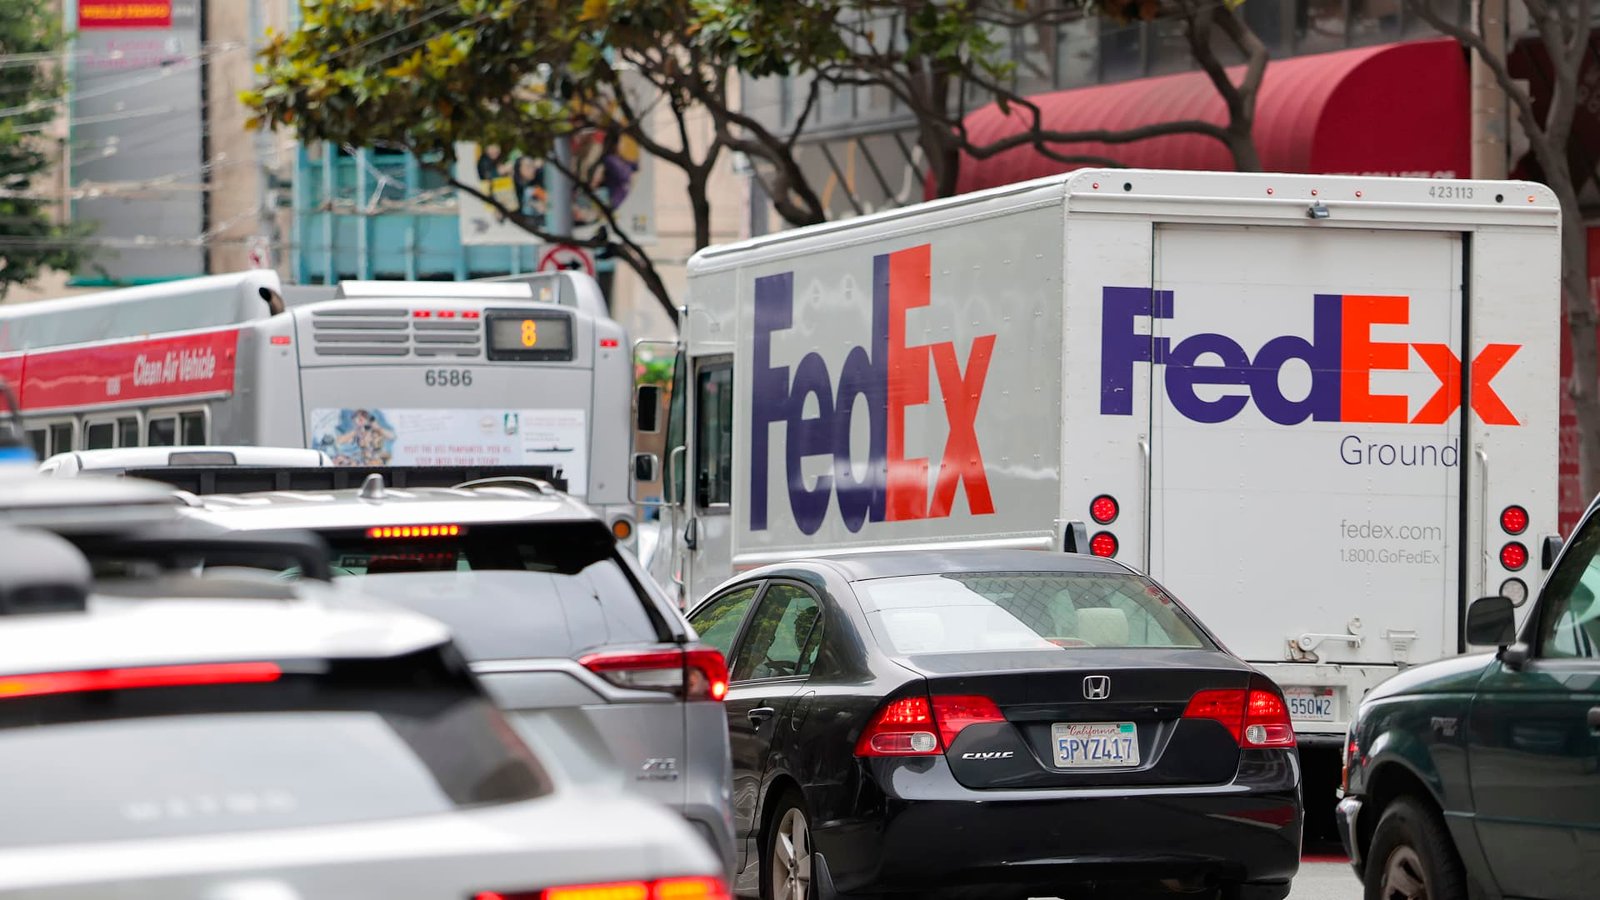
 LivestreamMenuFedEx on Wednesday night demonstrated that its transformation under CEO Raj Subramaniam is making progress, even amid higher fuel prices and a tight labor market for truck drivers. The company is controlling what it can control to become more profitable and stronger, enabling us to stay patient while all the moving pieces get sorted out. Revenue in the July-to-September quarter rose 12% year over year to $22.86 billion, beating the LSEG consensus of $22.42 billion. Adjusted earnings per share (EPS) increased 28% from a year earlier to $3.74, topping analyst expectations of $3.36, according to LSEG data. Adjusted operating margin came in at 5.24%, essentially in line with the 5.21% consensus. It represents modest year-over-year expansion. Shares fell more than 2% in extended trading to roughly $297 apiece. Combined with a 0.8% drop in Wednesday’s regular session, the stock is set to give back almost all of the gains registered in the first two trading days of the week. Most of that advance came Tuesday, when shares rallied 2% in sympathy with parcel-delivery rival UPS after Big Brown reported better-than-expected results. As of Wednesday’s close, FedEx is up 31% year to date, though it’s down about 10% from its all-time closing high of $339.35 on Aug. 13. FDX YTD mountain FedEx’s year-to-date stock performance. Bottom line Why aren’t investors as enthusiastic about FedEx on Wednesday night as they were about UPS a day earlier? The simple answer is that the headline revenue and profit beats don’t tell the whole story, though we’re certainly glad both boxes were checked in the company’s first official earnings report without its freight division, which was spun off in June as FedEx Freight . This also marks FedEx’s first earnings report since adopting a December-ended fiscal year (previously May), adding another variable to interpreting the numbers. The sellers may be disappointed by FedEx’s profit guidance for the October-to-December quarter, which is the peak season for these delivery giants. At the midpoint of its outlook for the final three months of the year, FedEx expects to earn $6.33 a share. That is below the FactSet consensus of $6.58. And while the company expects adjusted operating income to be up year over year, executives highlighted a few “transitory headwinds” that will weigh on results in the December quarter. Chief among them is higher rates for third-party transportation — dubbed “purchased transportation” — as the labor market for linehaul truck drivers has tightened. By geography, FedEx expects the international segment to see operating margin expansion in the holiday quarter, while the domestic business will see margins “down moderately” due to those higher purchased transportation costs and higher fuel expenses. Fuel surcharges help FedEx protect its bottom-line profits, but they also boost top-line revenue and squeeze margins (a dynamic we explained in June). A big part of our reason for owning the streamlined, freight-free FedEx is that Subramaniam is making the company more efficient and profitable. So why are we willing to look through the light EPS guide and these domestic margin pressures? For starters, Subramaniam has a track record of being conservative with guidance, so he deserves the benefit of the doubt again. As for the margins, executives said on multiple occasions that they expect the domestic operating margin to expand annually in 2027. Interim CFO Claude Russ said the company has both “operational and commercial levers” to pull next year to overcome some of these cost headwinds and ensure margin expansion. We also like that the company continues to make its delivery network more efficient through consolidation, part of what it calls its Network 2.0 plan. Subramaniam said Wednesday that nearly 65% of eligible parcel volume is flowing through about 630 Network 2.0-optimized stations. That’s up from 45% and nearly 490 optimized stations at the end of June. Subramaniam said the company will tackle the large Los Angeles market, along with Charlotte and Oklahoma City, after the peak season concludes. “One hundred percent, we’re convinced that we’re going to improve our domestic margins in 2027 and beyond,” Subramaniam said. Another sign that FedEx is controlling what it can: revenue in the September quarter grew across its key business-to-business verticals, including the data center buildout, and premium business-to-consumer parcels. And ground economy volume was down 4%, which COO Brie Carere noted was “intentional as we really lean into premium.” This is part of FedEx’s decision to move away from delivering low-margin packages to your doorstep for customers such as Amazon — something we fully support because it will enhance profitability over the long run. (For its part, UPS has embraced a similar strategy.) Finally, FedEx repurchased $2 billion of stock in the June-to-September period, a sizable step up from the guidance management provided in June. At the time, interim finance chief Russ said FedEx expected to repurchase about $1 billion through the remainder of calendar 2026. With the way the stock slumped from mid-June into late July — and then again from late August through September — we support the increased buyback activity. It’s a positive sign of confidence that the management team believed the market wasn’t fully valuing the shares. FedEx has $4.3 billion in buyback dry powder remaining. Something to watch with capital allocation is how FedEx monetizes its retained 19.9% stake in FedEx Freight . This came up on the earnings call, though nothing concrete was offered other than that it provides the company “meaningful optionality.” Add it all up, and our reasons for starting a position in FedEx back in May remain intact. Though there are some challenges in the operating backdrop at the moment, we’re confident in Subramaniam and team’s ability to navigate through them. We’re reiterating our buy-equivalent 1 rating and price target of $380. Guidance Here’s FedEx’s new guidance for calendar year 2026 versus the outlook provided in late June: Revenue growth of approximately 12% year over year (up from 11%) Adjusted diluted EPS in the range of $18.00 to $18.60 (up from $16.90 to $18.10) Effective tax rate of 22.5% (down from 23%) Capital spending of $3.9 billion (unchanged) (Jim Cramer’s Charitable Trust is long FDX, FDXF. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
FedEx’s soft holiday-quarter outlook doesn’t change our view on the stock
CEO Raj Subramaniam’s transformation is making progress.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News


Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports


