Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
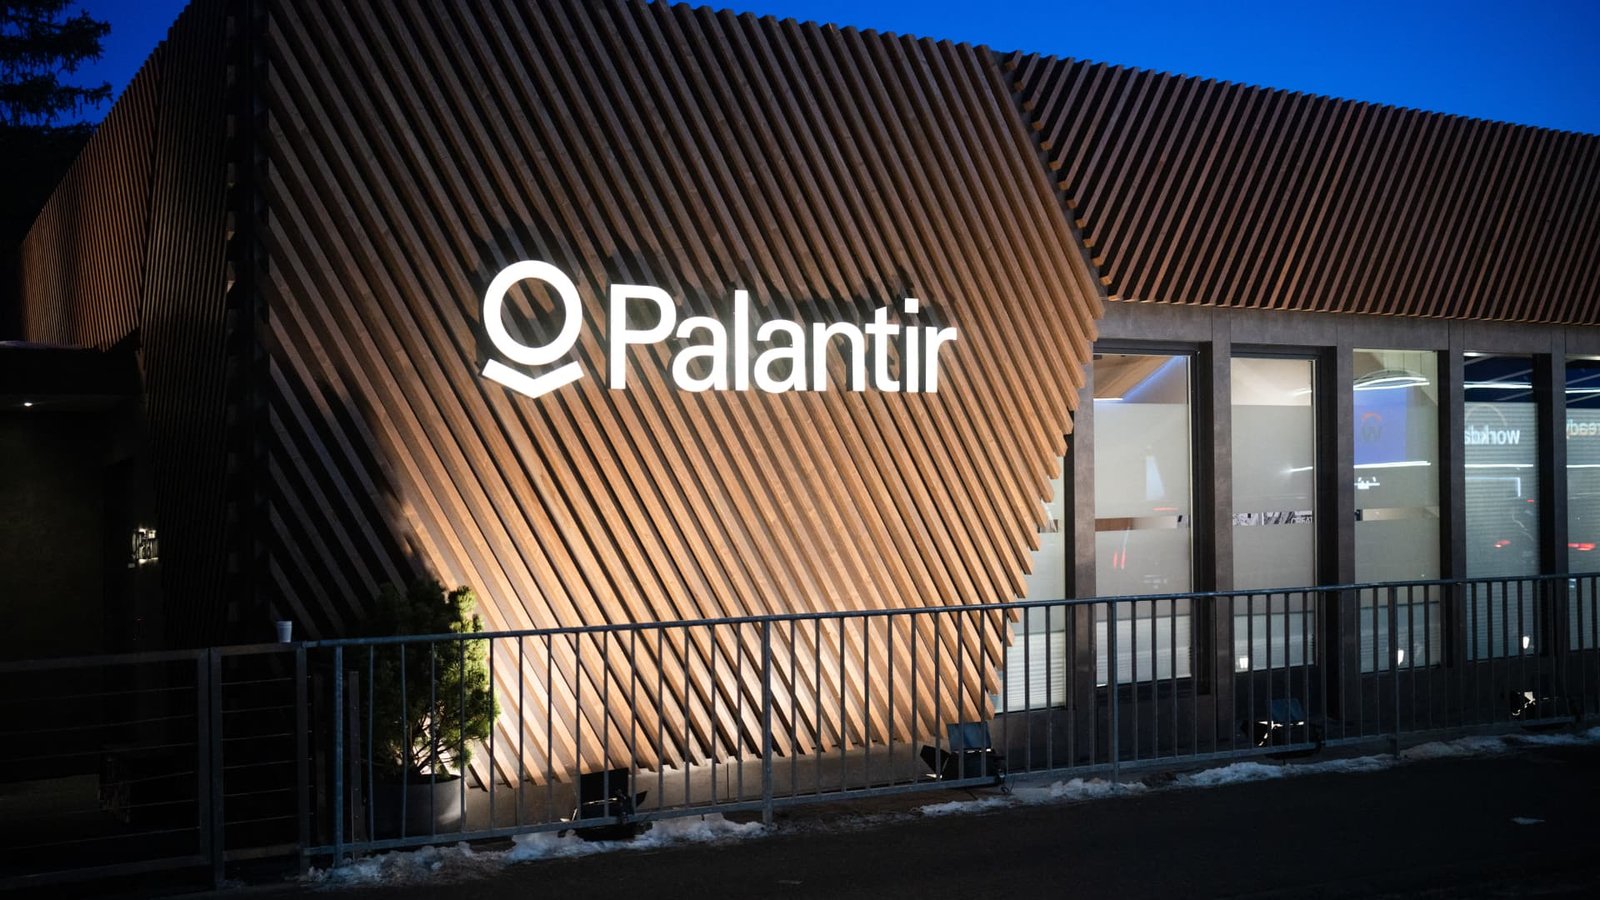
 LivestreamMenuPalantir Technologies looks relatively cheap, and shares of the data analyzing company should soon rebound as its artificial intelligence-linked software services gain more traction, according to UBS. The investment bank reiterated a buy rating on Palantir and raised its price target by about 14%, to $250 from $220, implying 44% upside from Monday’s close. “Last week we attended Palantir’s AIPCon customer/leadership event … our view of Palantir as the best AI enabler in the market (making frontier models/AI useful in large enterprises) was if anything bolstered by these conversations [with Palantir executives and customers] and demand momentum seems robust,” analyst Karl Keirstead wrote in a report Tuesday. Palantir provides AI-integrated software platforms to clients including the Department of Defense, enabling users to analyze massive data sets. Shares have edged down nearly 3% year to date due to concerns over Palantir’s sky-high valuation and amid a broader rotation out of technology stocks this summer. Palantir soared 135% in 2025, 340% in 2024 and another 167% in 2023. The stock now trades at 51 times expected free-cash flow for 2027, despite Palantir having “the highest growth and margin profiles across software,” according to UBS. At current prices, the stock is particularly attractive versus peers such as Snowflake and CrowdStrike , Keirstead wrote. The “valuation discount derives largely from investor concerns about a near-term growth rate peak and the potential that the model providers begin to target the data software layer,” the analyst wrote. “Palantir deserves a material multiple premium given its leading position in three key growth areas – AI, data and modern defense tech, making it a relatively cheap stock.” The UBS call matches the consensus on Wall Street, where 23 of 33 analysts rate it a buy or strong buy, according to LSEG data.Read More
Former highflier Palantir is a bargain compared to AI-linked software peers, UBS says
Trading at relatively cheap levels, Palantir is likely to rally as outsized demand for its services keeps fueling growth, according to the Wall Street bank.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets news People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports