Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
 LivestreamMenuThere’s been a lot of talk about the move up in crude oil, the inflation surprise that’s come with it, and whether the Federal Reserve is about to begin an actual rate hike cycle. We’ve spoken and written about this frequently in this column. This week it stops being a thought exercise. The FOMC wraps a two-day meeting Wednesday afternoon, and futures markets have moved decisively toward a quarter-point hike. That would be the first increase since 2023. Before we get to what the Fed does, I want to be precise about what’s actually driving long rates here, because I think most of the commentary has it wrong. Look at the three panels in this chart. The top panel is your 10-year nominal yield. Yes, 10-year yields are moving up, reaching 5% for the first time since 2007. The middle panel in orange is the 10-year breakeven — the market’s expected inflation. This is the point I keep coming back to: this move in nominal yields is not showing up as a move up in expected inflation. Breakevens sit at 2.37, well below the early 2026 highs. For all the noise about crude at triple digits, the bond market is not pricing a durable inflation problem. The bottom panel is your real yield, which is simply the nominal 10-year minus expected inflation. Real yields are going up without a corresponding move in expected inflation. That’s the whole story in one line. So what is this? I’m holding to the view that this is a competition for capital rather than an inflation scare — and that the market still prefers equities. At a 2.6% real yield, you’re only making 2.6% after inflation to lock up money for a decade risk-free. That’s a real hurdle for stocks, and it’s the highest that hurdle has been in years. But it is not yet high enough to break the equity bid. Watch that number. If real yields keep grinding higher, the math on that trade changes. This next chart is one I’ve pointed to before, and it’s worth revisiting. The blue line up top is the 2-year Treasury yield. The orange stair-step is the fed funds target upper limit. The bottom panel is the spread between them. The logic is simple: the 2-year yield is the bond market’s forecast of where policy is headed. When that spread widens sufficiently — when the 2-year runs far enough above the Fed funds ceiling — history says the Fed follows. It has to. The market is telling it to move. Look at the two marked points. In December 2015, the spread got to 0.65, and the Fed began hiking. In March 2022, the spread reached 1.50 and the Fed began the most aggressive tightening cycle in four decades. Today that spread sits at 91 basis points, with the 2-year at roughly 4.66% against a 3.75% ceiling. That is wider than the 2015 signal. I think we’re now at the point where history says the Fed raises. Here’s where it gets interesting for equity positioning. Historically, the spread between the 2-year yield and fed funds has had a meaningful impact on the market’s preference for value or growth stocks. There are some powerful examples on this chart. Heading into the pandemic, the value/growth ratio was falling — meaning growth stocks were outperforming — as the purple 2-year/fed funds spread was dropping. Then, coming out of the pandemic through 2021 and 2022, the spread turned sharply higher and the value/growth ratio moved up with it as the market rotated out of growth and into value. Fast forward to 2023, and the pattern repeated in reverse. The spread rolled over from its 1.50 peak, and the value/growth ratio declined right alongside it. So the relationship is well established. Spread up, value leads. Spread down, growth leads. Here’s a closer view of the same two lines. Ever since the back half of 2024, the 2-year/Fed funds spread has been moving up quite sharply. It’s traveled from roughly -1.80 all the way to positive 0.91, where we find ourselves today. That is a massive repricing of the policy outlook, and by the historical relationship above, it should have produced a decisive rotation into value. It hasn’t. The value/growth ratio has barely come off the floor. Yes, there’s fear of higher inflation and a Fed rate hike landing today. The bond market has repriced violently. And value still can’t get out of its own way. So, is this the market’s way of telling us we’re still firmly in the grips of a growth trade — one strong enough to override the rate signal that has historically governed this rotation? That’s the question I’d put to anyone arguing the leadership is about to change hands. Let’s finish with straightforward technical analysis on the Vanguard Value/Vanguard Growth ratio. Again, as this ratio declines, value stocks are relatively weaker than growth — growth is outperforming. And this ratio has been declining since 2006, as evidenced by the major trend line running down the chart. That’s two decades of growth leadership, interrupted only briefly. It’s also worth looking at what actually sits inside these two baskets today, because the labels have drifted from what most investors picture. The top holding in the Vanguard Value ETF is Micron at 3.93%, followed by JPMorgan Chase and Berkshire Hathaway . On the growth side, Nvidia alone is 13.61% of the fund, with Apple at 12.48% and Microsoft at 10.11% — roughly 36% of the ETF in three names. When you take a position on this ratio, that concentration is what you’re actually trading. Moving to the short term, the minor trend line is the level that matters right now. Growth is still in play while we’re below 2.72 resistance on the ratio. We’re at 2.55 today. If we push above 2.72 I think you could see a major rotation into value. This clearly defined resistance and potential breakout level is what I’ll be focusing on to help shift through all the noise telling us what “should” be happening. Let’s make smart decisions with our portfolios based on what IS happening at the hard right edge. But until the ratio confirms, I’m not front-running it. For now, despite the move higher in interest rates, I think the growth trade remains in favor. I’ll be updating you weekly here if my preference changes. -Todd Gordon, Founder of Inside Edge Capital, LLC We offer active portfolio management and financial planning for retail investors, as well as regular market updates like the idea presented above. Visit us at https://www.insideedgecapital.com/cnbc DISCLOSURES: Gordon owns MU, AAPL, NVDA, JPM personally and for clients of his wealth management company Inside Edge Capital, LLC. All opinions expressed by the CNBC Pro contributors are solely their opinions and do not reflect the opinions of CNBC, or its parent company or affiliates, and may have been previously disseminated by them on television, radio, internet or another medium. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET. THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL’S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR. Click here for the full disclaimer.Read More
Growth stocks are still attractive compared to value even as rates rise, charts show
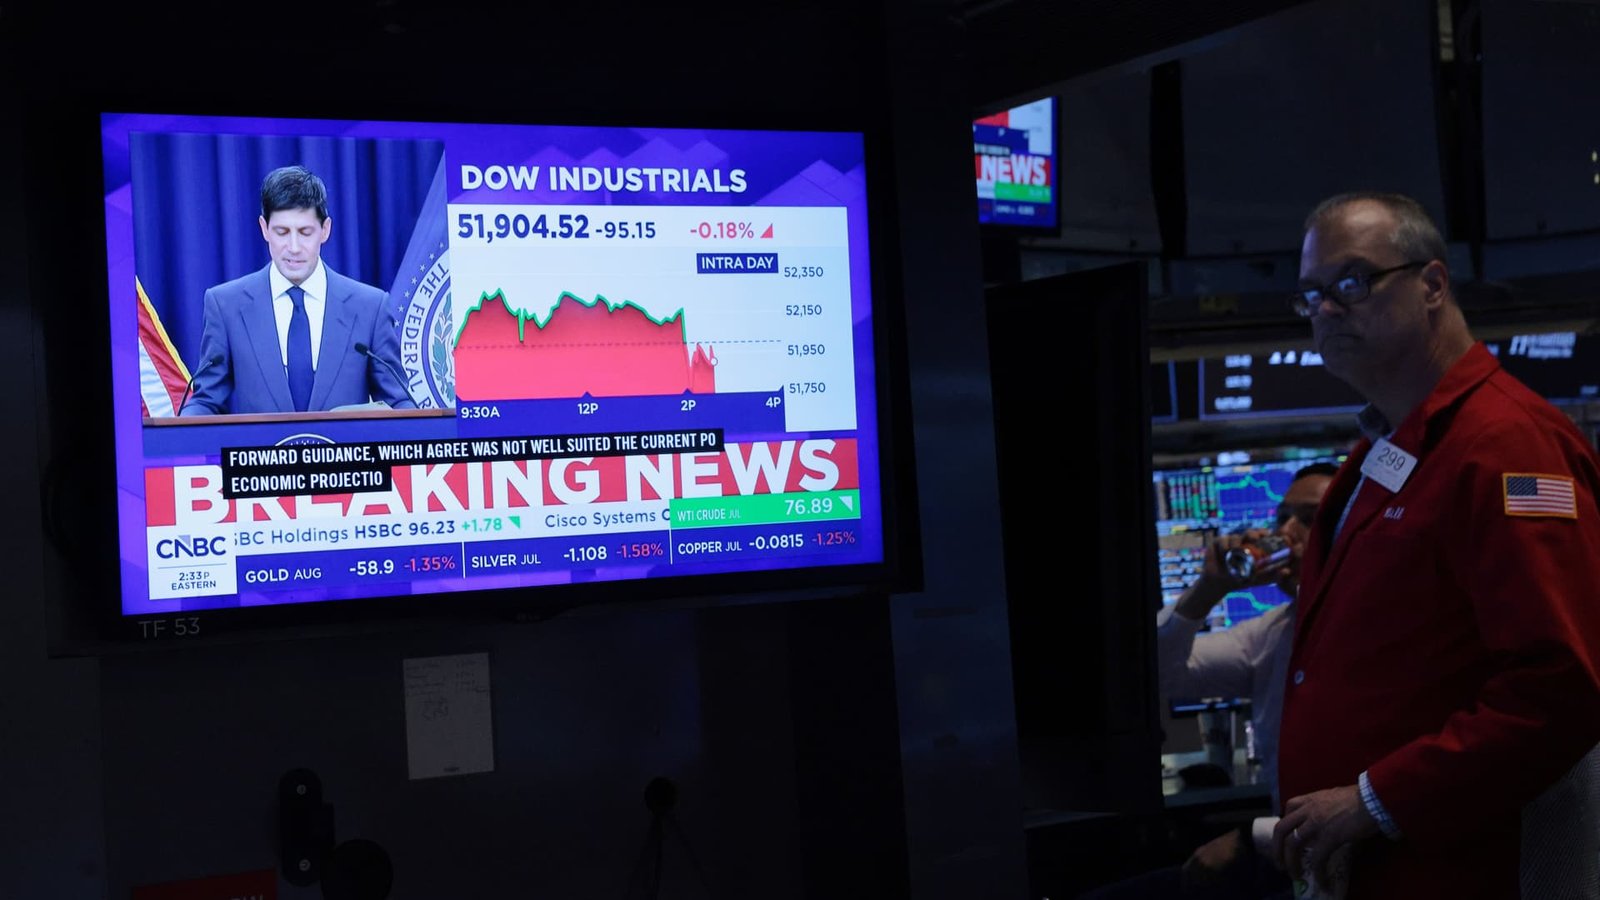
Todd Gordon breaks down the technical outlooks for growth and value stocks ahead of the key Fed decision.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany Investment strategy iran Iran war markets news People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports