Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
 LivestreamMenuMeta Platforms may be leaving billions of dollars in potential cloud revenue on the table. The reason? It may have found a much better use for its computing power. In a Tuesday note to clients, Wells Fargo argued that enthusiasm around the company’s Muse artificial intelligence agent is justified. At the same time, the analysts removed 500 megawatts of expected capacity resales from its 2027 estimates — roughly $5 billion of high-margin revenue — because Muse’s early success makes it increasingly likely Meta will need that computing power itself. We’re fine with that trade-off. Renting out unused capacity could generate revenue relatively quickly, but Muse has the potential to become a much larger business over time. Wells Fargo raised its price target on Club stock Meta to $1,000 from $796 on Tuesday, implying nearly 35% upside to Monday’s close. “Do we really like SpaceX more because they have more compute that they can lend than we like a company that’s actually taking the compute and making it into a big business?” Jim Cramer said during Tuesday’s Morning Meeting . “I want the compute to be used for something that’s very productive.” Renting out compute capacity made more sense for SpaceX as a way to generate cash from infrastructure it wasn’t fully using. Meta already has a highly profitable advertising business, giving it more flexibility to invest for the long term. Growing competition from so-called neocloud providers could eventually pressure the economics of simply renting out computing power. That’s a significant change from how investors were looking at Meta just a couple of months ago, when much of the focus was on whether Meta would launch a cloud business. Shares struggled for much of the year as the Facebook and Instagram parent poured increasingly large sums into AI infrastructure without giving Wall Street enough evidence of how those investments would generate new revenue. Jim had been pushing Meta on the cloud idea — and on July 1, Meta CEO Mark Zuckerberg confirmed it was on the table, giving the stock a brief reprieve. However, a lack of specifics boiled over after Meta’s second-quarter earnings miss and disappointing guidance in late July, sending the stock right back down. META YTD mountain Meta Platforms YTD Then things started to really turn around. On the consumer side, Meta on Aug. 26 settled youth social media addiction litigation with attorneys general from across the nation for up to $18 billion, avoiding what Jim thought could be some $200 billion in fines in the event of courtroom losses. On Sept. 8, Meta launched Muse, allowing users to hand off tasks ranging from sending emails to booking travel and making purchases. The early response quickly changed the conversation around the stock. Meta shares surged 27% in September, its best month since Nov. 2022 , compared with a 0.5% decline on the benchmark S & P 500 . That buttoned up the consumer side. Then, Zuckerberg stepped up his enterprise game. On Sept. 28, he announced the new Meta Enterprise Platform business and hired MongoDB CEO CJ Desai to run it. The next day, Meta unveiled Muse for Small Business. “[Muse] is incredibly popular, and we know it’s been downloaded and downloaded,” Jim said. “You get Muse, and then you do a lot more with it. And I defy you to say that that’s not worth something.” Wells Fargo compared the setup to the early days of Reels in 2022, but said Muse could ultimately represent a much larger AI-driven product cycle. The financial payoff, however, isn’t expected right away. The analysts cautioned against expecting Muse to meaningfully boost Meta’s results in 2027. They estimate operating expenses could reach roughly $212 billion next year, above the current Wall Street consensus of $202 billion, as Meta continues building the infrastructure needed to support its AI ambitions. Wells Fargo cut its 2027 earnings estimate to $31.18 per share and views next year as a potential trough before AI product revenue begins contributing more meaningfully in 2028, when it expects earnings to climb to $40.02 per share. Still, the analysts think that Meta’s advertising engine gives Zuckerberg the luxury of playing the long game. Wells Fargo expects third-quarter revenue of roughly $64 billion, up 25% from a year earlier, near the high end of the company’s guidance. We may never get the Meta Cloud business we once envisioned, but we don’t need it if Muse delivers. The next year may still be dominated by AI spending rather than AI revenue, but we’d much rather see Meta use its computing power to build its own next growth engine than rent it out to someone else. (Jim Cramer’s Charitable Trust is long META. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
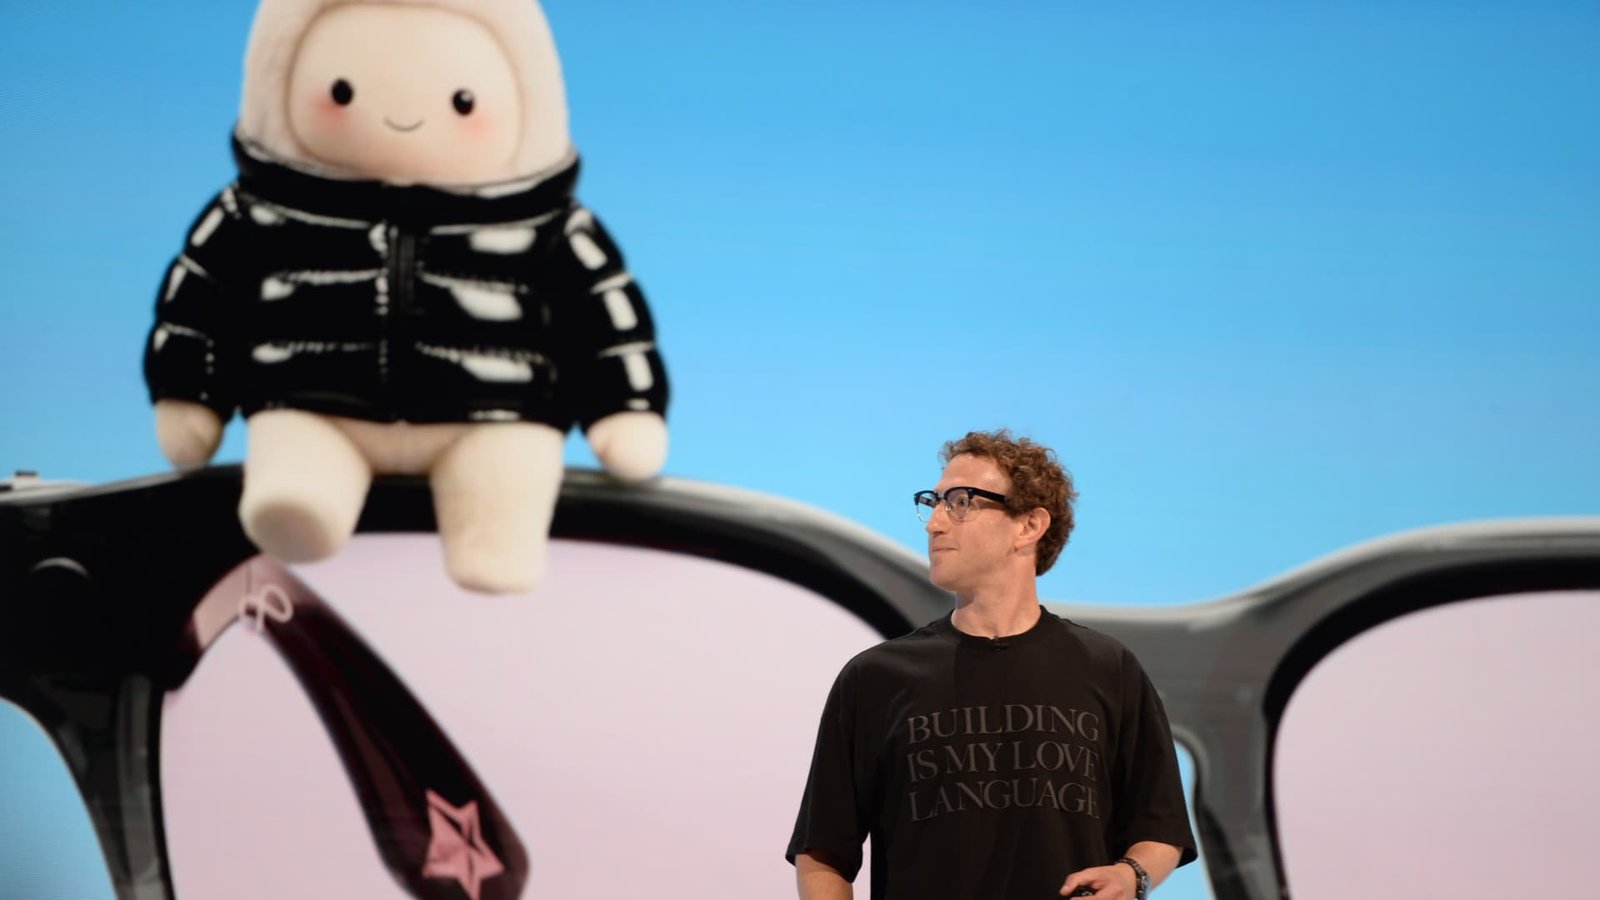
Meta may ditch the idea of a cloud business for Muse. We think that’s a good trade
We may never get the Meta Cloud business we once envisioned, but we don’t need it if Muse delivers.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports