Stocks gain on AI optimism; lower oil helps bonds
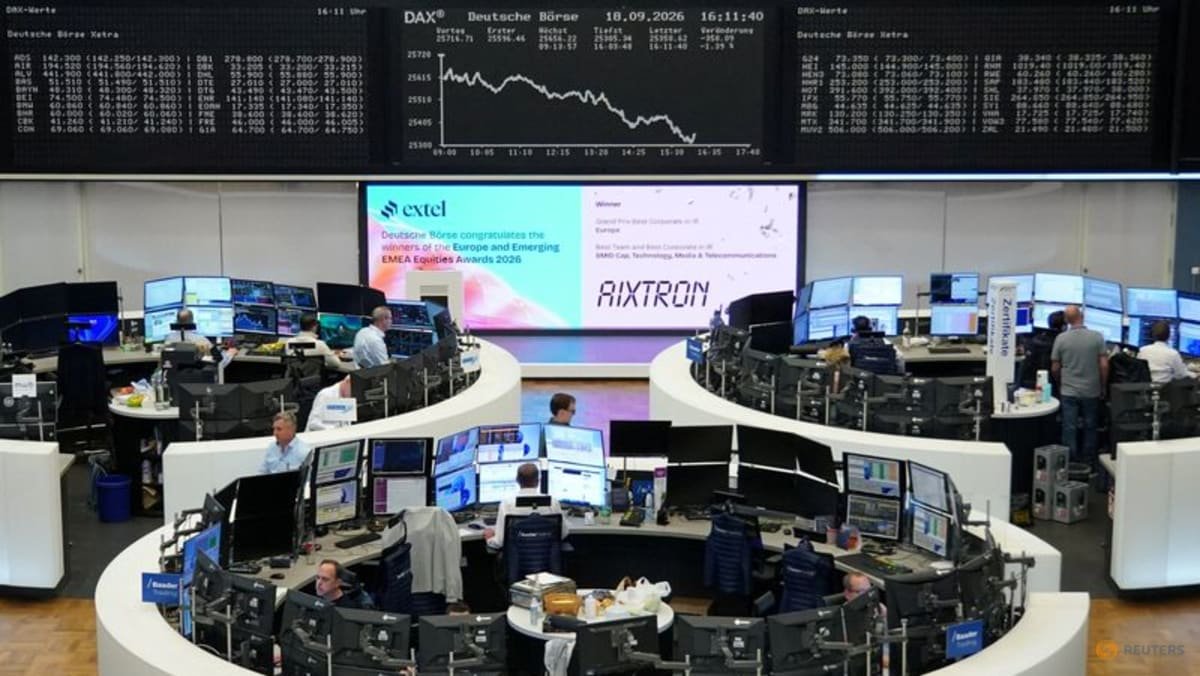
The German share price index DAX graph is pictured at the stock exchange in Frankfurt, Germany, September 18, 2026. REUTERS/Staff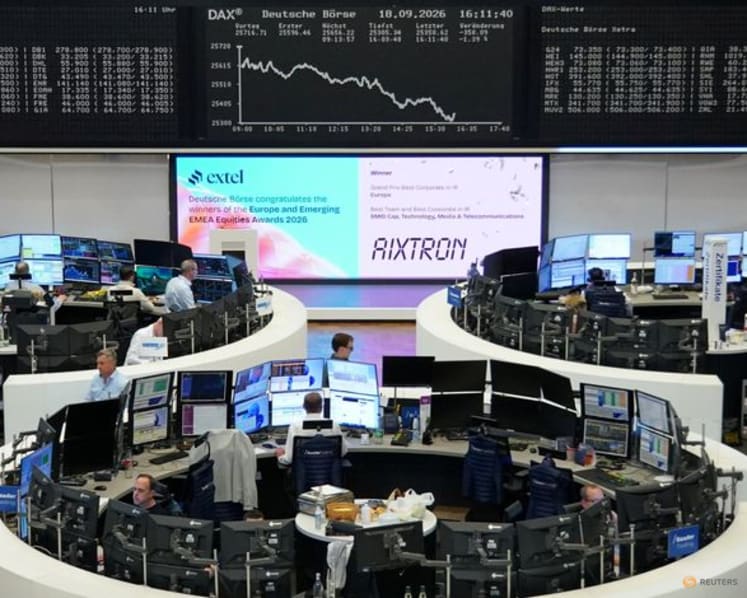
Read a summary of this article on FAST.
Get bite-sized news via a new
cards interface. Give it a try.
Click here to return to FAST
Tap here to return to FAST
FAST
LONDON, Sept 21 : Global stocks rose on Monday, as evidence of booming AI demand lifted tech shares, and oil fell on reports that more supply was leaving the Gulf than previously thought despite the ongoing conflict.
The bond market, which last week endured a sixth straight weekly selloff in the face of rising interest rates and a persistently high oil price, rallied, with European debt leading gains.
MSCI’s All-World index rose 0.4 per cent, while shares in Europe rallied 1.2 per cent.
Futures on the Nasdaq rose 1.1 per cent as shares in chipmakers rallied, with Intel up 5.2 per cent and AMD and Super Micro Computer up 2.4 per cent and 3 per cent, respectively, in premarket trading.
Guess Word
Crack the word, one row at a time
Buzzword
Create words using the given letters
Mini Sudoku
Tiny puzzle, mighty brain teaser
Mini Crossword
Small grid, big challenge
Word Search
Spot as many words as you can
South Korean data showed exports for the first 20 days of this month hit a record high, thanks to surging demand for chips.
S&P futures gained 0.7 per cent.
Some of the concern that rattled investors last week about global central banks possibly embarking on a hiking cycle subsided, as the oil price edged back towards $100 a barrel, from highs last week above $109.
“Maybe things got a little bit apocalyptic last week, and they’re just easing off. But obviously the direction of travel in oil prices is still higher. This is just a minor correction,” IG chief market strategist Chris Beauchamp said.
“Then again, the AI demand was cited overnight as the reason why tech stocks have bounced, so the ongoing themes just keep coming back to the fore … it’s just the sort of the dance where one narrative prevails over the other for the time being,” he added.
On the geopolitical front beyond the Middle East, US President Donald Trump will attend the United Nations General Assembly this week, ahead of a meeting with Chinese President Xi Jinping on Thursday.
OIL RETREATS, FOR NOW
Oil futures prices eased even as Iran and the United States exchanged new threats and after the Houthis attacked Saudi Arabia’s capital. Brent fell 2.6 per cent to $101.2 a barrel.
Data from analytics firm Kpler showed exports from Saudi Arabia had recovered to just over 4 million barrels per day (bpd) so far in September after slumping to 2.4 million bpd in August, the lowest since at least 2013.
There were also reports that Saudi producers were aiming to quickly restart some flows through the country’s main east-to-west pipeline after it was damaged in attacks last week, though details were lacking and analysts harboured doubts.
“We now estimate that oil markets have 5 to 10 weeks before global oil and refined product inventories deplete, compared to estimates closer to 15 to 20 weeks just a fortnight ago,” Vivek Dhar, head of commodities at CBA, said.
Against that backdrop, central banks in most major economies are expected to raise rates again this year. Hawkish guidance from the Federal Reserve last week has futures wagering on a 56 per cent chance it will hike rates again in October, with a move by year-end considered a done deal.
Bonds have been hit hard as a result, with the average 10-year yield for the Group of Seven biggest economies at its highest since 2008 around 4.2 per cent.
Concern about the impact of inflation, as well as over governments’ long-term finances, hit French debt on Friday, sending its risk premium to the highest since the 2012 euro zone debt crisis.
In Germany, Chancellor Friedrich Merz’s mainstream conservative party suffered its worst election results since 1949. But the driving force for bonds remained the drop in oil, leaving German 10-year yields down 5 basis points at 3.472 per cent and French 10-year yields 10 bps lower at 4.469 per cent, unwinding almost all Friday’s rise.
In foreign exchange, the dollar edged up 0.2 per cent against the yen to 157.2 , with investors wary in case the Bank of Japan took advantage of the lack of liquidity during the country’s three-day Silver Week holiday to step in to buy the currency.
The yen jumped on Friday after Japanese authorities conducted rate checks in the currency market, the Nikkei newspaper reported.
(Additional reporting by Wayne Cole in Sydney; Editing by Jamie Freed and Andrew Heavens)
Source: Reuters
Sign up for our newsletters
Get the CNA app
Stay updated with notifications for breaking news and our best stories
Get WhatsApp alerts
Join our channel for the top reads for the day on your preferred chat app
Get bite-sized news via a new
cards interface. Give it a try.
Click here to return to FAST
Tap here to return to FAST
FAST