Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
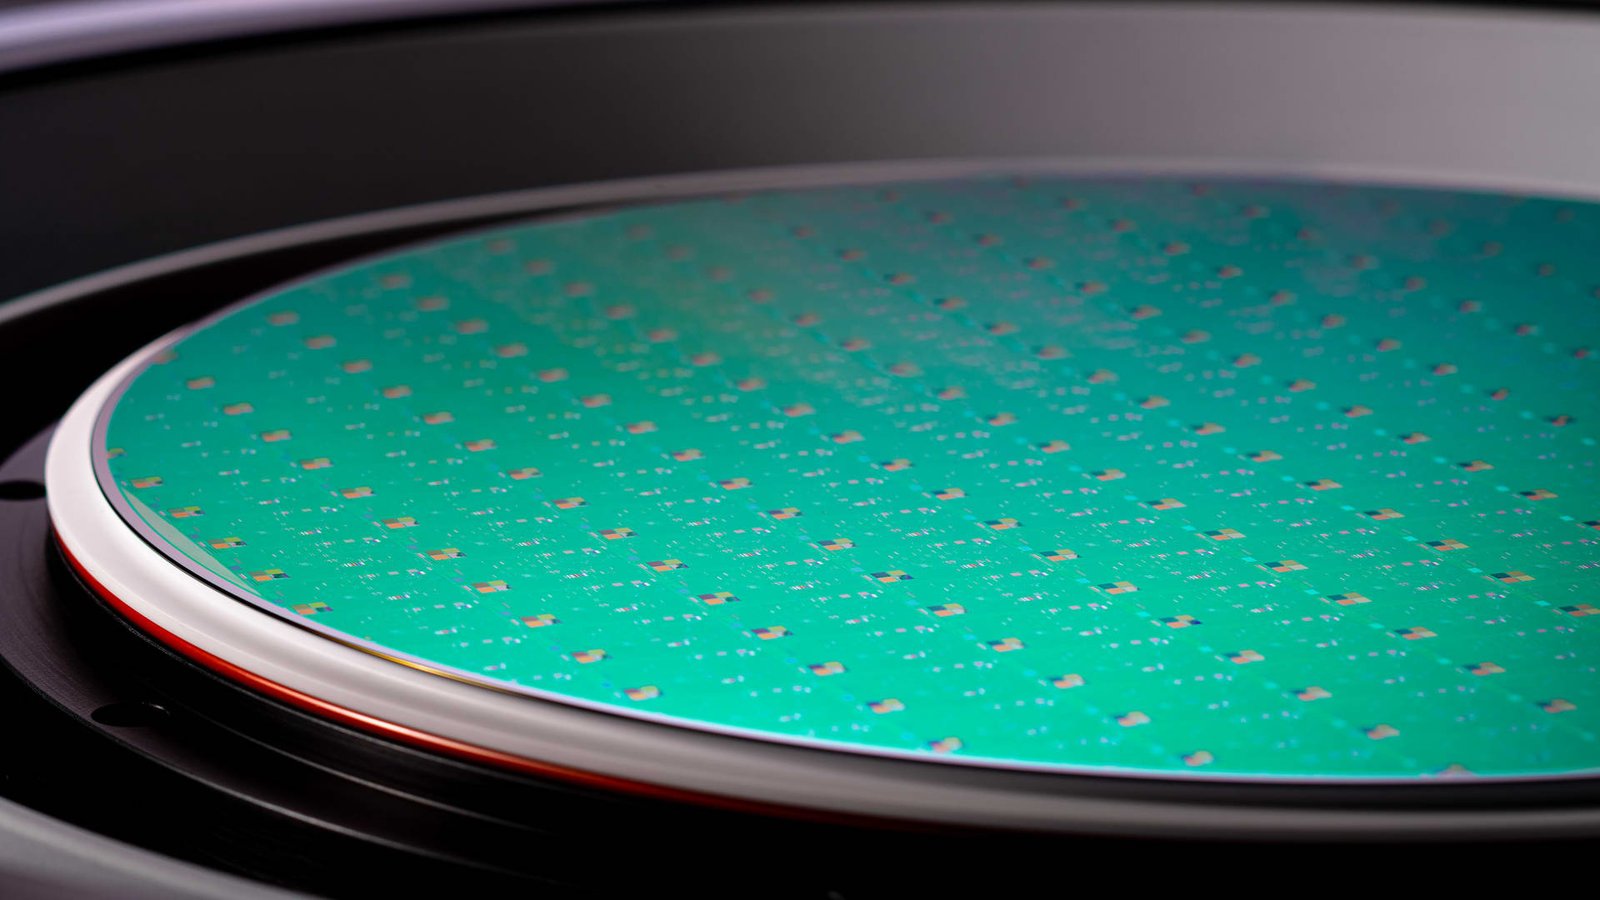
 LivestreamMenuLam Research Corporation has been on an impressive run this year, but with shares pulling back from their highs, I see an attractive buying opportunity. We already own in our Mango Growth ETF and we’re looking to potentially add to our position following the recent sell-off. The Fremont-based company makes specialized equipment that chipmakers use to manufacture semiconductors. Its tools help create the tiny, intricate structures inside advanced chips, making Lam an important supplier to the companies powering the artificial intelligence boom. Key points AI spending is driving demand for the advanced chips that Lam’s equipment helps manufacture. As chips become more sophisticated, Lam’s technology is becoming more essential to their production. Growing services business provides steady revenue and a cushion against a slowdown in AI spending. Lam is an important part of the semiconductor supply chain, even if it doesn’t get the same attention as the companies designing AI chips. And as the industry works to make chips more powerful and efficient, I believe Lam’s equipment will become increasingly valuable. Why I’m buying AI spending continues to fuel demand The world’s largest technology companies are spending heavily on AI infrastructure, driving demand for more advanced chips and memory. Lam reported record June-quarter revenue of $6.72 billion , up 30% from a year earlier. Revenue tied to NAND memory, used for data storage, more than doubled from the previous quarter. That momentum is expected to continue. Management projected September-quarter revenue of $8.1 billion and expects its advanced chip packaging business to grow more than 70% in 2026. I believe there’s plenty of room for further growth. More complex chips mean more opportunities for Lam As semiconductors become more complex, manufacturers increasingly rely on Lam’s specialized equipment. The company specializes in etching and deposition, two essential manufacturing processes. Put simply, its machines carve intricate patterns into chips and add the extremely thin layers needed to build them. I think the growing complexity of advanced chips presents a significant growth opportunity for Lam. Its services business offers protection against a slowdown Lam also generates revenue by servicing and upgrading machines already installed in customers’ factories. That business is growing rapidly, with revenue from its Customer Support Business Group climbing more than 40% year over year in the second quarter. LRCX YTD mountain Lam Research Corporation, YTD I like that this is a high-margin business with a more dependable revenue stream than new equipment sales. It could help cushion Lam if major technology companies eventually slow their AI spending. Why now? After a strong run earlier this year, Lam shares have pulled back roughly 37% from their 52-week high of $438.50 to around $275. I see this as an attractive buying opportunity following some profit-taking, particularly with earnings coming up on Oct. 21. Lam has beaten earnings estimates for 12 consecutive quarters, and its strong fundamentals could support another solid report. Bottom line Lam Research looks well positioned to benefit as AI chips become increasingly sophisticated and demand for its specialized equipment grows. The stock isn’t for the faint of heart. Investors should be prepared for continued volatility, but I’m willing to ride it out given the long-term opportunity. Jeff Kilburg is the founder and CEO of KKM Financial. Prior to starting his own firm, he spent more than two decades on the floors of the Chicago Board of Trade (CBOT) and Chicago Board Options Exchange (CBOE). Disclosures: Kilburg owns personally and in KKM Financial. All opinions expressed by the CNBC Pro contributors are solely their opinions and do not reflect the opinions of CNBC, or its parent company or affiliates, and may have been previously disseminated by them on television, radio, internet or another medium. This content is provided as part of our editorial output for informational purposes only and does not constitute financial, investment, tax or legal advice or a recommendation to buy any security or other financial asset. The content is general in nature and does not reflect any individual’s unique personal circumstances. The above content might not be suitable for your particular circumstances. Before making any financial decisions, you should strongly consider seeking advice from your own financial or investment advisor. THIS CONTENT IS PROVIDED FOR INFORMATIONAL PURPOSES ONLY AND DOES NOT CONSTITUTE FINANCIAL, INVESTMENT, TAX OR LEGAL ADVICE OR A RECOMMENDATION TO BUY ANY SECURITY OR OTHER FINANCIAL ASSET. THE CONTENT IS GENERAL IN NATURE AND DOES NOT REFLECT ANY INDIVIDUAL’S UNIQUE PERSONAL CIRCUMSTANCES. THE ABOVE CONTENT MIGHT NOT BE SUITABLE FOR YOUR PARTICULAR CIRCUMSTANCES. BEFORE MAKING ANY FINANCIAL DECISIONS, YOU SHOULD STRONGLY CONSIDER SEEKING ADVICE FROM YOUR OWN FINANCIAL OR INVESTMENT ADVISOR. Click here for the full disclaimer.Read More
This semiconductor stock is not for the faint of heart. Here’s why I see opportunity
Lam Research shares have pulled back from their June high as AI demand boosts chipmaking equipment, memory and advanced packaging.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News


Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports