Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
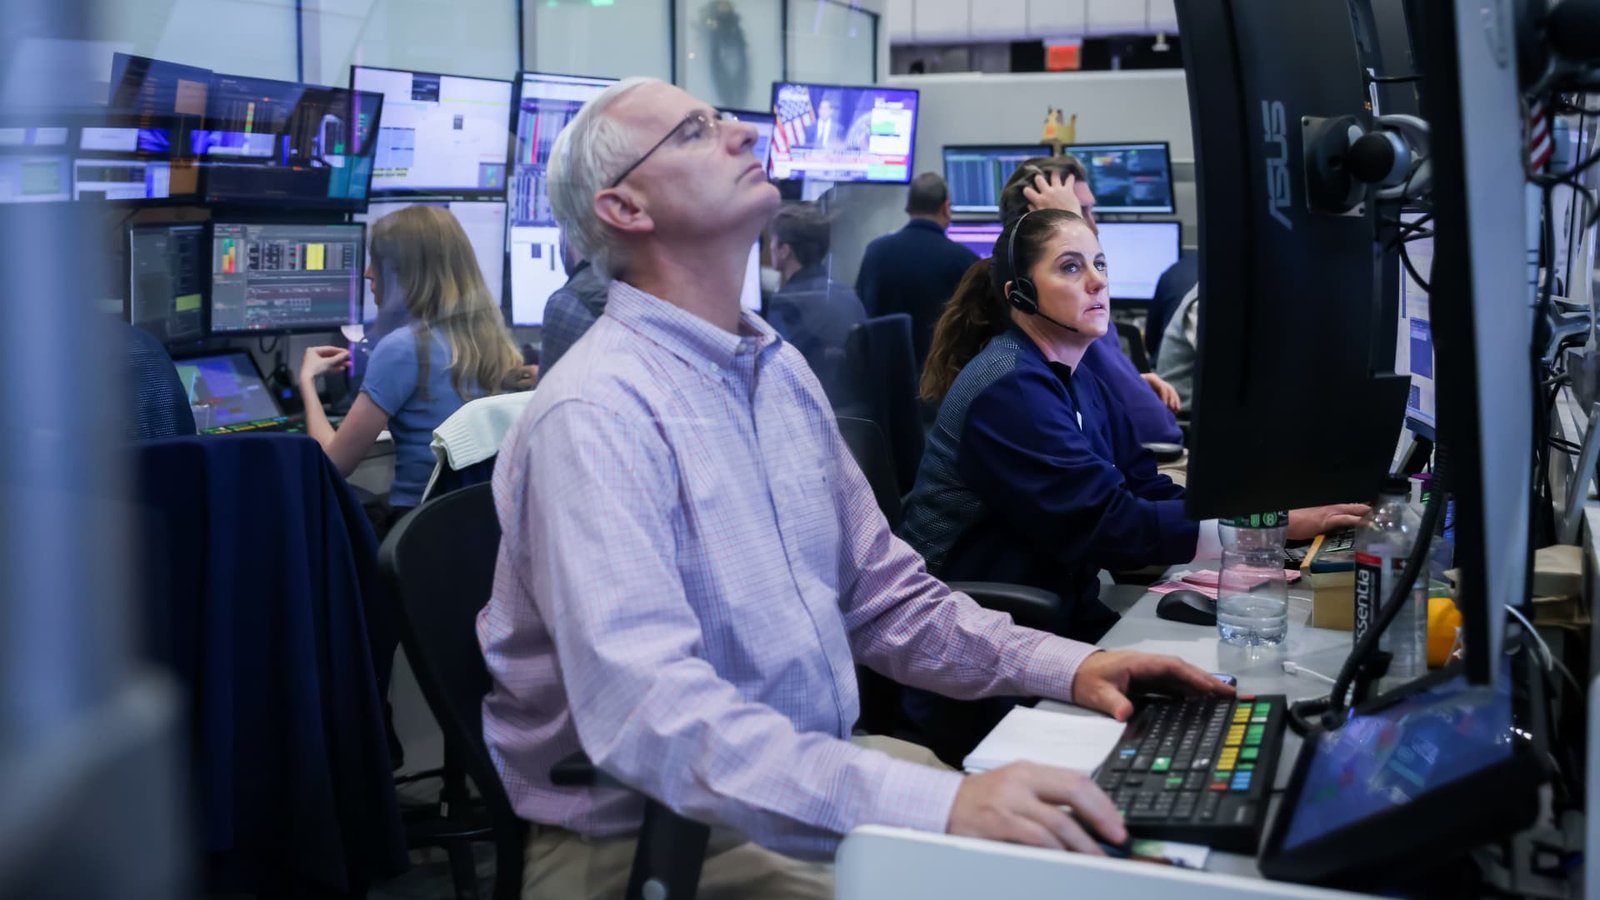
 LivestreamMenuTraders work on the floor of the New York Stock Exchange (NYSE) in New York, US, on Wednesday, Oct. 28, 2026. Michael Nagle | Bloomberg | Getty Images
Stocks wrapped their worst week since June on Friday, but a group of the most sophisticated options analysts agree the reaction in the options market was oddly calm.
While the Cboe Volatility Index (VIX), often referred to as a so-called fear index, did touch its highest intraday level since April on Friday, it quickly retreated and closed at 19.4. Its rollover came even as the S&P 500 finished the day down nearly 2%. For that size of a decline in stocks, the 2.2-point move in VIX was “relatively muted,” according to SpotGamma’s Brent Kochuba, whose analysis suggests VIX should have jumped closer to 2.6 points, based on a study of 126 selloffs since 2018.
Stock Chart IconStock chart icon Cboe Volatility Index, 5 day
Even in the Nasdaq 100 Index, where implied volatility increased for most options contracts, there were key exceptions. Prices on put contracts that are between 20% and 50% out-of-the-money were higher on a volatility basis after the sell-off on Oct. 16, according to data shared by Nasdaq’s Kevin Davitt.
So not only did traders not pile into S&P 500 Index options on Friday, they were also especially choosy with which Nasdaq hedges they bought. For example, in the Nasdaq, puts were more expensive two weeks ago, according to Nations Indexes data. And out-of-the-money S&P 500 Index puts “just aren’t being chased-into at this moment,” writes Nomura managing director Charlie McElligott, indicating investor calm in the face of falling stocks.
“Index options skew hasn’t been particularly reactive to the few days of spot equities selloff this week, and even where it has, it’s partially a function of call vol getting mushed,” McElligot said in a note to clients on Friday.
One explanation for the lack of hedging could be that asset managers are quickly selling stocks instead of using options to protect those stocks from further decline.
One popular chart making the rounds over the weekend came from Morgan Stanley’s prime brokerage. According to the firm’s data on long-short active managers, total global gross equity exposure is down 8% from its most recent peak, the biggest drawdown in at least ten years.
“Long/short has experienced a massive de-levering event,” said Zed Francis, CIO of Chicago-based Convexitas. “Buy the shorts, sell the longs. If you were closer to cash than you were before, no need to hedge. I believe this is the main reason implied volatility has remained quiet during an increased-stress month.”
Choose CNBC as your preferred source on Google and never miss a moment from the most trusted name in business news.Read More