Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
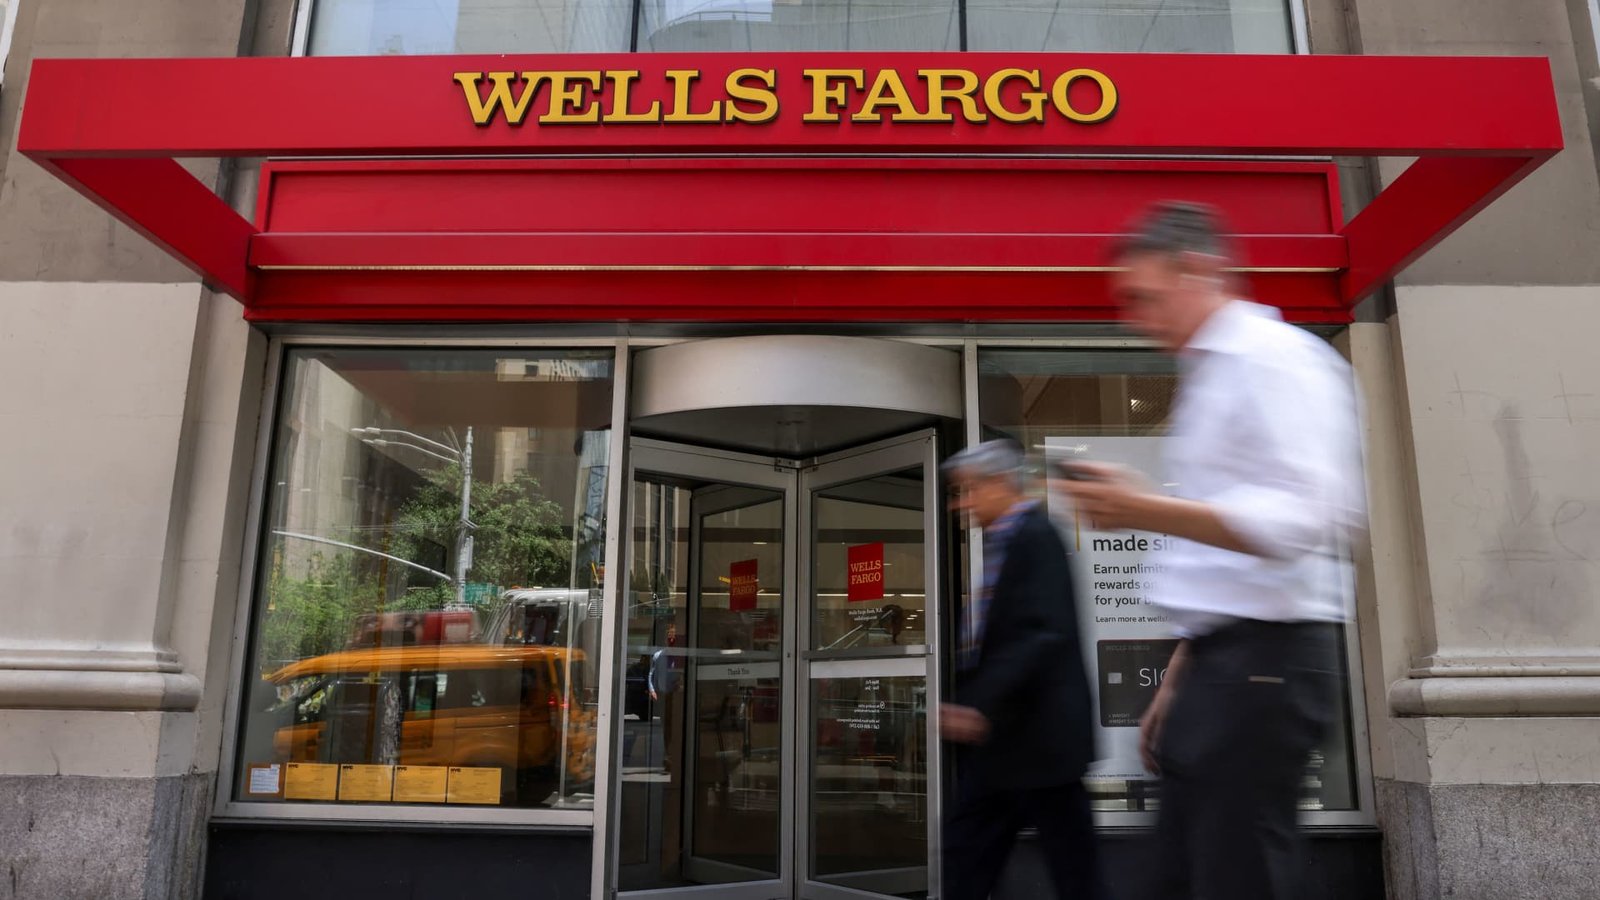
 LivestreamMenuMorgan Stanley is sticking its neck out for Wells Fargo with a bold upgrade just over a week before the bank reports earnings next Tuesday. The firm upgraded Wells to a buy-equivalent rating from hold Monday and named it a top pick — betting that one of this year’s biggest bank laggards is poised to play catch-up thanks to a “clearer path to improving profitability in 2027.” Analysts’ price target of $102 implies about 27% upside from Friday’s close and is about $6 above the Club stock’s record close in early January. Shares rose about 1.5% Monday but remain down about 12% this year. By comparison, BNY has surged 24%, Citi has gained nearly 11% and Goldman Sachs is up roughly 2%, while the Invesco KBW Bank ETF is up about 4%. BNY and Goldman are both Club names. What makes the call particularly striking is the timing. Rather than waiting for Wells to open its books next week, Morgan Stanley is betting that some of the biggest pressures behind that underperformance are already starting to ease. The willingness to make that call ahead of fresh results caught Jim Cramer’s attention. “Typically we would not get anything of any substance ahead of the numbers,” Jim said on CNBC, just before the opening bell Monday. “It was a very big call,” he added later on Monday’s Morning Meeting . The analysts see 2026 as a transition year for Wells Fargo following the removal of the Federal Reserve’s punitive $1.95 trillion asset cap last June, which restricted the bank’s balance-sheet growth for more than seven years. Freed from that constraint, Wells has rapidly expanded and ended June with $2.23 trillion in assets, up 15% year over year. But to achieve that growth, Wells initially relied on more expensive borrowing to fund lower-yielding assets. That squeezed net interest margin (NIM) — a profitability metric measuring the difference between what a bank earns on interest-bearing assets, such as loans, and what it pays to fund them. While customer deposits are the cheapest source of funding, banks also use more expensive wholesale funding channels, especially when they need money quickly. This is where Wells had found itself. Now, with the initial burst of balance sheet growth now slowing, Morgan Stanley said Wells should need less expensive borrowing and can fund more of its business with lower-cost customer deposits. Higher interest rates could provide another tailwind . Morgan Stanley expects NIM to stabilize around 2.42% through the first quarter of 2027 before expanding to 2.49% by the fourth quarter. “Normalizing balance sheet growth should ease funding pressure, stabilize NIM, and raises our conviction in the path to higher returns,” the analysts wrote. In the more immediate term, CFO Mike Santomassimo said at a Sept. 15 conference that Wells’ NIM for the third quarter ended in September was running ahead of expectations. The opportunity isn’t just about better margins. Morgan Stanley said Wells can “earn more fees from relationships where it is already committing capital,” particularly through investment banking. In other words, instead of just loaning a company money, Wells can do more advising on mergers and acquisitions. Wells has hired roughly 150 senior bankers over the past four years, gained share in M & A and equity capital markets, and more than doubled investment banking fees from 2022 levels, according to Morgan Stanley. Still, those fees remain well below peers relative to the size of Wells’ commercial loan book. Analysts estimate narrowing that gap could eventually generate roughly $4 billion in additional annual fees. “This piece says it’s finally happening,” Jim said of Wells’ investment banking buildout, which has been a priority for CEO Charlie Scharf. It’s a very relationship-driven business, so having respected bankers helps bring in business. It takes time to scale, though. While we spotlighted Wells’ investment-banking push back in 2024 , the bank is not in Dealogic’s top 10 global M & A advisor rankings this year. Goldman is No. 1, holding onto the top spot it secured in 2025. “[Scharf] is bringing in the right people, and they’re going to begin to win some deals,” Jim predicted. That’s an important part of the story for us going forward. Wells doesn’t need another massive balance sheet expansion to drive the next leg of growth. It can make more money from the larger franchise it has already built. Morgan Stanley expects Wells’ return on tangible common equity — a key measure of how effectively a bank generates profits from shareholder capital — to rise from 15.5% in 2026 to 17% in the second half of 2027 and 18% in 2028. The firm argues that improving profitability isn’t reflected in the stock, underpinning the upside to its $102 price target. We agree the setup is attractive, with shares trading at less than 11 times forward earnings, according to FactSet. That’s down from a 13 multiple at the start of the year. While we were been frustrated earlier this year that the asset-cap removal wasn’t leading to better quarterly results, Wells did enough in July to keep us around. If next Tuesday’s results show NIM stabilizing while Wells continues making progress in investment banking and other fee businesses, investors may finally start giving the stock more credit for the earnings power Scharf has spent years building. (Jim Cramer’s Charitable Trust is long BNY, GS, WFC. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
Wells Fargo gets a bold upgrade ahead of earnings. Why the stock can play catch-up
Wells Fargo received a bold upgrade just over a week before the bank reports earnings next Tuesday.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News


Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports