Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
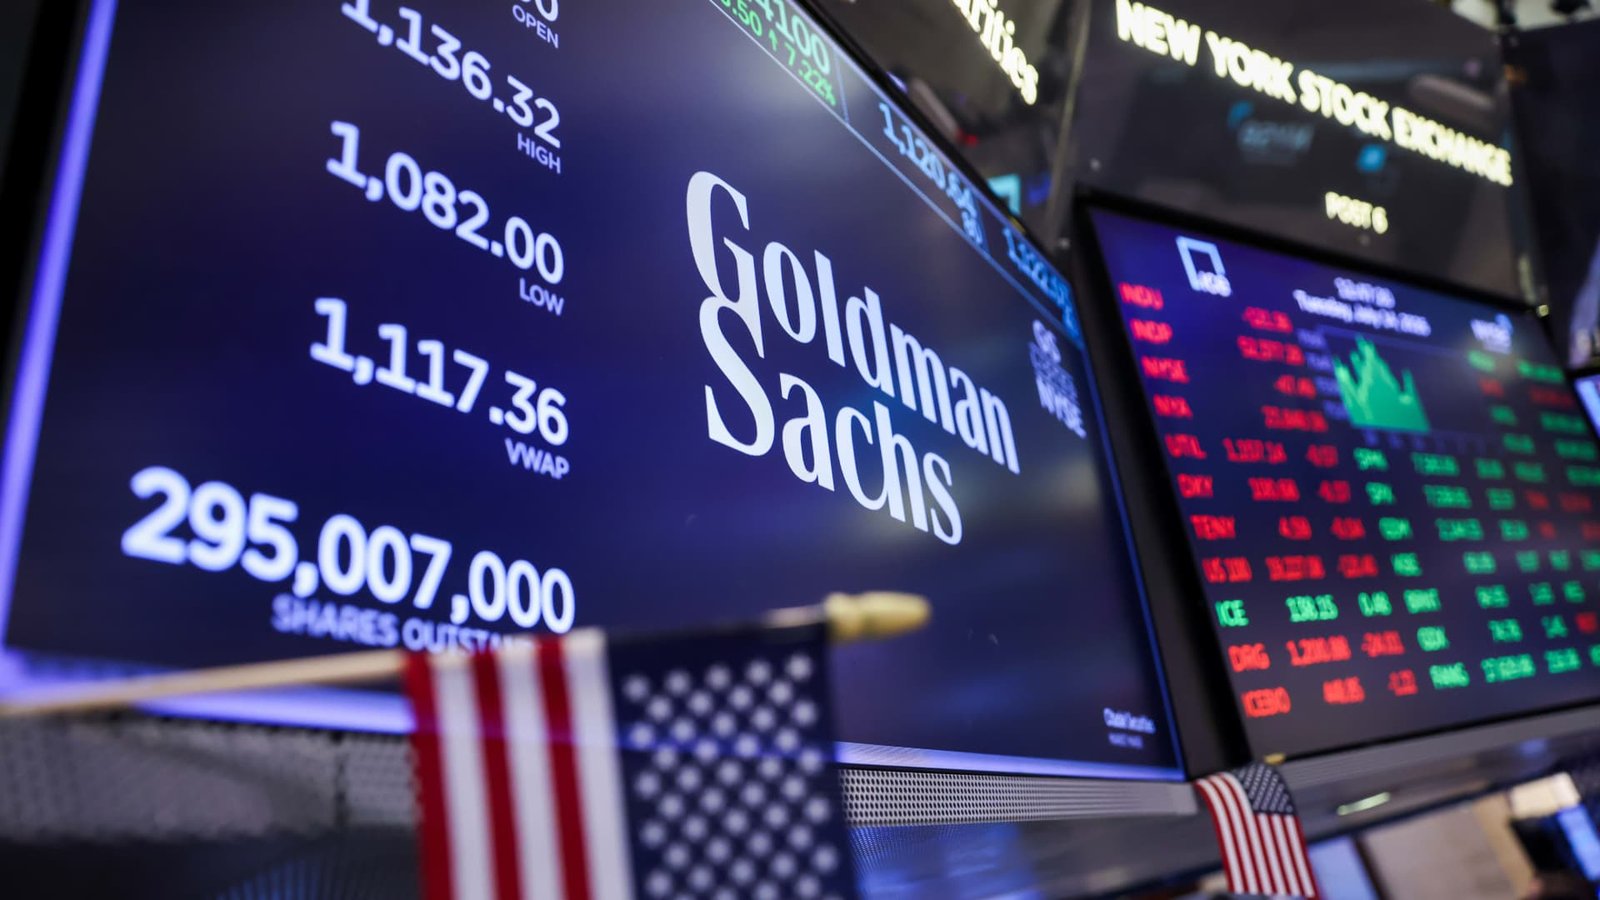
 LivestreamMenuFinancial stocks have taken a beating following the Federal Reserve’s first interest rate increase in three years. But if last week’s quarter-point hike marks the beginning of a new tightening cycle, our four holdings show why investors shouldn’t paint the entire sector with the same brush. Financials are one of the most Fed-sensitive parts of the stock market, because the central bank’s overnight lending rate target directly influences banks’ funding costs. That sensitivity has been on display this month as investors have priced in a potential for multiple rate hikes to squash elevated inflation. The State Street Financial Select Sector ETF , or XLF, is down more than 5% in September, making financials the third worst-performing S & P 500 sector, while the broader index is up 0.2%. Since the Fed’s Sept. 16 rate hike, the XLF has dropped roughly 4% while the S & P 500 has climbed 1.6%. For our four financial holdings — Wells Fargo , Capital One , Goldman Sachs and BNY — the impact of higher rates will vary because their businesses are so distinct. Wells is the closest to a traditional bank, collecting deposits and making loans to individuals and businesses. Capital One is heavily exposed to credit cards and the consumer. Goldman’s earnings are driven primarily by investment banking and trading. BNY generates most of its revenue from fees for servicing and safeguarding financial assets for other banks, corporations, and government entities. Those differences are exactly why we like owning multiple types of financial stocks. Their distinct business models give us exposure to different earnings drivers, offering diversification within a single sector as changes in interest rates and the economy affect each bank in different ways. It also means the old rule that higher rates are “good for margins” is too simplistic. “When it comes to interest rates, it’s more nuanced,” depending on the hiking cycle, RBC Capital Markets analyst Gerard Cassidy told CNBC. “There’s no perfect correlation where you can say, ‘As rates move up, sell the banks; as rates move down, buy the banks.’” When talking about Fed rate moves, the federal funds rate is the one everyone is referring to. The central bank sets the target range for federal funds, which is the overnight rate at which banks lend reserves to one another. Changes in that benchmark rate ripple through other short-term borrowing costs across the economy, influencing everything from bank funding costs to credit card rates. Last week, the Fed raised its federal funds target range by a quarter percentage point to 3.75% to 4% as policymakers confront stubborn inflation stemming in part from the war with Iran alongside a still resilient U.S. economy. The question now is how many hikes it will take to bring inflation back under the Fed’s 2% target . Banks can benefit early in a Fed tightening cycle because yields on loans and other assets may rise faster than what they pay depositors, expanding net interest margins, which is a key profitability gauge for banks. But as hikes accumulate, the focus can shift to deposit costs, the yield curve — and, ultimately, whether higher borrowing costs begin to hurt the economy and credit quality. Here’s how we’re thinking about each of our four holdings. Wells Fargo WFC YTD mountain Wells Fargo’s year-to-date stock performance. Of our four financial stocks, Wells Fargo has the most direct exposure to higher rates. They can go from friend early on to foe down the road, if they start to slow the economy. Shares are down 8.4% since the Fed’s rate increase and down 4.9% for the month of September, as of Thursday’s close, reflecting growing concern that the Fed’s September hike may not be a one-off. When the Fed raises rates, yields on Wells’ loans can reprice relatively quickly while the bank can take longer to increase what it pays depositors , widening its net interest margin. RBC estimates that an instantaneous 100-basis-point increase in market rates across the yield curve would boost Wells’ net interest revenue by roughly $1.3 billion, or 2.6%, translating into an estimated 4.7% increase in 2026 core earnings per share. For comparison, the same move would have a less than 1% impact on EPS at each of Capital One, Goldman and BNY, according to RBC. Cassidy expects the benefit to become more apparent in Wells’ fourth-quarter results, when “they could see a wider margin because of the lag effect of deposits.” The third-quarter numbers, set to be released Oct. 20, are unlikely to show much impact because the Fed raised rates so late in the period. Commercial and industrial loans and home-equity loans are among the assets that can reprice quickly as short-term rates rise, he added. The shape of the yield curve — which maps how bond yields compare across different maturities — also matters. Traditional banks generally benefit from a positively sloped curve, with lower rates on the short end and higher at the long end, because they fund themselves at shorter-term rates and lend further out. A flatter or inverted curve can squeeze that spread. That gap has narrowed this month with the spread between the 10-year and 2-year Treasury yields falling from roughly 40 basis points at the beginning of September to 25 basis points as of Thursday. A basis point is equal to 0.01 percentage points. The calculus changes if the Fed keeps hiking. Higher borrowing costs can eventually weaken loan demand and increase stress among borrowers. Cassidy said leveraged loans, which are made to companies with relatively high levels of debt often to finance acquisitions, would be one area to watch, while a meaningful rise in unemployment could also pressure consumer credit. That means Wells may have the most to gain early in a hiking cycle — but also greater credit exposure if those hikes eventually tip the economy into a downturn. Capital One COF YTD mountain Capital One’s year-to-date stock performance. For Capital One, the bigger impact from higher rates may come later. The direct effect of Fed hikes is relatively small, but a prolonged tightening cycle could become much more consequential if higher borrowing costs weaken the consumer. Shares have slipped 5% since the Fed’s rate hike and are down more than 8% in September. TD Securities analyst Moshe Orenbuch said the direct effect of higher rates on Capital One should be a “small positive,” while Jefferies analyst John Hecht described the company as broadly balanced from an interest rate risk perspective. Its credit card loans generally reprice alongside short-term rates, while its deposit costs eventually adjust as well. The speed of the hikes matters. Hecht said a rapid increase could temporarily pressure margins if funding costs rise faster than assets reprice, while a slower cycle gives the two sides of the balance sheet more time to adjust. Still, those movements are relatively small for Capital One, which, despite its credit-card reputation, also offers traditional banking services like checking and savings accounts, commercial lending, and auto loans. Truist analyst Brian Foran pointed out that the company operates with a net interest margin of roughly 8%, making a few basis points of movement much less consequential. “For them, it’s much more about: can the consumer bear this?” Foran said. Capital One’s heavy credit-card exposure means its biggest risk isn’t one or two additional hikes. It’s a tightening cycle that weakens the economy enough to pressure consumers. Capital One is more sensitive to this risk than peer American Express because it has a less affluent customer base. Foran said credit card delinquencies are the most important early indicator to watch and have so far been running “better than expected.” The firm’s focus on credit cards “makes higher returns on average through the cycle, but it’s more volatile,” Foran said. “You would expect a typical bank to see their earnings decline 20-25%, but you would expect a credit card company to see their earnings decline 30-60%.” The Discover acquisition makes credit even more important. Capital One completed the acquisition of Discover in May 2025. Foran said the deal slightly improved Capital One’s positioning for higher rates but also significantly increased its credit card exposure. Goldman Sachs GS YTD mountain Goldman Sachs’ year-to-date stock performance. Goldman Sachs has little direct sensitivity to higher interest rates. Shares have dropped 5.5% since the Fed’s rate increase and 10% in September. BMO Capital Markets analyst Brennan Hawken described Goldman as essentially “net rate neutral.” Its private-banking business can benefit from higher rates, but that upside is largely offset by higher deposit costs. RBC similarly estimates that a hypothetical 100-basis-point increase in rates would add just 0.2% to Goldman’s estimated 2026 core EPS. For Goldman, what higher rates do to capital markets activity — think underwriting and trading — matters much more. Higher financing costs can also weigh on mergers and acquisitions, particularly among private equity firms that rely heavily on debt. But Hawken said certainty around the rate path can matter more than the actual level of rates. “What we hear from bankers is that … way more important than the absolute level of interest rates is the certainty of the rate path,” he said. If buyers know financing will cost more a year from now, they can incorporate that into their models. Uncertainty about where rates are headed makes transactions harder to price. Trading can provide an offset. Changing rate expectations can create volatility, forcing investors to reposition portfolios and increasing activity. “Volatility generally helps trading because if you see things move, then firms need to reposition, and to reposition you have to transact,” Hawken said. So for Goldman, we’re watching whether higher rates disrupt the investment-banking recovery and whether increased volatility provides an offset through trading. BNY BNY YTD mountain BNY’s year-to-date stock performance. BNY, which is our newest financial, occupies another lane on the financial road. Formerly known as Bank of New York Mellon, BNY is a custodian bank that helps our financial system run smoothly. It holds assets for other firms, settles trades, provides liquidity management, and wealth management. We initiated our position in the stock on Sept. 2 to diversify away from the AI trade, added to the position twice last week during a slight pullback, and bought more on Tuesday. Shares have edged down roughly 3% since the Fed’s rate hike and dropped 6.9% in September. Roughly 70% of BNY’s revenue is fee-based, making it far less dependent on lending spreads than Wells. Higher rates can still lift net interest income as securities reprice at higher yields, but BNY’s institutional depositors are also quicker to demand higher rates, counteracting some of the benefit. This dynamic shows up in a metric known as deposit betas, which measures the changes in a bank’s deposit costs (what they pay in interest to customers) in response to changes in short-term interest rates. BMO’s Hawken estimates BNY’s deposit betas on its U.S. dollar deposits are around 80% to 85%, meaning roughly 20-21 basis points of a 25 basis point Fed hike could ultimately be passed through to those customers. That’s very different from Wells’ retail deposit base, where customers tend to be slower to demand higher rates. BNY also has far less credit exposure than a traditional lender. If tightening ultimately produces a downturn and loan losses rise, its smaller loan book and fee-heavy business should leave it less directly exposed than Wells. Bottom line The first Fed hike doesn’t fundamentally change our view of these holdings. Instead, it highlights why we own different kinds of financial companies rather than four versions of the same bank. Wells has the clearest near-term opportunity to benefit from higher rates, but the yield curve isn’t a major part of our thesis. We’re more focused on the bank becoming less sensitive to rates through CEO Charlie Scharf’s quest to build a larger investment banking and markets business. Capital One is much more dependent on what happens to the consumer in the medium and long term. Further capitalizing on its Discover acquisition is more of an immediate concern for us. Goldman is largely rate neutral, with the bigger potential effects showing up in investment banking and trading. BNY’s fee-heavy model limits both its direct rate sensitivity and credit exposure. As the rate cycle evolves, the opportunities and risks shift — but they don’t hit every business at the same time or in the same way. (Jim Cramer’s Charitable Trust is long BNY, COF, GS, WFC. See here for a full list of the stocks.) As a subscriber to the CNBC Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on CNBC TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.Read More
Fed may not be done hiking rates. What it means for our 4 very different bank stocks
The differences in their businesses are exactly why we like owning multiple types of financial stocks.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World world cup World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports