Mid-market gyms feel the heat in Singapore’s ‘golden age’ of fitness
Even as more Singaporeans exercise regularly, big box gyms are losing ground to boutique studios and budget 24-hour chains.
A woman exercising in a gym. (File photo: iStock)
New: You can now listen to articles.

This audio is generated by an AI tool.
Read a summary of this article on FAST.
Get bite-sized news via a new
cards interface. Give it a try.
Click here to return to FAST
Tap here to return to FAST
FAST
SINGAPORE: When personal trainer Sharon H started taking clients in April, she offered them the option of training in ActiveSG gyms, their own homes or her flat, which has a dedicated exercise space.
The 29-year-old told CNA she wanted to fill the “gap in the market” for clients who prefer more privacy and convenience, as the fitness scene is “saturated” with big box gyms.
About half of her 10 to 15 active clients work out at her flat. The rest train with her in ActiveSG gyms or their homes.
Hindrances like queues for machines at ActiveSG gyms and limited equipment in condominium gyms are counterbalanced by greater affordability and convenient locations.
When the trainer herself started exercising regularly around 2018, she followed videos on YouTube. She still primarily works out at home.
Guess Word
Crack the word, one row at a time
Buzzword
Create words using the given letters
Mini Sudoku
Tiny puzzle, mighty brain teaser
Mini Crossword
Small grid, big challenge
Word Search
Spot as many words as you can
This mix of home workouts and shared facilities exemplifies the “increasingly fierce” competition cited in True Fitness and True Yoga’s abrupt closure of all their studios in Singapore earlier this month.
Parent company Kontafarma cited “unprecedented” challenges: the growing popularity of boutique studios, more residential gyms reducing the need for external memberships and the rise of online training options.
But taking a wider view complicates this explanation.
“We are in what the industry calls the ‘golden age of fitness and wellness’. There has never been greater awareness (of) the importance of exercise,” said Mr Sean Tan, co-founder and president of the non-profit Singapore Fitness Alliance.
More people in Singapore are keeping active. Sport SG data showed that 76 per cent of residents exercised at least once a week last year, a figure that has risen almost every year since before COVID-19, when it stood at 66 per cent in 2019.
With the market growing, fitness studio owners pushed back against the idea that industry-wide headwinds were what ailed True Fitness and True Yoga.
“If a free gym downstairs is enough to make someone switch, it raises the question of what else that gym is offering beyond access to equipment,” said Mr Samuel Gallo, co-founder of Surge Strength & Results.
“The market itself has never been bigger,” he said. “Demand is not the problem. Being nothing in particular is the problem. Not the cheapest, not the best, so people drift out of the middle.”
MIDDLE OF THE PACK
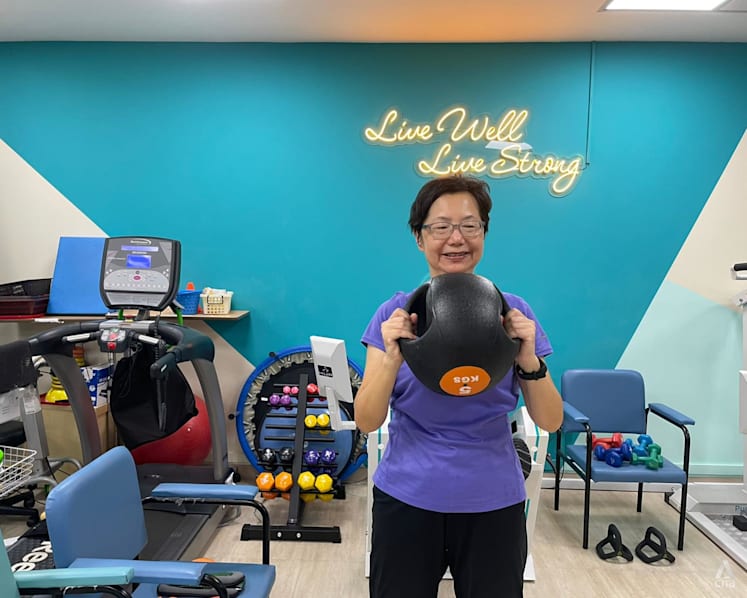
Conventional big box gyms like True Fitness sit in the middle of the market, between boutique gyms offering specialised or premium experiences on one end, and low-cost 24-hour gyms with convenient heartland locations on the other.
Big box gyms tend to be upwards of 15,000 sq ft and offer all kinds of training under one roof, from treadmills and elliptical machines for cardio, to pin-loaded machines for strength training, said Mr Tan.
These gyms usually provide personal training and have studios for group classes, recovery facilities like saunas or cold plunge baths, as well as showers, changing rooms and even swimming pools, he said.
True Fitness’ TFX club in Millennia Walk was the epitome of this – at more than 41,000 sq ft, it was the largest gym in Singapore before it closed.
“Large gyms carry significant fixed costs in rent, equipment, staffing, utilities and maintenance, so profitability becomes a challenge when utilisation falls,” Mr Tan said of this business model.
“Operating costs remain high, while consumers have more alternatives these days and can switch providers with ease, making membership revenue less predictable.”
In contrast, boutique gyms with smaller footprints of 1,000 to 2,500 sq ft are less costly to set up. They usually offer only a single modality, such as pilates or indoor cycling, and may not have showers or toilets.
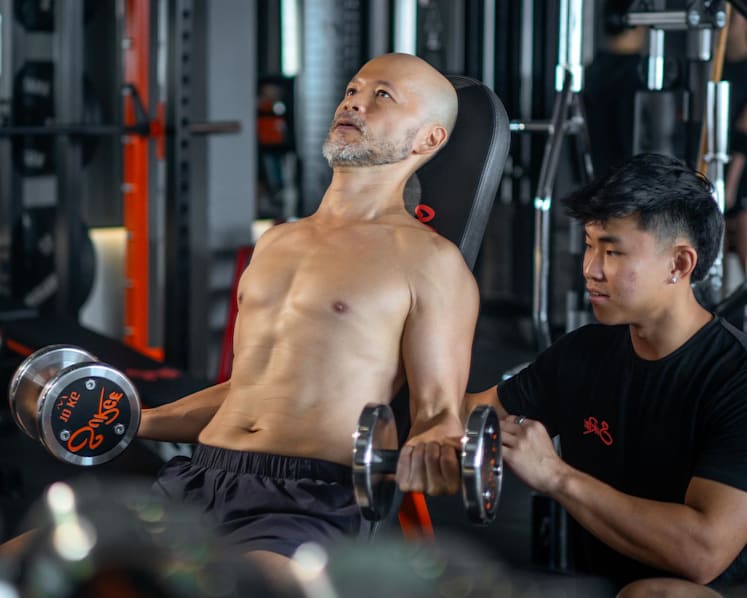
Such gyms that offer specialised training and small- to mid-sized studios with premium wellness services are more resilient, said Mr Damien Lee, senior lecturer in sport and wellness management at Nanyang Polytechnic.
This is because they offer unique expertise, personalisation, a strong sense of community and measurable fitness outcomes, he said.
The other growing segment comprises lower-budget, 24-hour franchises like Anytime Fitness, Snap Fitness and 24/7 Fitness. Sized around 4,000 to 6,000 sq ft, they may offer personal trainers and group classes.
It costs much less to rent and outfit these smaller gyms, which are also able to open closer to where their members live. They save even more by not providing showers or toilets, the most expensive part of a gym’s built facilities, said Mr Tan.
“Their lean operating model allows them to compete effectively on convenience and affordability without the overhead burden that weighs on larger operators,” added Mr Lee.
In short, consumers are now gravitating towards either value and convenience, or specialised training and premium experiences, he said.
“Operators in the middle could face greater challenges in setting themselves apart from their competitors.”

“BOUTIQUE” DOES NOT JUST MEAN SMALL
Even then, just being “small versions of the same commercial gym” does not cut it for a boutique fitness studio, according to Mr Gallo.
Boutique studio operators emphasised the service layer they build on top of gym hardware. This usually involves fitness or wellness experts who work closely with clients and keep them accountable to their goals.
Surge goes all in on one-to-one personal training, with no group classes or gym memberships. It has three locations, but Mr Gallo said the company’s biggest investment is its people, because “the coaches are the product”.
“Last year alone we invested over S$50,000 in our team’s education. This year we plan to do the same,” he said.
Fitness studio UFIT, which has four locations, similarly eschews a pay-per-use or gym membership model, but for a different approach – a wider take on wellness that it calls a “circle of care”.
It has about 700 active clients who attend personal training or group fitness classes, and can also tap on the services of a physiotherapist, podiatrist or nutritionist as needed.
“We work more with clients who are paying for expertise and accountability, not just access to equipment and facilities,” said founder and COO Dean Ahmad.
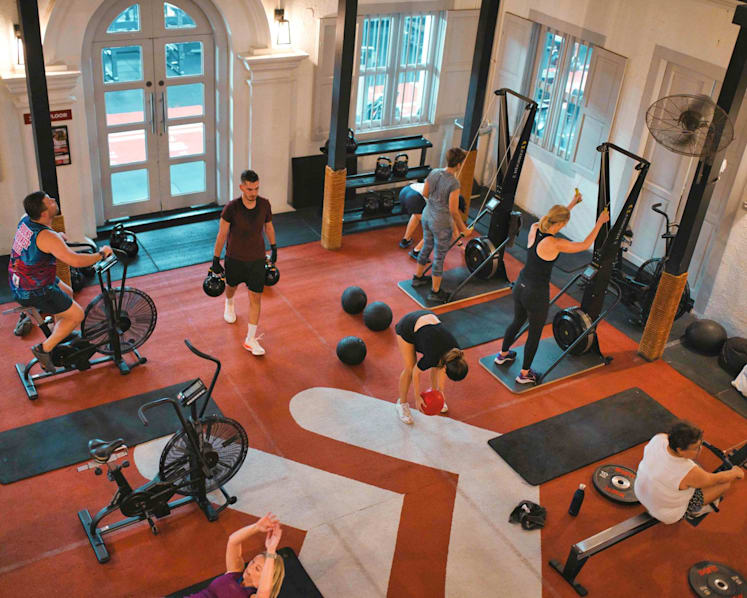
In stark contrast to the recent gym closures, Mr Ahmad said 2026 has been UFIT’s best year of business in the past five years. Event-based competitions and marathons are helping to drive people into gyms, but he also credited a focus on client retention by delivering measurable outcomes.
Mr Ahmad added that ActiveSG and condominium gyms are a form of “healthy market segmentation” and not a threat to boutique studios.
“They have absorbed a real slice of that demand, but it’s a very specific slice of that demographic that are price sensitive or that are convenience-based users, who are never going to pay for coaching or they’re not interested in that coaching model in the first place.”
CHANGING EXERCISE HABITS
Differentiation through service is also increasingly necessary because the way people exercise in Singapore has changed.
“Today’s consumers are far less likely to anchor their fitness routines around a single gym membership,” said Nanyang Polytechnic’s Mr Lee.
“Instead, they mix and match across different formats: using the condo gym, running outdoors, attending pilates classes, joining colleagues for pickleball, following free digital fitness programmes, or even travelling regionally for Hyrox competitions with their training communities.
“Fitness spending has become more fragmented, more flexible, and increasingly driven by experience, community and measurable outcomes.”
It is a challenge noted by Amore Fitness, which has been in business for more than 40 years. The homegrown chain runs women-only fitness studios and spas in nine locations around Singapore.
“Fitness is no longer just about choosing between one gym and another. Consumers can choose from 24-hour gyms, boutique studios, pilates, specialised training, outdoor activities and digital programmes, and many move between them,” said director Lim Kian Leong.
As women look for “more choice and more ways to fit fitness into their lives”, Amore has responded by introducing new brands for beauty, rest and recovery treatments, reformer pilates, and strength and functional training.
“Women don’t all want the same thing from fitness, and what they need can change over time. We want to give them the choice to find what works for them, while staying within a community they know,” he said.
Amore’s physical footprint reflects these ongoing shifts. It closed outlets at Jurong Point in 2023 and Seletar Mall in 2024, only to open at the CPF Jurong building in 2024 and Punggol Coast Mall in 2025.
Mr Lim said this was “part of running a physical fitness business in a changing market”, adding that the goal is not to have more locations, but the right ones.
“We regularly review our locations based on factors such as demand in the neighbourhood, rental rates and operating costs, as well as changes to the properties themselves,” he said.
“At the same time, we look at where we can serve members better, whether that means being closer to where they live and work, having a more accessible location or offering a space that better suits the way they want to exercise.”

RENTS AND COSTS
Internal competition aside, the fitness industry is not immune to the same cost factor squeezing other local businesses regardless of sector – rent.
High rents are the single biggest challenge that gyms face, according to Singapore Fitness Alliance’s Mr Tan. Margins in the fitness industry are traditionally thin at 15 to 25 per cent, with rents taking up 15 to 20 per cent of revenues.
“If rents now go up to 30 to 40 per cent of revenues, and other costs like manpower and utilities also go up, what is there for the businesses to take home?”
He traced this situation to more commercial properties being owned by real estate investment trusts, or REITs, where he said landlords must show year-on-year increases in rental yields.
“Rarely can you now find instances where your unit is owned by an individual with whom you can have reasonable discussions on rents. Rental negotiations are often cold and without emotion,” he said.
Many leases also have a gross turnover component, where rent is tied to sales. “If the landlord sees that you are doing well, you can almost surely expect a significant increase in your rent at the next lease renewal,” he added.
And the costs can stack up quickly. Operating expenses come up to about S$40,000 a month at Unstoppable Fitness, a roughly 4,000 sq ft bodybuilding gym in Shenton Way.
“Beyond rent, there are utilities, business loans, manpower, cleaning, laundry, equipment maintenance and repairs, software, marketing and many other recurring expenses,” founder and owner Luke Yeo said.
About S$1.2 million has been invested into building and operating the gym since it opened in 2022.
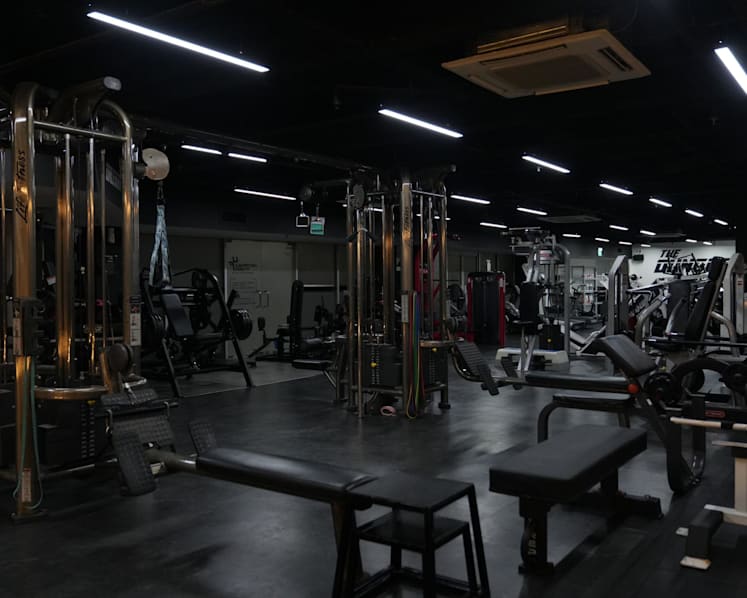
To Mr Yeo, the amount of capital being pumped into the fitness industry by well-funded gym operators is a major change that is intensifying competition.
A premium commercial gym machine can easily cost around S$15,000 to S$20,000, not including taxes, transport and installation costs, said Mr Yeo, adding that he is seeing more of such equipment in local gyms.
Gym operators are also spending heavily on renovation and amenities because customer expectations have changed, he said.
Differences between two pieces of gym equipment may be hard to spot, but what clients do see immediately are a gym’s size and appearance, showers and changing rooms and overall environment, he said.
“An independent operator isn’t competing only on membership price anymore. You’re competing on equipment, design, convenience, amenities, technology, community, branding and the overall experience.”
Mr Yeo pointed to branding and visibility as his pain points.
“A trainer with more experience does not automatically get more clients, and a gym with better equipment does not automatically get more members. People first need to know you exist, understand what you offer and trust your brand.”
But the bodybuilder, whose own training journey began in ActiveSG facilities, leans into the rivalry.
“I don’t necessarily think competition is a bad thing. It forces every operator, including us, to continuously improve and give customers a reason to choose us.”
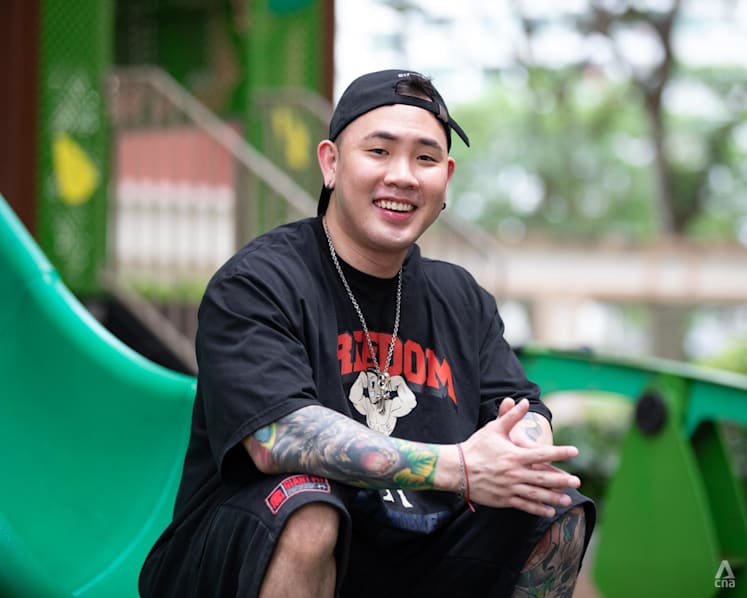
Source: CNA/dv(cy)
Sign up for our newsletters
Get the CNA app
Stay updated with notifications for breaking news and our best stories
Get WhatsApp alerts
Join our channel for the top reads for the day on your preferred chat app
Get bite-sized news via a new
cards interface. Give it a try.
Click here to return to FAST
Tap here to return to FAST
FAST