Skip NavigationMarketsBusinessInvestingTechPolitics & PolicyVideoWatchlistInvesting Club PRO
 LivestreamMenuU.S. Treasurys are returning to favor as a safe haven play that sidesteps investors’ worries over a shaky economy and the future of equity and credit investments beholden to the data center build-out. Until a few weeks ago, if you woke up to higher oil prices, you could count on higher Treasury yields and lower stock futures due to inflation fears. Monitoring oil was the key to anticipating bond and stock movements. Recently, this correlation has broken down. On Thursday, front-month Brent crude futures closed up by 4%, while 10-year Treasury yields were lower by 18 basis points with the S & P 500 index down 1.2%. There are several reasons for this divergence, some of which might be based on short-term positioning and others which may reflect longer-term changes. You might forgive anyone under 40 for ever even thinking that bonds were a good investment. For 15 years multiple rounds of quantitative easing kept yields suppressed below 3% and often even close to zero, returns which are hardly competitive with stocks. Then for the past five years, we have seen the worst long-term bond bear market since the days of Alexander Hamilton as yields rerated. US10Y ALL mountain 10-Year Treasury yield, long term While it is tempting to extrapolate recent poor performance into a forecast for ever-higher yields, current levels represent a reversion to the mean. In reality, 10-year yields have simply returned to historical norms, hovering just above their 100-year moving average. The end of the stock rotational trade Meanwhile, investors are starting to rethink the A.I. trade. For most of the year it has all been about rotation within stock sectors. If you were worried about the massive, front-loaded capital expenditures of the hyperscalers and their ability to quickly monetize their investments you sold these stocks and bought semiconductors which would profit from the expenditure. If you thought you were over-exposed to the A.I. trade, you rotated into stocks that weren’t as exposed, largely ignoring the reality that a broader A.I. slowdown could ultimately compromise the entire economy. “It’s been almost a full year since the last 80%+ downside volume day on the NYSE,” writes Jonathan Krinsky, chief market technician at BTIG in a recent note. TLT .SPX 3M mountain iShares 20+ Year Treasury Bond ETF vs. S & P 500, 3 months That could change if investors start rotating out of stocks and into bonds instead of just piling into other stock sectors during periods of uncertainty. Credit now matters And if you are going to rotate into bonds, you might want to avoid corporates, many of which have the same exposures to the A.I. build-out. The theory that hyper-profitable data center expansions will neutralize higher borrowing costs, and that deep-pocketed bond investors will readily absorb the wave of new debt issuance is being tested. Suddenly corporate bonds priced for a super low yield environment at record-tight spreads didn’t look so appealing and spreads began to widen. The pain has been felt most acutely in the riskier credits with high-yield spreads rising about 70 basis points since late September. Corporate bonds with CCC or lower ratings, the junkiest of the junk, have seen spreads increase by over 200 basis points over the same time frame. Fiscal issues are relative As the U.S. national debt hit $40 trillion this summer, investors began to demand higher returns to finance growing borrowing needs. While the near-term deficit trajectory hasn’t changed materially this year, the government’s interest expense could rise if rates remain elevated or push even higher. If interest expense exceeds nominal GDP growth, a debt spiral could occur. Ultimately the U.S. is years away from such a potential scenario, but other countries such as France face such a reality now. The bonds of countries with more serious fiscal issues have become unownable for some investors and U.S. Treasurys have benefited from a rotation as a result. “For the first time in a while, Treasurys are enjoying haven status. You have weakness in tech, an escalation of risk in the Middle East and higher oil. On a relative basis Treasurys start to look like the safe place to hide again in the short term,” writes Larry Holzenthaler, senior portfolio manager, fixed income at Catalyst Funds. Slowly the demand started to pick up when 10-year yields reached 5.3%. At those levels pension funds targeting a 6% return can allocate a lot more of their investments towards fixed income at lower risk. US10Y YTD mountain 10-year Treasury yield, YTD Now the rush to Treasurys has picked up steam. The psychological 5% yield which served as a technical level to sell bonds last month now has the opposite effect with FOMO gripping investors who are wondering if they have missed out on a plus-5% risk free return. A cyclical or secular shift? Near-term AI uncertainty and a cluster of imminent catalysts which I highlighted recently could spark robust Treasury demand over the coming month, but longer term the jury is still out on whether investors will swap the guaranteed return of current yields of Treasurys held to maturity for a bet on an A.I.-based future. “We do still believe that hiding in Treasurys is a risky move longer term. You still have fiscal concerns and high inflation. Unless you’re positioning for a recession, we believe assets like short duration corporate credit offer a more optimal risk/return,” said Holzenthaler.Read More
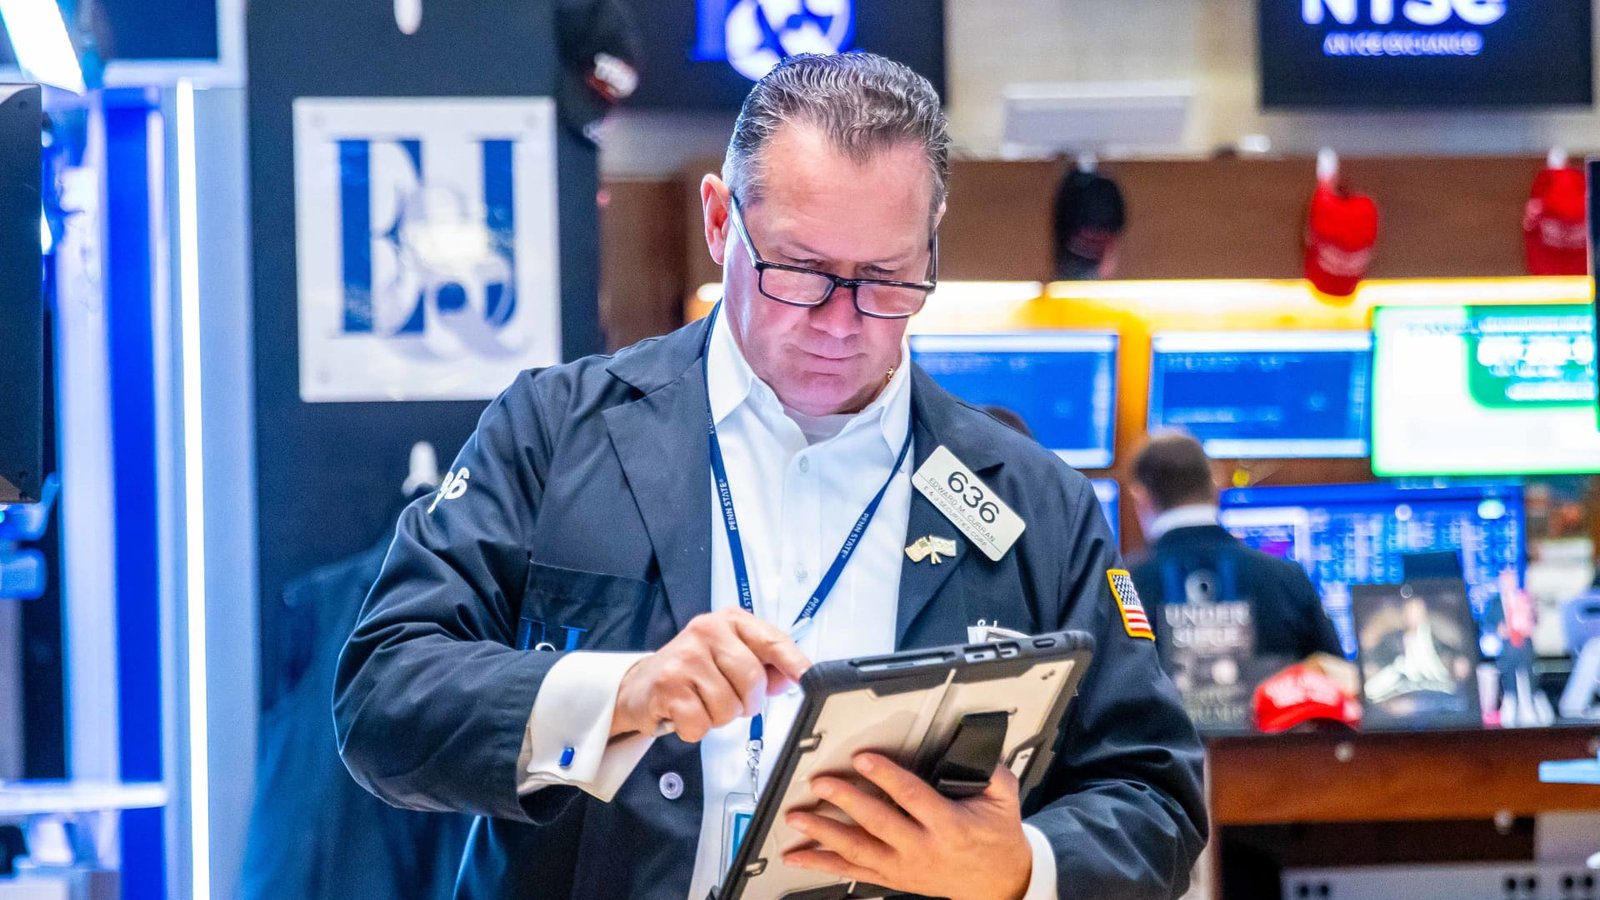
Why investors are moving back into Treasurys
U.S. Treasurys are returning to favor as a safe haven play that sidesteps investors’ worries over a shaky economy and the future of the data center build-out.

by
Read Time
About the Author

Previous Post
Next Post
Leave a Reply
Latest News
Stay Connected
Categories
BBC News CNA CNBC CNN International Deutsche Welle (DW) Euronews France 24 General Global & European Specialized & Regional
Tags
amp Artificial intelligence Asia Breaking News: Business Breaking News: Markets Breaking News: Politics Breaking News: Technology Business business news cent china cup Donald J. Trump Donald Trump economy European Union fast football France germany india Investment strategy iran Iran war markets People per politics return russia S&P 500 Index said Singapore spain Sport Stock markets technology trump ukraine United States US-Israel attack on Iran 2026 video War in Ukraine World World Cup 2026
About the Author
AF themes
Easy WordPress Websites Builder: Versatile Demos for Blogs, News, eCommerce and More – One-Click Import, No Coding! 1000+ Ready-made Templates for Stunning Newspaper, Magazine, Blog, and Publishing Websites.
Search the Archives
Access over the years of investigative journalism and breaking reports